
Challenge
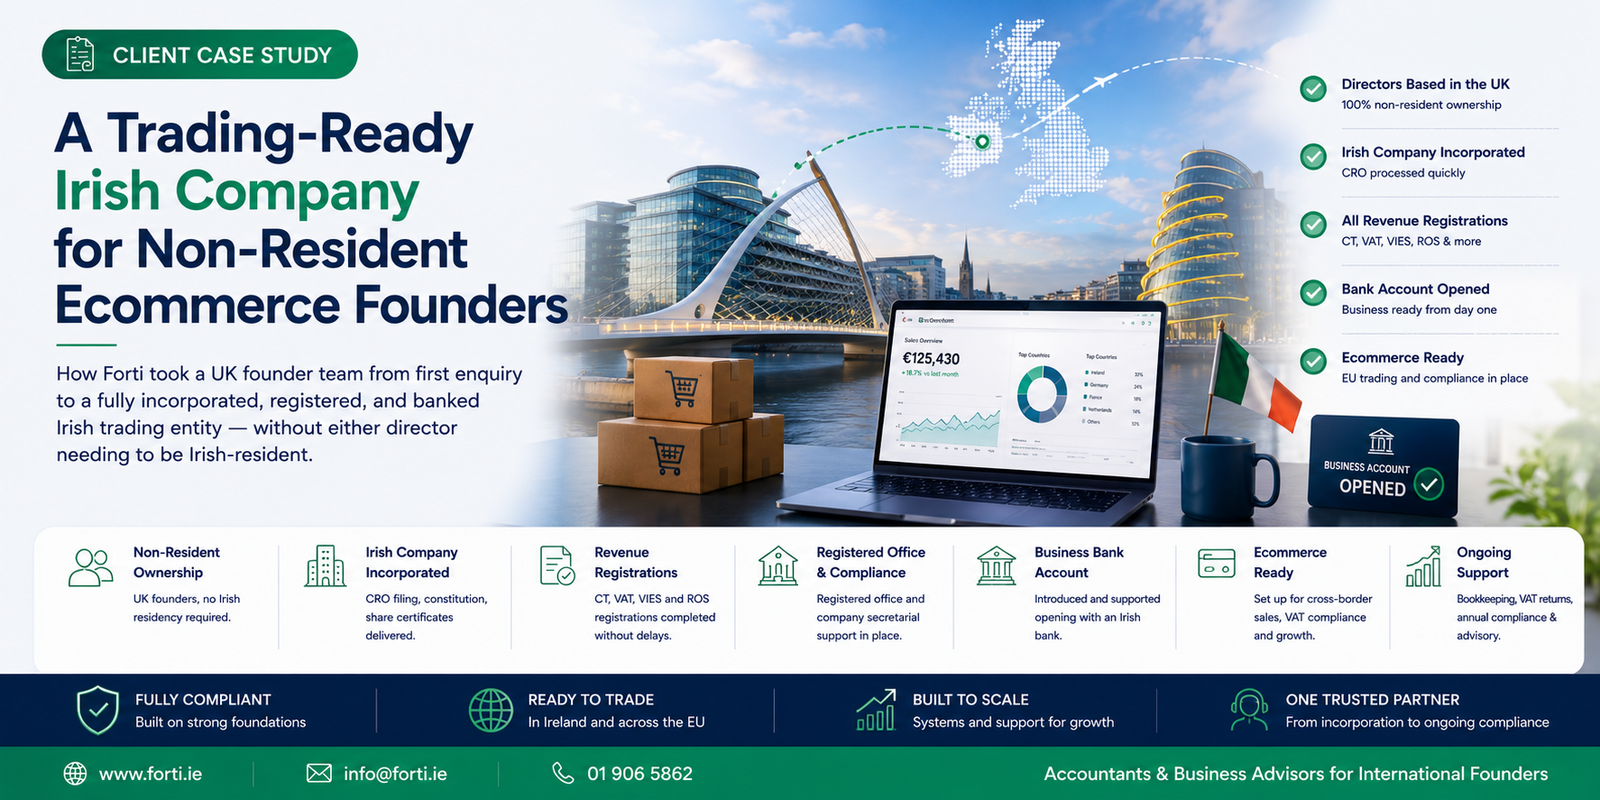
A UK-based husband-and-wife founder team came to Forti to set up a new Irish trading company ahead of expanding their ecommerce business across the EU. At the time of enquiry there was no trading activity yet, no Irish employees, and logistics were to be fully outsourced to an EU-based 3PL — they simply wanted a straightforward Irish-resident trading company with themselves as individual shareholders.
Their brief was specific: a fixed-fee package covering annual accounts and corporation tax (CT1), VAT returns plus EC sales and Intrastat once trading began, and CRO annual return and company secretarial support. As neither director planned to live in Ireland, they also needed clarity on what a non-resident-directed Irish company requires — including whether a compliance bond would be needed, and how to structure the business so it could still qualify for Ireland’s 12.5% trading tax rate rather than the 25% rate that applies without genuine local substance.
The wider business model added complexity: manufacturing based in the Czech Republic, fulfilment handled by a 3PL in the Netherlands, and the Irish entity intended to sit at the centre as the brand and contracting hub for EU-wide sales — a structure that needed to be right from day one, not patched together after trading started.
Forti's Approach
1. Recommending the right structure
Forti recommended its Non-Resident Plus package — built for founders who need an Irish company ready to trade, invoice, and hire immediately, without either director being Irish-resident. Alongside the formation itself, Forti advised on what’s required to achieve Ireland’s 12.5% trading tax rate: the Irish company needed to demonstrate genuine commercial control and substance in the state, meaning it would own the brand, IP, and customer contracts, and make key commercial decisions — pricing, marketing — from Ireland, even with manufacturing and fulfilment outsourced elsewhere.
The founders took time to weigh this against their group’s wider EU strategy before confirming Ireland as the jurisdiction and formally engaging Forti to proceed.
2. Non-resident director compliance and bonding
Because neither director was resident in Ireland or the EEA, the company needed a Section 137 non-resident director bond before it could be validly incorporated. Forti collected notarised verification-of-identity forms, passports, and proof of address for both directors, advised on the correct bond application route for a company that didn’t yet legally exist, and processed the bond through Aviva — issued and lodged with the CRO within roughly three weeks of the engagement letter being signed.
3. Incorporation and a proactive registration strategy
Once incorporated, Forti registered the company for Corporation Tax, VAT, VIES (for B2B transactions with EU suppliers and logistics partners), OSS (the One Stop Shop scheme for B2C EU ecommerce sales), and the Register of Beneficial Ownership (RBO) — registering proactively ahead of trading to avoid the administrative penalties that can follow a late application once sales begin.
Equally important was what Forti didn’t register the company for: IOSS, EORI, Customs & Excise, and Postponed VAT Accounting were all assessed as unnecessary at this stage, since the supply chain is entirely intra-EU with no goods being imported from outside the bloc. Keeping the registration set matched to the actual business model avoided unnecessary compliance overhead.
4. Banking and ongoing support
Forti facilitated a direct introduction to a Revolut Business account executive to help the founders set up banking correctly configured for a standalone, non-resident-directed Irish entity, and confirmed that Revolut Business was an acceptable banking solution for the structure. Forti also confirmed that director dividends would not currently trigger PAYE obligations — a common point of confusion for non-resident director structures.
An ongoing monthly bookkeeping and compliance package (€195 + VAT per month, covering bookkeeping, annual financial statements, and regulatory filings) was agreed to commence once the business begins actively trading, so the founders aren’t paying for services ahead of revenue.