Pradeep Dabas, ACCA, MIoD, MBA
Pradeep Dabas is a Chartered Certified Accountant (ACCA), Member of the Institute of Directors (MIoD), and founder of Forti, a Dublin-based accountancy and advisory firm helping Irish entrepreneurs and SMEs with company formation, bookkeeping, and compliance. He is also the founder of Salt Marketing, a Dublin-based digital marketing agency. Holding an MBA in Marketing and an ACCA qualification — both achieved in Dublin — and with over 20 years of experience in finance and business, Pradeep brings a rare combination of financial rigour and commercial thinking to every client relationship. He is also the creator of The Mentor Academy, an online education platform specialising in finance courses designed to help entrepreneurs and professionals take control of their financial future. Forti is based in Sandyford, Dublin and works with businesses across Ireland.
View all posts by Pradeep Dabas →
Ireland’s Budget 2025 introduces transformative tax changes aimed at providing significant financial relief and incentives to individuals, families, and businesses. This comprehensive overview summarises the key updates and shows how you can take advantage of them.
Introduction: Why Budget 2025 Matters
With rising living costs and increased pressure on businesses to innovate and grow, the Irish government has implemented targeted tax measures to relieve financial pressures and boost economic activity. These changes demonstrate a commitment to assisting individuals, families, and businesses in fostering a more robust and equitable economy.
Updates for Individuals
1. Increased Personal Tax Credits
From January 1, 2025, several personal tax credits will see notable increases:
Personal Tax Credit: Up by €125 to €2,000
Employee Tax Credit: Up by €125 to €2,000
Earned Income Tax Credit: Up by €125 to €2,000
Other enhanced credits include:
Home Carer Tax Credit: Increased by €150 to €1,950
Single Person Child Carer Tax Credit: Raised by €150 to €1,900
Incapacitated Child Tax Credit: Up by €300 to €3,800
Blind Person’s Tax Credit: Increased by €300 to €1,950
Dependent Relative Tax Credit: Up by €60 to €305
These changes aim to alleviate financial pressures, especially for caregivers, single parents, and families with special needs.
2. Expanded Tax Bands
The standard rate tax band increases by €2,000, allowing individuals to earn up to €44,000 before being subject to higher tax rates. This adjustment translates into greater take-home pay for workers.
Example Scenario: Case Study of a Married Couple
To illustrate the impact of the 2025 tax changes, let’s consider a case study of a married couple with a combined annual income of €144,000, split equally between both spouses (€72,000 each).
Tax Calculation for 2025:
Standard Rate Band: €88,000 taxed at 20%
Remaining Income: €56,000 taxed at 40%
Income Tax:
(€88,000 x 20%) + (€56,000 x 40%) = €17,600 + €22,400 = €40,000
Tax Credits:
Personal Tax Credit: €4,000 (€2,000 x 2)
Employee Tax Credit: €4,000 (€2,000 x 2)
Total Tax Credits: €8,000
Net Income Tax:
€40,000 – €8,000 = €32,000
Universal Social Charge (USC):
0.5% on first €12,012 = €60.06
2% on next €15,370 = €307.40
3% on next €42,662 = €1,279.86
8% on balance €73,956 = €5,916.48
Total USC: €7,563.80
Pay Related Social Insurance (PRSI):
4% of €144,000 = €5,760
Total Deductions:
Income Tax: €32,000
USC: €7,563.80
PRSI: €5,760
Total: €45,323.80
Take-Home Income for 2025:
€144,000 – €45,323.80 = €98,676.20
Savings Compared to 2024:
The main changes affecting this couple are:
Increased Standard Rate Band: €88,000 in 2025 vs. €84,000 in 2024
Increased Tax Credits: €2,000 per person in 2025 vs. €1,875 in 2024
Reduced USC Rate: 3% in 2025 vs. 4% in 2024 for income between €27,382 and €70,044
Estimated Savings:
€800 from the increased standard rate band
€250 from increased tax credits
€426 from the USC rate reduction
Total Estimated Savings: €1,476
Therefore, this married couple with a combined income of €144,000 can expect to take home approximately €98,676.20 in 2025, with estimated savings of around €1,476 compared to 2024 due to the new tax measures.
3. Rent Tax Credit
Renters benefit from a significant increase in the Rent Tax Credit:
Individuals: Up to €1,000
Jointly Assessed Couples: Up to €2,000
This measure provides relief amid rising housing costs.
4. Universal Social Charge (USC) Reduction
The 4% USC rate is reduced to 3%, applying to income between €27,382 and €70,044. This change offers additional net income for many employees.
Business Tax Credits and Incentives
Budget 2025 extends significant support to businesses and entrepreneurs through enhanced credits and incentives.
1. Employment Investment Incentive (EII) and Start-Up Relief
EII Scheme: Investors can now claim relief on up to €1 million annually, doubled from the previous limit of €500,000.
SURE Extension: Relief continues through December 31, 2026, encouraging start-up growth.
2. Enhanced R&D Tax Credit
First-Year Payment Threshold: Increased by 50% to €75,000.
This provides extra cash flow support for innovative companies.
3. Relief for Listing Expenses
Companies can deduct up to €1 million in expenses related to an initial stock exchange listing.
This measure promotes growth and access to capital markets.
How to Benefit from Budget 2025
For Individuals:
Review your tax status and claim all eligible credits.
Renters should apply for the increased Rent Tax Credit.
If self-employed or earning non-PAYE income, ensure to claim the enhanced Earned Income Tax Credit.
For Businesses:
Leverage the enhanced R&D tax credit to fund innovation.
Consider listing your company on the stock exchange to utilise the new relief for listing expenses.
Encourage investors to take advantage of the increased EII limits.
Conclusion: A Brighter Financial Future
Ireland’s Budget 2025 brings tangible benefits for individuals and businesses. By proactively managing your tax affairs and consulting a professional, you can maximise the advantages of these changes. These measures not only ease financial pressures but also drive economic growth, setting the stage for a more prosperous Ireland.
Companies with under 10 employees make up 92.3% of all businesses in Ireland, and control over two-thirds of the nation’s workforce. You would be right to call them the beating heart of the Emerald Isle.
As of 2023, there were over 309,000 active Small and Medium Enterprises (SMEs). That’s everything from cafes and local Mom-n-Pop stores in Dublin, tech startups in Cork to grocery stores in the countryside. Not all is well with many of these though.
Owners are on their wits end, taking on multiple roles at the same time. The manager is running affairs. The marketer pushing out ads online and on the ground. Bookkeeping and trying to track every penny. These entrepreneurs bear the heavy burden of bookkeeping. And as it turns out, this is usually more costly in the long run.
The Money Math
Cash flow issues can bring your business to a complete halt. How are Irish SMEs affected?
Delayed payments: Over 57% say customers are taking longer to settle invoices. For many, it takes two to three days just to see payments hit their accounts.
Bad debts: 30% of the business have to write this off every year. On average, this results in a loss of €21,076 that could have been reinvested in the business.
Lack of cash flow: More than one in five SMEs admit they simply don’t have enough cash flow to expand. The ambition is there, but the money isn’t.
Difficulty accessing finance: Struggling to secure funding? You’re not alone—27% of the SMEssay getting access to finance is their biggest hurdle.
Day-to-day cash flow: Even larger SMEs with turnovers between €10 million and €25 million aren’t immune. 53% of them say managing day-to-day cash flow is still a challenge.
Professional accountants come in to put the house (business) in order, for you to better manage the situation.
How Professional Accountants Help Your Business
1. Comply With Irish Tax Laws
Taxes. Love or hate them, they can’t be avoided. Miss a deadline or file incorrectly, and suddenly you’re in the hook for thousands of euros.
The tax system here is one of the most detailed in Europe. From VAT registration to payroll taxes, there are plenty of rules that you need to keep up with.
Professional accountants ensure:
Accurate and timely filing of VAT returns, PAYE, and Corporation Tax.
Identification of tax breaks like the R&D Tax Credit, Capital Allowances, and Entrepreneur Relief.
Tax strategies that save your business thousands of euros annually.
Example Savings:
Tax Relief Opportunities: Ireland’s corporate tax rate is just 12.5% on trading income. You can tap into reliefs and deductions to shrink your taxable income even further.
Capital Allowances: Got fixed assets in your business? Reviewing them could unlock big tax savings and give your SME a financial boost.
Entrepreneur Relief: It lets you pay a reduced Capital Gains Tax (CGT) rate of just 10% on qualifying assets—up to €1 million. That’s a massive incentive to grow and invest in your business.
Foreign Earnings Deduction (FED): Travel often for work? If you spend 40 qualifying days in emerging markets outside Ireland, you could benefit from this relief. It caps at €35,000, potentially saving you up to €14,000 in taxes at a 40% tax rate.
Professional accountants ensure you file everything on time—be it VAT returns, PAYE, or Corporation Tax. No more panicked submissions. No more fines.
They’re also experts in finding tax breaks and incentives. Did you know about the R&D tax credit for small businesses? Or that some VAT exemptions could apply to you? Probably not. But your accountant does.
Know exactly where your business stands, month by month. Accountants provide:
Clear income and expense tracking.
Insights to identify profitable product lines and eliminate wasteful spending.
Accurate reports to secure loans, attract investors, and plan for growth. That includes identifying profitable product lines and cutting wasteful expenses.
Without reliable data, decision-making becomes a guessing game—and that’s a risk no SME can afford.
3. Save Time and Focus on Growth
How much time do you spend chasing invoices, reconciling statements, or sorting payroll—it’s an endless to-do list. If you’re like most small business owners, it’s too much.
Outsourcing your accounting means:
No more late nights over spreadsheets.
Reduced errors that cost you money.
More time to focus on growing your business, serving customers, and innovating.
Time is money. Why waste it on admin when you could spend it where it counts?
And the risks aren’t even worth it. Mistakes in your accounting can lead to missed tax deadlines, penalties, or more trouble with your cashflow.
However, handing over your accounts to an expert means no more late nights stressing over spreadsheets. It frees up your time, reduces errors, and lets you focus on what matters most—running your business.
Time is your most valuable resource. Why not spend it where it counts?
4. Work Smarter with Cloud-Based Tools
Modern accounting tools automate repetitive tasks like invoicing, expense tracking, and reconciliations while providing real-time financial insights. Accountants can:
Set up and integrate cloud-based accounting software.
Ensure accurate, up-to-date financial reporting.
If you’re not using cloud-based applications, you’re missing out on a massive opportunity to streamline your operations.
They automate tedious tasks like invoicing, expense tracking, and bank reconciliations, and also give you real-time access to your financial data.
Professional accountants use these tools to provide you with accurate, up-to-date information. They can also help you integrate accounting software with other business systems.
5. Strategic Financial Advice-More than just numbers
Professional accountants do more than crunch numbers. They act as trusted advisors who help you:
Project cash flow for the next quarter.
Identify financial leaks and cost-saving opportunities.
Plan expansions and map out strategies for growth.
You want to go into the next quarter with accurate cash flow projections. You’ll need to find financial leaks in your operations, and put together strategies to plug them. Are there areas you can cut costs in your operations?
Professional accountants find out all that for you, identifying trends in your books, highlighting areas that need attention, giving you a heads-up on risks, and mapping out the best path forward. It all helps your bottom line.
Planning to expand? They’ll help you evaluate the benefits and create a strategy that works for your goals. Looking for ways to boost cash flow? They’ll recommend tailored solutions to keep things running smoothly.
This kind of support turns an accountant into a trusted advisor—a true partner invested in your success. Having expert guidance on financial trends, risks, and opportunities empowers you to make confident decisions.
Outsourcing Accounting Saves You Money—Here’s How
Outsourcing Accounting Saves You Money
According to SalaryExpert, hiring an in-house accounting team in Ireland is expensive. For example:
Bookkeepers: Earn an average of €41,037 annually. Entry-level positions start around €30,192, while those with significant experience can earn up to €50,070.
Financial Accountants: Cost between €45,000–€91,000, depending on experience.
Financial Controllers: We’re talking an average of €64,516 per year, with higher amounts in major cities like Dublin.
Additionally, by identifying errors before they become costly ones, you can avoid fines and penalties that could have significantly reduced your profits.
Factoring in all expenses such as wages, benefits, paid time off, IT support, office space, and even overtime, the true cost of establishing an in-house accounting team can be significantly high.
By outsourcing:
You only pay for the services you need (e.g., monthly bookkeeping, year-end tax filings).
You avoid costly mistakes and penalties.
SMEs save an average of €12,000 per year compared to hiring full-time staff.
Only hire for the services you need, whether that’s monthly bookkeeping or year-end tax filings.
SMEs face challenges like cash flow issues, delayed payments, and difficulty accessing finance. Managing taxes, bookkeeping, and financial reporting alone often leads to costly mistakes and wasted time.
How Professional Accountants Help:
Stay Compliant: Timely and accurate tax filings while maximising reliefs like R&D Tax Credits, Entrepreneur Relief, and VAT exemptions.
Improve Financial Reporting: Gain clear insights to track income, reduce expenses, and plan for growth.
Save Time: Eliminate time-consuming admin, freeing you to focus on growing your business.
Strategic Advice: Accountants act as trusted advisors, identifying trends, risks, and growth opportunities.
Cost-Effective Solution: Outsourcing accounting saves SMEs an average of €12,000 annually compared to hiring an in-house team.
With professional accounting support, small business owners can reduce stress, save time, comply with tax laws, and make smarter financial decisions to grow their business.
Get Accounting Help Today
Running a small business is already hard. Doing it without professional accounting makes it a recipe for stress and missed opportunities.
Avoid the headaches. Save time. Save money. Comply with the country’s tax laws. Get advice that helps your business thrive.We’ve got all that and more here at Forti. Email us at info@forti.ie or call us at 01-9065862 and let’s talk about how we can help.
It’s more important than ever to understand how your business makes money. For Irish business owners, the world of accounting can be challenging to understand, especially since there is really no pricing transparency offered by either bookkeepers or accountants. It’s important to know what to expect in terms of prices and services, whether you’re a new business trying to build a strong financial base or an existing one trying to make your accounts more efficient. This article will explain how firms like Forti Accountants are changing the way businesses see value and how they set prices for accounting services in Ireland. Our aim is to give you the information you need to make smart choices that will help your business grow by looking at competitive pricing models, unique service offerings, and the benefits of specialised solutions. Let’s dive into the world of accounting services and find out how to get the most out of your money so you can be successful in 2025 and beyond.
Business owners face a lot of stress from their accountants. Having a reliable accounting partner is more crucial than ever in today’s competitive world. Forti Accountants, an innovative accounting practice based in Dublin, is looking to redefine traditional financial management by offering tailored solutions that combine expertise and technology together. We have customised accounting plans for startups, SME, or established corporations. Forti Accountants may be the partner you need to simplify compliance, optimise tax planning, and drive business growth.
Comprehensive Services Tailored for Modern Businesses
Before we dive into the pricing structure, lets understand the activities that needs to be carried out through out the year by accountants.
Monthly Bookkeeping Activities
Effective monthly bookkeeping is the backbone of sound financial management. Here’s a detailed breakdown of essential activities:
1. Sales Management
Recording and categorising all sales transactions
Verifying invoice accuracy and completeness
Tracking sales by product, service, or customer segment
2. Purchase Tracking
Logging all business expenses and purchases
Categorizing expenses for tax efficiency
Monitoring supplier payments and terms
3. Bank Reconciliations
Matching bank statements with internal records
Identifying and resolving discrepancies
Ensuring all transactions are accounted for
4. Creditors Reconciliation
Reviewing and updating accounts payable
Aging analysis of payables
Identifying opportunities for early payment discounts
Managing employee additions, removals, and changes
Submitting payroll returns to Revenue
3. Year-End Procedures
Conducting comprehensive year-end reconciliations
Preparing closing entries and adjustments
Ensuring books are audit-ready
4. Financial Statements Preparation
Compiling profit and loss statements
Preparing balance sheets
Creating cash flow statements
5. Corporation Tax Return (CT1) Filing
Calculating corporation tax liability
Preparing and submitting CT1 return
Advising on tax planning strategies
6. Annual Return (B1) Filing
Preparing and submitting annual return to CRO
Ensuring compliance with company law requirements
Updating company records as necessary
7. Personal Tax Returns
Preparing and filing Form 11 for directors and shareholders
Advising on personal tax planning
Ensuring compliance with personal tax obligations
These comprehensive services ensure that your company keeps accurate financial records, meets all regulatory requirements, and has the financial insights required for sound decision-making.
How much time should a Bookkeeper spend keeping the records up-to-date?
Bookkeepers typically require varying amounts of time to maintain accounts, depending on the business’s complexity.
Time Estimates by Business Size
Small Businesses: Approximately 5 hours per month
Around 20 transactions monthly
Estimated 3-5 minutes per transaction
Medium-Sized Businesses: Approximately 10 hours per month
Higher transaction volume
More complex reconciliation processes
Large Businesses: Up to 20 hours per month
Extensive transaction records
Multiple reconciliation requirements
Key Factors Influencing Time Investment
Transaction Volume
Business Complexity
Accounting System Efficiency
Automation Level
Record-Keeping Quality
Recommended Practices
Implement automation tools
Use accounting software with bank feed integrations
Maintain organized financial records
Perform reconciliations monthly
Track time spent on bookkeeping tasks
Year-End Accounting Fees structure
Once the bookkeeping is done, next step is to file your accounts. A lot of business owners only engage accountants to file their year-end accounts. The fee may vary depending upon the complexity of the business, but here is q quick guide on what to expect:
Small Size Companies: Year-end accounting fees typically start from €500 to €800
Medium-Sized Companies: Fees range from €900 to €2,500.
Large Companies: Charges can be between €2,500 to €5,000 or more.
These fees generally cover:
Preparation and filing of annual financial statements
Corporation tax return filing
Preparation and submission of abridged financial statements
A lot of accountants now offer month-end packages that include year-end services, which may offer businesses better value and cash flow management.
Pro Tip: The accountant’s bill always depends on the quality bookkeeping done during the year. If it is not done right, you may carry the risk of unnecessary profit reporting and a risk for not being able to claim the relevant taxes. Once the books are smooth, most professional bookkeepers estimate spending about 3 hours per week per client, with the total time varying based on specific business needs and transaction complexity.
Pricing
Now let’s talk about the pricing. Bookkeeping tasks are sometimes extremely time-consuming. A lot of business owners are not proficient at keeping records; what’s coming out, what’s coming in, bank transactions, etc. can be sometimes overwhelming, especially when there is pressure from the operations to get the core tasks done.
Whatever the situation is, pricing should be transparent and agreed upon with the accountants, and there shouldn’t be any surprises. Business owners should use the technology to keep track of all the transactions.
Our pricing model is straight-forward. Our accounting fee, which includes all the above-mentioned tasks, is approximately 1% of your annual turnover, no surprises.
Forti Accountants likely provides competitive rates with bundled packages that include additional services. The transparent pricing structure ensures that clients understand exactly what they are paying for, avoiding the hidden fees common with traditional firms.
A comparison table of Forti Accountants’ pricing versus typical industry rates:
Service
Forti Accountants
Industry Average
Basic Accounting (Sole Traders)
From €88/month
From €250/month
Accounting (Limited Companies)
From €150/month
From €350/month
E-Commerce Accounting
From €150/month
From €350/month
Bookkeeping
From €40/hour
From €50/hour
Company Registration
From €250
From €300
Payroll Services
From €25 per person
From €50/month for up to 6 payslips
Expert Advice
From €100/hour
From €120-€150/hour
Customised Accounting
1-2% of turnover (min From €88/month)
Varies, often higher fixed rates
Company Secretarial Services
From €450/year
Varies, often From €500-€700/year
Virtual Office Services
From €50/month
Varies, often From €75-€100/month
Note: Industry averages are approximations that may differ depending on the firm size, location, and particular services provided. Forti’s prices seem more reasonable overall, particularly for small and medium-sized enterprises.
FORTI’s comprehensive services
Forti Accountants offers a variety of services tailored to the specific needs of businesses at various stages of growth. Here’s a closer look at what they offer:
1. Core Accounting Services
These essential services help businesses stay compliant with Irish regulations:
Annual Accounts Preparation: Ensuring accurate reporting for stakeholders and regulatory bodies.
Tax Return Filing: Covering corporation tax, VAT, and income tax for individuals and businesses.
Payroll Processing: Efficient handling of employee payments and tax obligations.
Bookkeeping: Maintaining accurate financial records to track income and expenses.
2. Advanced Financial Services
For businesses aiming to scale or optimise operations, Forti Accountants offers:
Financial Consulting and Advisory: Tailored advice to support strategic decision-making.
Budget Forecasting and Analysis: Helping businesses plan for future growth and challenges.
Tax Planning and Optimisation: Identifying opportunities for savings while staying compliant.
Business Growth Strategies: Expert guidance on expansion and new market entry.
3. Technology-Driven Solutions
Forti Accountants leverages modern tools to enhance efficiency:
Cloud Accounting: Real-time access to your financial data, enabling better decision-making.
Digital Financial Management Tools: Automated processes for accuracy and time savings.
Operations Analysis: Identifying inefficiencies and opportunities using data-driven insights.
4. Compliance and Regulatory Support
Navigating regulatory requirements can be challenging, but Forti Accountants simplifies the process:
Company Setup Assistance: Seamless support for new businesses entering the market.
Annual Return Filing: Ensuring compliance with the Companies Registration Office (CRO).
Regulatory Compliance: Ongoing support to meet Irish legal and tax obligations.
5. Additional Value-Added Services
Forti Accountants goes beyond traditional accounting by offering:
Business Performance Analysis: Regular tracking of key performance indicators (KPIs).
Controller and CFO Services: Strategic financial leadership for growing companies.
Workshops and Resources: Empowering clients with financial knowledge and skills.
How Forti Accountants Stands Out
Forti Accountants distinguishes itself by addressing common pain points in the accounting industry.
1. Technology Integration
Unlike traditional firms that are still transitioning to digital solutions, Forti Accountants was created with modern businesses in mind. We are currently working on the new software, which will report in real-time backed up by AI. The cloud-based tools will be able to provide real-time financial insights, enabling faster decision-making and more accurate reporting.
2. Tailored Packages
Keeping different sizes in mind, which are based on the annual turnover and monthly transactions, Forti Accountants offers customisable service packages. This flexibility allows businesses to pay for only what they need, making their services accessible to businesses of all sizes. Further benefits include the monthly payments, which take off the burden of once-off accounting fee.
3. Industry Specialization
Forti Accountants focusses on providing industry-specific expertise to assist clients in effectively navigating niche challenges and opportunities.
4. Proactive Financial Planning
Forti Accountants places a premium on proactive strategies in addition to compliance. Their proactive approach ensures clients are prepared for both opportunities and challenges.
5. Client Education
Forti Accountants stands out for empowering its clients with financial knowledge. Training sessions, workshops, and free resources assist businesses in making well-informed decisions.
Key Considerations for Business Owners
Consider the following when assessing Forti Accountants as your accounting partner:
Service Range: Does their offering align with your business needs?
Expertise: Do they have experience in your specific industry?
Technology: Are their digital solutions compatible with your processes?
Scalability: Can their services grow with your business?
Cost-Benefit: Are the benefits and savings worth the investment?
Personalised Attention: Will you receive tailored support and advice?
Are you ready to transform your accounting experience? Talk to one of our experts today to explore their services and how we could help you with your accounting needs.
Take the first step towards financial clarity and business success today!
Running an e-commerce business in Ireland provides exciting opportunities, but it also presents distinct bookkeeping challenges. For financial clarity and compliance, it is imperative to maintain effective bookkeeping in light of online sales, inventory management, and fluctuating cash flow. In this guide we will go over the basics of e commerce business bookkeeping, discussing procedures, typical mistakes, and recommended strategies. Additionally, discover how FORTI can assist with your e-commerce bookkeeping needs, allowing you to concentrate on expansion as we handle the details.
Why Bookkeeping Matters for E-Commerce Businesses
Bookkeeping is not merely a compliance obligation for e-commerce enterprises; it is a strategic asset. Here’s why it’s important:
1. Inventory Management
Accurate inventory tracking is essential for comprehending profit margins, guaranteeing appropriate stock levels, and preventing costly write-offs.
2. VAT Compliance
VAT on sales must be collected by Irish e-commerce companies. Maintaining accurate records helps you avoid fines by making sure you report and pay VAT accurately.
3. Cash Flow Management
Maintaining a healthy cash flow and reinvesting in growth requires accurate tracking of income and expenses when transaction volumes are high.
4. Financial Clarity for Decision-Making
Strategic decisions are aided by the insights that detailed records offer into profitable products, seasonal trends, and consumer purchasing patterns.
Key Bookkeeping Steps for E-Commerce Businesses
Here’s how to simplify your e-commerce bookkeeping step-by-step:
1. Set Up a Dedicated Business Bank Account
It’s essential to have a dedicated business bank account for all your e-commerce transactions to maintain a distinction between your business finances and make tracking easier while also complying with Irish tax laws.
2. Track All Sales and Income Sources
Ensure to keep track of all earnings received from sources such as sales from your website through third-party marketplaces, as well as other revenue streams. It’s important to monitor not only the income but also consider any fees and shipping costs to better understand the overall profitability of your business. Make sure you don’t just focus on how much you earn but also take into account any charges and shipping expenses to get a picture of how profitable your business is.
3. Record Cost of Goods Sold (COGS)
The expenses linked to creating or acquiring the goods you sell are reflected in your COGS (Cost of Goods Sold). It’s important to keep your COGS up to date to ensure the profitability and inventory valuation are accurate; this includes costs related to manufacturing processes such as shipping and warehousing expenses.
4. Manage Inventory Effectively
In the world of businesses, like e commerce stores and shops selling goods over the internet or other electronic platforms, inventories are a significant asset to manage well and keep track of properly to run a successful operation smoothly and effectively which includes maintaining precise records of available stock levels monitoring expenses and updating data for any inventory losses or reductions due to theft damage or other factors that may affect the overall inventory quantity The use of specialised software for inventory management can make this entire process easier by seamlessly connecting with your accounting system, allowing for better organisation and control over your business operations.
5. Record Expenses and Overheads
Remember to keep track of all your business costs, such as advertising expenses and hosting fees, along with shipping and software subscriptions, in order to maximise your deductions and lower your income effectively.
6. Track VAT on Sales and Purchases
Irish online businesses are required to apply VAT on transactions within the EU and ensure reporting of it by maintaining records of VAT on sales as well as purchases and expenses. Utilise accounting tools to streamline VAT calculations and schedule reminders for submitting VAT returns.
7. Reconcile Payment Gateway Fees
Make sure to factor in the transaction fees charged by payment gateways such as PayPal, Stripe, or credit card processors when reconciling the income with the sales figures.
8. Monitor Accounts Receivable and Payable
It’s crucial, for businesses that offer credit or have vendor accounts to keep an eye, on money owed and money coming due to ensure cash flow and prevent penalties for late payments.
9. Generate Monthly Financial Reports
Regular monthly reports that consist of profit and loss statements along, with balance sheets and cash flow statements offer insights, into the well being of your business entity.Use these reports to assess profitability and make informed business choices.
Common errors in e-commerce bookkeeping
1. Not Tracking Inventory Changes Accurately
Profit calculations may become erroneous if stock level fluctuations are ignored. Utilise software to keep tabs on inventory and make necessary record adjustments.
2. Failing to Reconcile Payment Gateway Fees
Payment gateway fees mount up. Ignoring the need to reconcile these fees may lead to unexpected discrepancies and inaccurate revenue tracking. If you dont record the expenses, you end up paying additional taxes.
3. Overlooking VAT Compliance
Inaccurately recording VAT on both domestic and EU sales can result in expensive fines and problems with Revenue compliance.
4. Not Separating Income Sources
Revenue can be easily misclassified when there are several sales channels. Better financial analysis and tax accuracy are made possible by tracking each source independently.
5. Inconsistent COGS Recording
Inaccurate profit margins and skewed financial statements are the results of inconsistent cost tracking. Update COGS monthly for accuracy on regular basis. Keep your books clean and health.
6. Neglecting to Record Small Expenses
Running a store involves minor costs, like packaging materials and software subscriptions that should be accurately tracked to gauge the actual profitability of the business.
Best Practices for Efficient E-Commerce Bookkeeping
Use E-Commerce Accounting Software
Accounting software tailored for e-commerce businesses, such as QuickBooks Commerce or Xero, allows seamless integration with sales platforms to automate inventory tracking and manage VAT and expenses efficiently without the need for data entry. Reducing errors significantly.
Implement Inventory Management Tools
Tools such as TradeGecko or the inventory management features integrated into Shopify assist in monitoring stock quantities and replenishment requirements while also managing costs of goods sold (COGS). This efficient system saves time. Effectively mitigates problems related to insufficient stock levels.
Schedule Monthly Financial Reviews
Regularly checking your statements every month enables you to identify patterns and manage your funds effectively while also making changes in a timely manner. Moreover, reviewing your finances on a regular basis ensures that you are well prepared for tax season with records that adhere to regulations.
Plan for VAT and Tax Payments
Online retail companies should remember to submit VAT returns on a basis and allocate funds each month to account for VAT and taxes so that they are ready when its time to make payments.
Work with a Bookkeeper Experienced in E-Commerce
Managing finances for e-commerce comes with its own set of hurdles to overcome—an accountant well acquainted with digital enterprises can navigate VAT issues and monitor inventory while assisting in optimising tax benefits.
Monthly Bookkeeping Checklist for E-Commerce Businesses
Your bookkeeping procedure can be streamlined and you can avoid missing any important steps by using a monthly checklist:
Task
Frequency
Completed (Y/N)
Record all sales and income sources
Weekly
Update inventory and COGS
Weekly
Record expenses and overheads
Weekly
Reconcile bank and payment gateway fees
Monthly
Track VAT on sales and purchases
Monthly
Generate profit and loss statement
Monthly
Review cash flow and inventory levels
Monthly
Prepare VAT return (if applicable)
Quarterly
Monthly and Annual Bookkeeping and Tax Compliance Activities
Monthly Bookkeeping Activities:
Sales Invoices and Revenue Recording
Purchase Invoices and Expense Tracking
Bank Account Reconciliation
Creditors Reconciliation (Supplier Balances)
Debtors Reconciliation (Customer Balances)
Payroll and PAYE Reconciliation
Loan Account Reconciliation
Other Reconciliation Tasks (e.g., Petty Cash, Intercompany Accounts)
Bi-Monthly and Year-End Tax & Compliance Activities:
Bi-Monthly VAT Returns (Cash or Accrual Basis Reconciliation)
Payroll Processing and Submissions
Year-End Financial Reconciliations
Preparation of Financial Statements
CT1 Corporate Tax Filing
B1 Annual Return Filing
Personal Income Tax Returns (Self-Assessment)
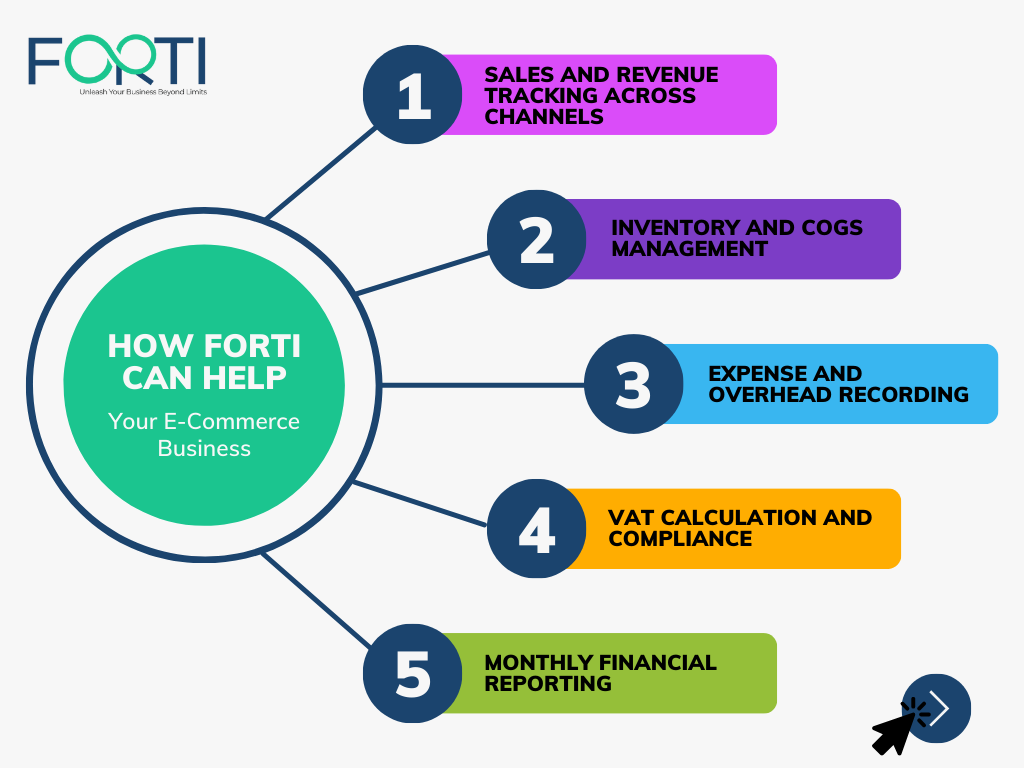
How FORTI Can Help Your E-Commerce Business
We recognise the requirements of online retail companies and offer tailored accounting solutions to simplify your financial processes and ensure precision and transparency for you to concentrate on expanding your enterprise.
Our Bookkeeping Services for E-Commerce Businesses Include:
Sales and Revenue Tracking Across Channels We keep a record of earnings from every sales source. Compare payment gateway charges to guarantee revenue calculations.
Inventory and COGS Management We make sure to keep our inventory records up-to-date and accurately calculate the cost of goods sold (COGS) to reflect our profit margins.
Expense and Overhead Recording We keep a record of every cost related to our business operations. From packaging expenses to marketing expenditures. To make sure that we cover all the expenses incurred.
VAT Calculation and Compliance We handle VAT computations for your sales in Ireland and the EU to guarantee reporting and submission to prevent any penalties.
Monthly Financial Reporting To help you understand the performance of your business, FORTI offers monthly balance sheets, cash flow reports, and profit and loss statements.
Document Management for Tax Compliance We prepare you for audits and tax filings by organising and safely storing all supporting documentation, including invoices and receipts.
Ready to streamline your e-commerce bookkeeping?
FORTI can handle the complexities of your e-commerce accounting. With our tailored bookkeeping solutions, you can maintain VAT compliance, manage inventory, and make data-driven growth decisions.
Limited companies in Ireland must maintain bookkeeping practices not for daily business activities but also to meet legal obligations as mandated by the law. Unlike traders, who have stringent reporting requirements compared to limited companies, such as filing annual financial statements and corporation tax returns along with payroll filings. To ensure accuracy and compliance, it’s essential to establish solid bookkeeping practices from the start. This guide serves as a resource for companies to grasp the significance of bookkeeping practices and lays out steps while pointing out common mistakes and offering best practices. Explore how FORTI can assist your business with customised accounting services, check these bookkeeping tips:
Monthly and Annual Bookkeeping and Tax Compliance Activities
Monthly Bookkeeping Activities:
Sales Invoices and Revenue Recording
Purchase Invoices and Expense Tracking
Bank Account Reconciliation
Creditors Reconciliation (Supplier Balances)
Debtors Reconciliation (Customer Balances)
Payroll and PAYE Reconciliation
Loan Account Reconciliation
Other Reconciliation Tasks (e.g., Petty Cash, Intercompany Accounts)
Bi-Monthly and Year-End Tax & Compliance Activities:
Bi-Monthly VAT Returns (Cash or Accrual Basis Reconciliation)
Payroll Processing and Submissions
Year-End Financial Reconciliations
Preparation of Financial Statements
CT1 Corporate Tax Filing
B1 Annual Return Filing
Personal Income Tax Returns (Self-Assessment)
Why Bookkeeping is Crucial for Limited Companies
Bookkeeping for limited companies in Ireland is more complicated than for sole traders. Here’s why effective bookkeeping is essential:
1. Legal Compliance
Under legislation, it is mandatory for companies to keep precise financial documentation and present yearly reports to both the Companies Registration Office (CRO) and the Revenue authorities.
2. Corporation and VAT tax
Maintaining records is crucial, for filing taxes and complying with Irish Revenue regulations to avoid penalties related to corporation tax and VAT returns.
3. Corporate Tax and VAT
Proper bookkeeping helps ensure accurate tax filings, including corporation tax and VAT returns, to avoid penalties and stay compliant with Irish Revenue requirements.
4. Financial Transparency
Detailed records provide stakeholders, such as shareholders and investors, with an accurate picture of the company’s financial health and performance.
5. Cash Flow Management
Proper bookkeeping ensures that cash flow is closely monitored, allowing your company to meet financial obligations while also planning for growth.
Key Bookkeeping Steps for Limited Companies
Here’s how to build a solid bookkeeping foundation for your limited company:
1. Separate Business and Personal Finances
It’s essential to follow this rule: All business dealings must be conducted using a corporate bank account, as mandated for limited companies. This practice eases accounting tasks. Guarantees transparency in records.
2. Keep track of all the money coming in and going out
Keep track of all transactions related to the business, from sales and expenses to loan repayments and investment income. Ensure that every transaction is categorised correctly to avoid misclassification, which can lead to incorrect tax filings.
3. Track Receivables and Payables
Keep an eye on outstanding invoices (receivables) and upcoming payments (payables). This is crucial for cash flow management and helps you avoid late fees or interest on overdue bills.
4. Manage Payroll Accurately
Limited companies’ payroll includes calculating employee pay, tax deductions, PRSI, and USC. Use a compliant payroll system to manage these tasks accurately, and ensure you file payroll taxes with Revenue on time.
5. Keep Detailed Records for VAT
If your company is registered for VAT, you must accurately track VAT on sales and purchases. Use accounting software to calculate VAT returns and set filing deadline reminders to avoid penalties.
6. Maintain Supporting Documentation
Irish Revenue mandates that you keep all supporting paperwork, such as receipts and contracts, for a period of six years and suggests using a document management system to store and organise these documents.
7. Reconcile Bank Statements Monthly
Reconciling your bank statements with your books every month ensures that your records are accurate and highlights any discrepancies early on. This is essential for maintaining reliable cash flow records.
8. Prepare Financial Statements
Limited companies are required to prepare financial statements, such as profit and loss statements, balance sheets, and cash flow statements. These statements give a snapshot of the company’s financial health and are crucial for decision-making and compliance.
Common Bookkeeping Mistakes to Avoid
1. Failing to Separate Business Transactions
Mixing personal and business finances can lead to serious bookkeeping issues, and it is against Irish accounting regulations for limited companies.
2. Ignoring Regular Reconciliation
Without monthly reconciliation, errors or missing transactions are easily overlooked, resulting in inaccuracies in financial reporting.
3. Misclassifying Expenses and Income
Incorrectly categorising transactions can lead to inaccurate tax filings and financial statements, affecting decision-making and tax liabilities.
4. Overlooking Payroll Compliance
Payroll compliance errors, such as incorrect deductions or late payments, can result in fines and reduce employee trust.
5. Inadequate VAT Tracking
Failure to properly track VAT on sales and expenses can result in errors in VAT returns, penalties, or overpayment/underpayment of VAT.
6. Neglecting Accounts Receivable and Payable Management
Poor receivables and payables management can put a strain on cash flow, making meeting financial obligations difficult.
7. Missing Documentation
Your tax liability may increase if you lose supporting documentation, which may cause problems during audits and result in missed deductions.
Best Practices for Efficient Bookkeeping in Limited Companies
1. Use Accounting Software
Accounting software simplifies bookkeeping tasks, such as invoicing, payroll, VAT calculations, and financial reporting. Popular options include Xero, Sage, and QuickBooks, which are designed to support compliance with Irish accounting standards. These software also uses platforms such as Hubdoc, which simplify your process of expense recording.
2. Schedule Monthly Financial Reviews
Sit down with your bookkeeper and review the monthly transactions. Monthly reviews provide an opportunity to examine your cash flow, track spending patterns, and address issues early. Making informed business decisions is also aided by routine financial reviews.
3. Work with a Professional Bookkeeper or Accountant
Taking the help of an expert means doing things more efficiently and quickly. With complex compliance requirements, many limited companies benefit from working with an experienced bookkeeper or accountant. Professionals can handle regulatory filings, tax compliance, and provide strategic financial advice. It also avoids any type of error that may arise from wrong expense categorisation.
4. Plan for Corporate Tax Payments
As a limited company, you’re required to pay corporation tax. Make smart financial decisions. A portion of income should be set aside for taxes throughout the year to avoid cash flow problems during tax season.
5. Implement a Document Management System
Organise your documents. A secure, organised document management system makes it easier to locate receipts, invoices, and other supporting documents when needed for audits or tax filings.
Monthly Bookkeeping Checklist for Limited Companies
A simple checklist can help ensure you don’t miss any essential bookkeeping tasks:
Task
Frequency
Completed (Y/N)
Record all income and expenses
Weekly
Save and organise receipts and invoices
Ongoing
Reconcile bank statements
Monthly
Track accounts receivable/payable
Weekly
Review payroll and tax deductions
Monthly
Prepare VAT calculations (if applicable)
Monthly
Generate financial statements
Monthly
Review cash flow and profit/loss
Monthly
This checklist can help streamline your bookkeeping, ensuring compliance and accuracy every month.
How FORTI Can Support Your Limited Company’s Bookkeeping
We recognise the challenges that come with managing bookkeeping for companies. Our comprehensive bookkeeping services are designed to handle everything from day-to-day recording to VAT returns and payroll management, ensuring your accounts are compliant and up-to-date.
Our Bookkeeping Services for Limited Companies Include:
Transaction Recording & Expense Tracking: We precisely document every transaction, classifying them to give a transparent financial picture.
Accounts Receivable & Payable Management: Our team monitors receivables and payables to help you manage cash flow and meet deadlines.
Payroll Compliance: We manage payroll, including tax deductions and PRSI, while adhering to Irish payroll regulations.
Monthly Reconciliations: Reconcilliations are the key exercise to keep the records clean and compliant. Regular reconciliations keep your accounts balanced, reducing errors and highlighting discrepancies early.
VAT Filing and Tax Preparation: We handle VAT calculations, track VAT on all relevant transactions, and prepare accurate tax filings to ensure your compliance.
Detailed Financial Reporting: FORTI provides monthly financial reports, such as profit and loss, balance sheets, and cash flow statements, to keep you up to date on your company’s financial health.
Document Management: We maintain a digital system for storing and organising all necessary documents, ensuring that you are ready for audits and tax returns.
Are you prepared to streamline your accounting tasks?
Allow FORTI to handle your documentation while you focus on growing your business effectively! Count on our team to deliver bookkeeping services that align with the needs of Irish businesses.
👋 Reach out to us now for a consultation. Uncover how FORTI can assist you in bookkeeping/annual compliance, impeccable financial records, and enhancing your company’s effectiveness while ensuring adherence to Irish regulations!
Managing your finances well is an important part of running a successful solo entrepreneur business in Ireland. Though it may not be fun, keeping accurate and up-to-date financial records allows you to track your profitability. adhere to the rules governing Irish taxes and make educated choices The importance of proper bookkeeping, the best ways to do it, frequent mistakes to avoid, and ways to make it easier to understand are all covered in depth in this guide for sole proprietors. Whether you’re just starting out or are looking to improve your procedures for bookkeeping jobs, this booklet will guide you to a better understanding of bookkeeping, and you can manage your finances confidently.
Why Bookkeeping Matters for Sole Traders
Maintaining records goes beyond simply documenting transactions—it involves gaining a comprehensive understanding of your business’s financial well-being. For sole traders, in particular, this is crucial since they bear legal responsibility for all facets of their business operations, including financial matters. Here’s why adopting bookkeeping techniques is indispensable:
1. Clear Financial Understanding
By monitoring your earnings and expenditures, you will develop an understanding of the financial health of your business, facilitating smoother strategising and expansion efforts.
2. Ensuring Revenue Compliance
Sole traders, in Ireland need to keep records, for tax purposes as having maintained accounts can make tax returns easier and lower the chances of facing penalties.
3. Making decisions based on information
Keeping records enables you to strategise, determining the ideal timing for investing in new equipment or making pricing adjustments and cost reductions.
4. Keeping track of your expenses
Maintaining records enables you to deduct qualifying expenses from your income tax calculation and consequently lessen your tax obligations in the end.
Essential Bookkeeping Steps for Sole Traders
Here are the key steps to set up a simple yet effective bookkeeping system for your sole trader business:
1. Ensure you keep your business and personal finances separate, from each other
It’s important for solo entrepreneurs to maintain a distinction between their business and personal finances by setting up a business bank account to handle all financial transactions related to the business efficiently and keep an organised record of the company’s financial operations.
2. Monitor Expenditures
Remember to log all transactions from sales to business costs, noting down specifics such, as dates and descriptions along with the amounts and payment methods used in each transaction for record-keeping purposes as per Irish Revenue guidelines that allow claiming of business related expenses.
3. Employ a Basic Accounting System
Utilising accounting tools such as Xero or QuickBooks software or even a simple spreadsheet template can simplify the process of managing your records by providing functions for expense tracking and invoicing along with basic reporting capabilities to maintain organised bookkeeping practices.
4. Remember to hold onto your receipts and invoices.
Remember to keep track of all the receipts and invoices related to your business activities as a sole trader in Ireland; it’s important to hold onto these papers for up to six years to show your costs and earnings clearly when needed in the future. Use a filing system to scan and store your documents for retrieval.
5. Remember to check your bank statements every month
Monthly reconciliations are important for making sure your records align with your bank statement and catching any mistakes or missing transactions to maintain financial records.
6. Make sure to calculate your taxes
Individual business owners must submit their income tax returns every year. Keep a record of their earnings and expenses to determine their tax obligations before the deadlines approach.It’s advisable to set aside money for taxes to prevent financial burdens at the end of the year.
7. Track Cash Flow
Cash flow management is essential for business sustainability. Monitor your income versus expenses regularly to ensure you have enough funds to cover expenses and grow your business.
It’s crucial for businesses to effectively manage their cash flow to sustain operations and growth potential, keeping an eye on their earnings in comparison to expenses to ensure funds for business expansion and covering costs efficiently.
Common Bookkeeping Mistakes to Avoid
Mixing Personal and Business Finances: Never mix the expenses. Always use a separate bank account for business. This prevents confusion and ensures your records are accurate.
Neglecting to Record Small Transactions: We all have tendency to ignore keeping a track of smaller expenses. Small cash expenses add up. Always record them to get a true picture of your spending.
Not Setting Aside Money for Taxes: It’s tempting to reinvest all profits back into the business, but remember to save for taxes to avoid cash flow issues.
Ignoring Regular Reconciliation: Adopt a practice to reconcile your bank monthly. Bank reconciliations catch errors early, reducing the risk of large discrepancies over time.
Skipping Receipt Tracking: Without receipts, you may miss out on expense claims, potentially increasing your tax liability. If you miss the receipts, you wont be able to claim the vat and you pay additional taxes too.
Best Practices for Efficient Bookkeeping Processes
1. Weekly Schedule
Make sure to set aside a time each week to handle your bookkeeping tasks, as it helps in maintaining records and avoids accumulating a pile of tasks to tackle all at once.
2. Accounting Software
Managing your finances is made easier with accounting software that automates tasks and keeps track of expenses while giving you an overview of your situation. Popular software programs such as QuickBooks or Xero come equipped with features like generating invoices and organising expenses efficiently.
3. Collaborate with a bookkeeper or accountant.
If you’re uncertain about handling your bookkeeping or if you find yourself in need of assistance around tax time, it might be an idea to think about bringing onboard a bookkeeper or accountant to assist your efforts.
4. Plan for Taxes
As a sole trader, you’re responsible for filing a self-assessment income tax return. Setting aside funds for taxes throughout the year can prevent cash flow issues when taxes are due.
5. Check your statements consistently
Reviewing documents, like income statements and cash flow statements, is essential for gaining insights into your company’s well-being and enabling you to make informed business choices on a regular basis.
Bookkeeping Checklist for Sole Traders
To keep you on track, here’s a simple monthly checklist for bookkeeping:
Task
Frequency
Completed (Y/N)
Record all income and expenses
Weekly
Save receipts and invoices
Ongoing
Reconcile bank statements
Monthly
Set aside money for taxes
Monthly
Review cash flow and income statement
Monthly
Prepare for self-assessment tax return
Annually
Using this checklist can help you manage your finances efficiently, saving time and ensuring accurate, compliant records.
How FORTI Can Help
We understand that bookkeeping can be difficult, particularly for sole traders who must focus on running their business. Our dedicated bookkeeping services are tailored to help sole traders in Ireland stay organised, compliant, and stress-free.
Our Bookkeeping Services for Sole Traders Include:
Transaction Recording: We meticulously document every source of earnings and all expenditures to classify them. .
Expense Tracking and Tax Preparation: We track every eligible expense, maximising your deductions and ensuring accurate tax filings.
Monthly Reconciliations: Our team makes sure that your records are current and reconciles your accounts to align with your bank statements.
Regular Financial Reporting: We provide monthly financial reports so you always know your business’s financial health, and keep you updated with your finacial situation.
Revenue Compliance and Tax Filing Assistance: Our services help you stay compliant with Irish Revenue, simplifying tax season and ensuring peace of mind.
Are you prepared to streamline your accounting tasks?
Allow FORTI to handle your documentation while you focus on growing your business effectively! Count on our team to deliver bookkeeping services that align with the needs of Irish businesses.
👋 Reach out to us now for a consultation. Uncover how FORTI can assist you in bookkeeping impeccable financial records and enhancing your company’s effectiveness while ensuring adherence to Irish regulations!
Bookkeeping for Irish businesses involves attention to detail and regular maintenance. Depending upon the complexity of the business, we estimate around 8-15 hours per month of bookkeeping required for SMEs. Still, common mistakes keep happening, which can lead to wrong records, problems with the law, and even fines. These errors can cause some serious issues for any business, including cashflow problems, if not looked after carefully.
In this article, 10 common mistakes in Irish accounting are talked about, along with ways to avoid them and the effects they can have on your business. We will also give you a useful checklist template to make keeping your books easier.
10 Common Mistakes in Irish Accounting
1. Misclassifying Transactions
Error
When any kind of expense comes up, it needs to be recorded properly based on the type of transaction. If you put expenses in the wrong category, especially between capital and operational costs, it can mess up your financial statements and make it harder to figure out your taxes.
Solution
A clear understanding, combined with expertise, aids in categorising expenses and Keep your company’s financial records organised using a uniform chart of accounts that is reviewed and updated on a regular basis. Staff should be trained on classification to guarantee uniformity.
Consequences & Impact
Financial decisions and budget allocations may be impacted by inaccurate classification, which can lead to overpayment of taxes, underutilisation of tax deductions, and the creation of false financial statements.
2. Small Cash Transactions
Error
Another common mistake is overlooking the small transactions. A lot of Irish businesses, especially those dealing in cash, may overlook these small transactions, which leads to inaccurate cashflow and reporting issues.
Solution
Strong control over spending management is provided by platforms like as Revolut, which are very practical and user-friendly. Limiting the expenses is another option. Implementing a petty cash log should be taken into consideration in addition to this digital spending tracking. These transactions can be automatically logged and categorised with the use of accounting software.
Impact & Consequences
Over time, little amounts accumulate. Ignoring them can affect overall financial accuracy and planning by distorting financial statements and creating disparities in cash flow.
3. Data Entry Errors
Error
This problem occurs when there is a lot of manual work required. Even in this digital age, people continue to record transactions manually. Manual data entry errors, such as inaccurate dates, amounts, or invoice numbers, can cause considerable discrepancies in Irish company accounting.
Solution
In the current digital era, laborious manual work has been entirely eliminated through the use of OCR technology. This error can now be prevented with the simple snap of a photograph. Similarly, the task that typically requires hours of work can be reduced to mere seconds by emailing the invoice to the software upon its arrival. Utilise accounting software that includes built-in validation tools to mitigate manual entry errors. Implement a system of double-checking, in which a second individual evaluates entries.
Consequences & Impact
Data entry errors cause inaccuracies that affect compliance with Irish regulatory standards, produce reports that are untrustworthy, and waste time tracking and fixing mistakes. Not appropriately recording the expenses or recording them at all can lead to a considerably more serious consequence: incorrectly claiming VAT. An immediate negative effect on VAT returns of about 5,000 euros was caused by the discovery while dealing with one of the new clients that approximately 25,000 euros’ worth of invoices had not been recorded.
4. Monthly Reconciliations
Error
One of the frequent errors that we always notice is either neglecting or failing to reconcile bank and credit card statements with accounts monthly. As we mentioned above, if the work is done manually, this error is common among Irish SMEs. Wrong transactions lead to discrepancies between actual cash flow and reported amounts.
Solution
The only way to deal with this error is to schedule monthly reconciliations as a non-negotiable task. Automated reconciliation features in accounting software can streamline this process and reduce errors.
Consequences & Impact
Businesses run the danger of undetected errors or even fraud if they don’t do frequent reconciliations. This may result in poorly informed financial decision-making and poorly managed cash flow. At the end of the year, business owners typically receive a lengthy list of chores from accountants asking them to justify every transaction. If they are unable to do so, most accountants will tend to make adjustments, which results in inaccurate reporting and the possibility of not being able to make the right tax claims.
5. Ignoring Accruals and Deferrals
Error
Not recording accrued income (income that earned but is not being received yet, eg., accounts payable) or deferral (revenue received but not incurred, eg., deposit) results in misleading monthly statements, especially for companies on accrual accounting.
Solution
Make sure accruals and deferrals are entered on a regular basis by using scheduled reminders. To accurately reflect income and expenses, bookkeepers should be familiar with Irish accrual accounting standards.
Consequences & Impact
If misrepresented profits and expenses are not adequately managed, they may impact tax obligations and financial reporting, leading to problems with Irish Revenue compliance. If someone is charged, they could be fined up to €126,970 or put in jail for up to five years. A convicted individual may also be compelled to fulfil unfinished business regarding documents, returns, etc.; not doing so within 30 days is a crime in and of itself.
6. Depreciation and Amortization
Error
Companies risk misleading lenders and investors by reporting inflated asset values if they don’t factor in depreciation and amortisation.
Solution
Depreciation and amortisation should be consistently accounted for, therefore, make sure to schedule automatic calculations in your accounting software to conform with Irish accounting standards.
Consequences & Impact
Business valuations and financial statements are impacted by exaggerated asset values. Higher liabilities could also arise from erroneous tax computations.
Inflated Business Valuations: Misleads investors, creditors, and prospective buyers; undermines trust and credibility when true values are revealed.
Misleading Financial Statements: distorts the company’s financial health, causing management to make poor decisions based on inaccurate data.
Higher Tax Liabilities: Inaccurate tax calculations may result in higher liabilities; potential penalties and legal consequences if discovered by tax authorities.
Loss of Investor and Stakeholder Confidence: Erodes trust, harms reputation, affects stock prices, and reduces investor interest.
Operational and Budgeting Errors: Leads to overinvestment or underestimating cash needs, causing inefficiencies or financial strain.
8. Accounts Receivable and Payable
Error
Cash flow issues and relationships with stakeholders are negatively affected if there are any errors in managing accounts payables and receivables.
Solution
Promote monthly reconciliations and set reminders to avoid these AP and AR issues.
Consequences & Impact
Maintaining a steady flow of funds is critical to the success of any company. Impacting cash flow, late payments, and collections make it tougher to manage obligations and risk damaging relationships with suppliers, which could lead to unfavourable credit conditions.
8. Payroll Errors
Error
Payroll errors, such as inaccurate tax deductions, late payments, or noncompliance with Irish payroll regulations, can result in fines and employee dissatisfaction.
Solution
Use a payroll management system that calculates taxes and deductions automatically. Regularly review employee data and tax codes to stay up-to-date with Revenue requirements.
Consequences and Impact:
Ensuring payroll accuracy is critical for compliance and employee satisfaction. Some of the consequences are as follows:
Revenue Penalties
Loss of Employee Trust
Legal Risks
Compliance Issues:
Administrative Burden
Employee Satisfaction
9. Documentation
Error
Businesses in Ireland are required to keep records for up to 6 years. In addition to keeping records, not having receipts, invoices, or other supporting papers can make it hard to prove finances during audits or tax inspections by the Irish Revenue.
Solution
A combination of cloud-based backup and digital document management software makes all data readily available by organising and linking documents to accounting processes.
Consequences & Impact
Inadequate documentation can lead to denied deductions during tax audits, resulting in increased tax liabilities and potential penalties.
10. Tax Compliance Deadlines
Error
Take all necessary measures to safeguard your company against noncompliance. Irish businesses risk heavy fines if they fail to file their VAT, PAYE, or corporation taxes by the due dates.
Solution
Create a tax calendar with filing date reminders. Irish-compliant accounting software can help monitor deadlines and streamline tax calculations.
Consequences & Impact
Some of the consequences are as follows:
Fines and Penalties: Late tax filings result in fines and increased financial liabilities for the business.
Interest Charges: Interest on overdue taxes adds to the total tax burden.
Revenue Scrutiny: Consistent noncompliance may result in additional scrutiny from tax authorities, increasing the likelihood of detailed audits.
Audit Risks: The increased likelihood of audits may expose other compliance issues, resulting in additional penalties and corrective actions.
Reputational Damage: Non-compliance impacts the business’s reputation with stakeholders, affecting credibility and trust.
Cash Flow Impact: Penalties and interest charges can disrupt cash flow, limiting the funds available for operations or growth.
Monthly Bookkeeping Checklist Template for Irish Businesses
A Monthly Bookkeeping Checklist can help keep Irish businesses organised and compliant. Use the following template to track monthly tasks:
Task
Frequency
Assigned To
Completed (Y/N)
Notes
Record all transactions, including petty cash
Daily
[Name]
Review and classify transactions
Weekly
[Name]
Reconcile bank statements
Monthly
[Name]
Record accruals and deferrals
Monthly
[Name]
Calculate and record depreciation
Monthly
[Name]
Reconcile accounts receivable/payable
Monthly
[Name]
Review payroll for accuracy
Bi-weekly
[Name]
Update supporting documentation
Ongoing
[Name]
Review tax compliance deadlines
Quarterly
[Name]
Review financial statements
Monthly
[Name]
Conclusion
Good financial management starts with keeping accurate books. If you don’t make these common mistakes, your records will be more likely to be correct, in line with Irish Revenue rules, and legal. For many businesses, doing their own accounting can take a lot of time and lead to mistakes. This is where FORTI is useful.
At FORTI, we offer full bookkeeping services created just for Irish businesses. This way, you can be sure that your accounts are being handled by professionals. We handle all of the documentation so you can focus on what you do best: building your business. Our highly qualified employees, modern technology, and custom solutions make this possible.
Why Opt, for FORTI, for Your Bookkeeping Requirements?
In every stage of our bookkeeping services, at FORTI – accuracy and dependability are guaranteed while ensuring adherence, to regulations.
First. Evaluation of Requirements: Lets begin by grasping the needs of your company and examining your existing bookkeeping methods to provide assistance and pinpoint potential areas for enhancement.
Establishing a Chart of Accounts: We develop a chart of accounts for your business to guarantee consistent classification of all transactions. Our team is responsible for handling the input and sorting of data with the help of error checking tools to prevent mistakes in data entry and maintain precise financial records.
Monthly reconciliation of bank statements and credit card accounts: We meticulously review your accounts each month to align them with bank statements to avoid errors and maintain the accuracy of your cash flow.
Managing Accruals and Depreciation: We manage transactions, like accruals and deferrals, while also handling depreciation to ensure that our financial performance aligns, with Irish Revenue regulations.
Accounts payable and receivable: We keep an eye on your outgoing payments to make sure they are paid and collected on time to keep cash flowing smoothly.
Handling Employee Salaries and Adhering, to Regulations: Our payroll system prioritises precision and adherence to regulations by handling calculations and deductions while ensuring submission of taxes in compliance with laws.
Regular Reporting & Financial Reviews: Each month we provide you with reports that emphasise any concerns or areas of potential growth to assist you in managing your finances effectively and staying on course.
Managing tax compliance and documentation: We keep all the required supporting paperwork in order for audits and to make sure you can take advantage of all deductions.
Ongoing Support & Advisory: Our team of professionals goes beyond managing records; they also offer valuable guidance and strategic perspectives to help you make well informed decisions using reliable and current data.
Are you prepared to streamline your accounting tasks?
Allow FORTI to handle your documentation while you focus on growing your business effectively! Count on our team to deliver bookkeeping services that align with the needs of Irish businesses.
👋 Reach out to us now for a consultation. Uncover how FORTI can assist you in bookkeeping impeccable financial records and enhancing your companys effectiveness while ensuring adherence to Irish regulations!
In Ireland, handling tax responsibilities as a self-employed individual can be a challenging part of operating a business. Sole traders are in charge of appropriately reporting their income and claiming any applicable deductions, in contrast to workers whose incomes have taxes automatically taken from them. It is essential to comprehend these deductions in order to reduce tax obligations and increase profits. With useful insights for every relevant tax credit and deduction, this guide examines ten efficient tactics Irish single proprietors can employ to maximise their tax position.
There are numerous strategies available to assist sole traders in Ireland in reducing their tax liabilities, despite the fact that they are subject to a variety of tax obligations. Some of them are as follows:
1. Earned Income Tax Credit
The Earned Income Tax Credit (EITC) is a tax benefit that self employed individuals can access to lower their tax burden based on their earned income calculation for the year 2024 at €1,875 It helps create a tax contribution, between employees and self employed individuals.
Amount: €1,875 (2024)
Details: This credit reduces your tax bill based on earned income, leveling the playing field between self-employed individuals and employees.
Conditions: Must be a sole trader or self-employed and earning income from trading or professional activities.
2. Mortgage Interest Tax Credit
The Mortgage Interest Tax Credit was initially put in place in 2023 to assist self employed homeowners by allowing them to deduct a portion of the interest they pay for their house mortgages, from their income annually with a maximum relief of €1250 per year.This can be particularly beneficial, for individuals who own homes and run their businesses alone.
Amount: Up to €1,250 per year
Details: Introduced in 2023, this credit allows self-employed homeowners to deduct a portion of increased mortgage interest from their taxable income.
Conditions: Must demonstrate that the mortgage interest has increased compared to previous years, with a maximum relief of up to €1,250 per year.
3. Remote Working Credit
The Home Office Tax Credit enables self employed individuals to deduct expenses associated with working from their home office such, as electricity and heating bills in light of the growing popularity of work setups.This benefit could potentially lower the income for those running businesses, from their homes.
Amount: Varies (based on actual expenses)
Details: This credit allows deductions for expenses related to working from home, such as heating, electricity, and broadband costs.
Conditions: Must provide evidence of additional costs incurred due to remote work, such as heating and electricity expenses.
4. Pension Contributions
Contributions, to pension plans qualify for tax relief based at your tax rate of up to 40%. This incentive not promotes saving for retirement. Also lowers your taxable income now. A double advantage, for self employed individuals.
Amount: Up to 40% tax relief based on marginal rate
Details: Contributions to pension schemes are eligible for tax relief, encouraging retirement savings while reducing current taxable income.
Conditions: Contributions must be made to a qualifying pension scheme; tax relief is available at the individual’s marginal tax rate, which can be up to 40%.
5. Medical Expenses Relief
Self employed individuals who work independently are eligible to receive a tax deduction of 20%, for costs that are not reimbursed by insurance plans such as doctor consultations and hospital care services. In situations where the expensesre higher and relate to nursing home services or similar needs relief can be claimed at rates of up to 40%. This deduction proves beneficial, for self employed individuals managing their businesses.
Amount: 20% relief on eligible medical expenses
Details: Sole traders can claim tax relief on medical expenses not covered by insurance, including doctor visits and hospital treatments.
Conditions: Must have incurred medical expenses not covered by insurance. Relief is granted at a rate of 20% on eligible expenses.
6. Tuition Fees Deductions
Self employed people have the option to deduct tuition fees they paid for their education or, for their dependents who are enrolled in university courses, which can help them save money on their tax filing.
Amount: Varies (based on actual fees)
Details: Self-employed individuals can claim deductions for tuition fees paid for third-level education courses for themselves or their dependents.
Conditions: Must provide proof of payment for qualifying third-level education courses; relief is available at the standard rate of 20%.
7. Home Carers Tax Credit
If you’re married and one partner stays home to look after the kids you may be eligible, for the Home Carers Tax Credit which can provide support of up to € 1800, per year to families where one parent is focused primarily on caregiving duties.
Amount: €1,800 annually
Details: If you are married and one spouse stays home to care for children, you may qualify for this credit.
Conditions: The stay-at-home spouse must provide care for dependent children; the credit is worth up to €1,800 annually.
Limit: The stay-at-home spouse’s income must not exceed €7,200; the credit amount is up to €1,800 annually.
8. Dependent Relative Tax Credit
Individuals providing financial support to dependent relatives, are eligible for this credit.
Amount: €245 per individual supported
Details: This credit helps those who care for dependent relatives, providing reduced tax liabilities to assist with caregiving expenses.
Conditions: The dependent relative must be directly related and unable to support themselves due to incapacity or old age. Their income must not exceed €17,404 (2024 threshold).
Limit: The dependent relative’s income must not exceed €17,404 (effective from January 1, 2024) to qualify for the credit of €245 per dependent relative.
9. Rent Tax Credit
Tenants paying rent can claim this credit.
Amount: €750 for single renters; €1,500 for married couples
Details: Tenants can claim this credit against rental payments, which can significantly impact annual tax returns.
Conditions: Must provide proof of rental payments; the credit is €750 for single renters and €1,500 for married couples.
10. Tax Break for Landlords (2024 Onwards)
Property owners earning rental income can claim this credit.
Details: Announced in Budget 2024, this new tax break allows property owners to claim deductions on income earned from rented properties.
Conditions: Specific details on eligibility will be outlined in the upcoming budget provisions, but generally must comply with rental income regulations.
Limit: Specific eligibility details pending in upcoming budget provisions, but generally must comply with rental income regulations.
Summary Table of Tax Credits
Tax Credit
Amount/Benefit
Description
Earned Income Tax Credit
€1,875 (2024)
Reduces tax bill based on earned income.
Mortgage Interest Tax Credit
Up to €1,250 per year
Deducts increased mortgage interest from taxable income.
Remote Working Credit
Varies
Deductions for home office-related expenses.
Medical Expenses Relief
20% relief
Claims on medical expenses not covered by insurance.
Pension Contributions
Up to 40% tax relief
Contributions eligible for tax relief based on marginal rate.
Tuition Fees Deductions
Varies
Deductions for tuition fees paid for education courses.
Home Carers Tax Credit
€1,800 annually
For married couples where one spouse cares for children.
Dependent Relative Tax Credit
€245 per individual
Supports those caring for dependent relatives.
Rent Tax Credit
€750 (single); €1,500 (couple)
Claims against rental payments.
Tax Break for Landlords
TBD
Deductions on rental income starting in 2024.
Using these credits wisely can enhance the health of business owners in Ireland and optimize their tax situations.It’s an idea to seek guidance from a certified accountant or tax consultant to ensure adherence, to regulations and maximise advantages tailored to business operations.
Conclusion
As a self-employed individual, lowering your tax burden is a tactic to increase profitability and long-term business success, not only to save costs. You can improve your financial situation and reinvest in the business to ensure its survival by taking advantage of all available tax advantages and deductions. It is strongly advised to speak with a tax professional in order to customise these tactics to your unique circumstances and guarantee adherence to Irish tax laws. Plan now to get the most out of your tax advantages.
Don’t delay if you’re an Irish sole trader trying to minimise your tax obligations and improve your financial situation! To customise these tactics to your company’s requirements, speak with a certified accountant or tax expert right now. You can guarantee compliance, lower your tax burden, and put the money you save back into expanding your company by being proactive and making good use of these tax benefits. To begin optimising your tax position for a prosperous financial future, get in touch with us right now for a free consultation!
Are you doing or thinking to start an e-commerce business in Ireland? Do you know an E-commerce businesses in Ireland can take advantage of several tax credits to reduce their tax liabilities. Lets talk about some of them here:
1. Research and Development (R&D) Tax Credit
Businesses have the opportunity to receive a tax credit of 25 percent, for research and development expenditures they incur. This allows companies to deduct 12.5% of their R&D expenses from their income, resulting in a 37.5% reduction in the corporate tax rate for qualified R&D initiatives. A potential enhancement to this benefit includes a thirty percent credit raise specifically aimed at microenterprises.
Reference: The 25% R&D tax credit can be claimed as a cash refund if there is insufficient tax due. If a corporation spends €500,000 on qualified R&D, it can claim €125,000.
Example: A tech startup creating a new software platform may spend a lot on R&D. A €100,000 tax credit can be claimed for €400,000 of eligible spending.
2. Knowledge Development Box (KDB)
The KDB provides a 10 percent tax rate, for profits generated from intellectual property (IP and patents when certain research and development (R&D activities are conducted within Ireland.This initiative encourages innovation. Can be particularly advantageous, for technology driven e commerce businesses.
Reference: The KDB allows for a 10% corporate tax rate on profits from qualified intellectual property. This incentivises companies to develop and exploit IP in Ireland.
Example: A gaming company that develops a new game and patents its technology can benefit from the KDB, paying only 10% on profits generated from that game.
3. Digital Games Tax Credit
This tax credit offers a reimbursement for costs accrued by digital gaming firms during the creation and testing of games that showcase Irish culture and heritage. This benefit can be requested for initiatives launched post November 22nd of the year 2022.
Reference: This credit provides relief for qualifying expenses associated with the design and production of video games that promote Irish culture.
Example: An independent game developer creating an educational game about Irish history could receive financial support through this credit.
4. Start-Up Relief for New Companies
New start-ups that start trading between 2009 and 2026 may be eligible for a three-year corporation tax holiday if the total amount of corporation tax payable does not exceed €40,000 per year. This tax relief initiative aims to provide support to emerging enterprises as they establish their presence in the market.
Reference: New businesses that have annual total corporation tax under €40,000 are eligible for a three-year corporation tax holiday.
Example: If an e-commerce business established in 2023 satisfies the criteria, it may be able to avoid paying any corporation tax for the first three years.
5. Accelerated Capital Allowances
Businesses that invest in energy-efficient equipment can take advantage of accelerated capital allowances, which enable them to deduct the cost of eligible assets from their taxable income at a faster pace than traditional depreciation schedules.
Reference: Compared to traditional depreciation schedules, this allows businesses to deduct the cost of energy-efficient equipment from their taxable income more quickly.
Example: Rather than spreading the cost over several years, an e-commerce company that invests in energy-efficient servers could claim the entire cost of those servers in the first year.
6. Foreign Tax Credits
You might qualify for foreign tax credits, which let you deduct taxes paid abroad from your Irish tax obligations, if your e-commerce company generates revenue from overseas sources. This can help mitigate double taxation on international earnings.
Reference: In order to prevent double taxation, businesses that receive revenue from overseas sources may deduct taxes paid abroad from their Irish tax obligations.
Example: An Irish e-commerce company may be able to lower its Irish tax liability by £10,000 if it sells goods in the UK and pays £10,000 in UK taxes.
7. Employer PRSI Relief
Relief from Pay Related Social Insurance (PRSI) contributions for specific employees can help employers lower payroll expenses overall and boost cash flow for e-commerce companies.
Reference: Payroll costs can be decreased for employers by receiving relief on Pay Related Social Insurance (PRSI) contributions for specific employees.
Example: By utilising this relief, an e-commerce company that hires new employees may lower its overall payroll costs.
E-commerce companies in Ireland can drastically lower their tax obligations and promote innovation and expansion in their operations by skilfully utilising these tax credits. To guarantee compliance and optimise benefits catered to particular business operations, speaking with a tax advisor is advised.
Take Action Today!
Are you ready to get the most out of your e-commerce business and pay less in taxes? There’s money waiting for you! Start looking into the tax breaks and credits you can get right now.
You should talk to a tax expert to find the best tactics for your business. Using these chances can help your business save a lot of money and grow, no matter if it’s a new one or an old one.
Get help figuring out how to use tax credits in Ireland by getting in touch with us at FORTI.ie. Let’s make sure your business does well together!
Starting a business is an exciting journey, and one of the first steps in this process is registering your company. Taking the initial steps involves officially setting up your company in Ireland is quite straightforward yet demands thoughtful attention to numerous details. The following detailed guide will lead you through the elements of registering your company in Ireland – from choosing the appropriate company structure to grasping your compliance responsibilities.
Understanding Company Structures in Ireland
Types of Companies
In Ireland, business owners have access to a wide variety of company structures to choose from. The most common include:
Private Company Limited by Shares (LTD): The most common form, in which shareholders’ liability is capped at the outstanding balance on their shares. It can have a single director and a single member.
Designated Activity Company (DAC): Similar to an LTD, but with specific activities specified in the constitution. It requires at least two directors.
Public Limited Company (PLC): A company that can issue shares to the public and must have a minimum share capital of €25,000. It requires at least three directors.
Company Limited by Guarantee (CLG): Commonly used for non-profit organisations, members’ liability is limited to the amount they promise to contribute.
Unlimited Company (ULC): A less common structure in which members bear unlimited liability. This type of company is often used for specific purposes, such as family businesses.
Pros and Cons of Each Structure
Choosing the right company structure is crucial as it impacts your liability, taxation, and compliance requirements. Here are some pros and cons:
Pros: Flexibility in activities, limited liability.
Cons: More compliance requirements than LTD.
PLC
Pros: Ability to raise capital from the public, credibility.
Cons: Higher regulatory scrutiny and costs.
CLG
Pros: Limited liability, suitable for non-profits.
Cons: Restrictions on profit distribution.
ULC
Pros: Fewer regulatory requirements.
Cons: Unlimited liability for members.
Selecting a Company Name
Importance of a Unique Name
Choosing a distinctive and memorable company name is critical for both branding and legal compliance. Your business’s identity and values should be reflected in the name of your company.
Guidelines for Acceptable Names
When selecting a name, ensure it adheres to the following guidelines:
The name must not be identical or similar to an existing company name.
It should not include restricted words (e.g., “bank,” “insurance”) without prior approval.
The name should not be misleading or offensive.
Tips for Brainstorming
Use descriptive words related to your business.
Consider using a name that conveys your mission or values.
Check domain name availability if you plan to have an online presence.
Registered Office Address Requirements
What Qualifies an Acceptable Address
Every business operating in Ireland is required to maintain a registered office address that serves as the designated contact point for communication with the Companies Registration Office (CRO). This address must be a physical location within Ireland and cannot be a post office box.
Options for Virtual Office Addresses
If you do not have a physical office, consider using a virtual office service. These kinds of services can offer you a designated address for your business operations and handle any incoming mail on your behalf to ensure that you are meeting all legal compliance standards and regulations effectively keeping you in line, with all necessary legal frameworks and guidelines.
Appointing Directors and Company Secretary
Legal Requirements
A minimum of one director must be appointed during the registration of a company. If your company is a DAC or PLC, you will need a minimum of two or three directors, respectively.
Roles and Responsibilities
Directors: Responsible for managing the company and making strategic decisions. They must act in the best interest of the company and its shareholders.
Company Secretary: Responsible for maintaining statutory records, filing returns, and ensuring compliance with legal obligations.
Process for Appointing Directors
Directors can be chosen during the registration process or later on by a resolution of the board. Ascertain that every director is informed of their duties and statutory requirements.
Share Capital Structure
Understanding Share Capital
A company’s funds raised through the issuance of shares are referred to as share capital. It is divided into two main categories:
Authorised Share Capital: The maximum amount of share capital that a company is authorised to issue.
Issued Share Capital: The actual amount of share capital that has been issued to shareholders.
Considerations for Share Capital Structure
When determining your share capital structure, consider the following:
The amount of capital you need to raise.
The number of shares to be issued to founders, investors, and employees.
The implications of share ownership on control and decision-making.
Post-Incorporation Compliance
Ongoing Compliance Obligations
After registering your company, you must follow several compliance obligations, including:
Filing Annual Returns: Companies must file an annual return with the CRO that includes financial statements and company information.
Maintaining Statutory Records: Keep accurate records of meetings, resolutions, and financial transactions.
Tax Compliance: Ensure timely registration for taxes such as Corporation Tax, VAT, and PAYE.
Importance of Proper Record Keeping
Maintaining accurate records is critical for compliance and can help protect your company during an audit. Implement a robust record-keeping system to track all business activities.
Tax Registration for New Companies
Mandatory Tax Registrations
New companies in Ireland must register for various taxes, including:
Corporation Tax: All companies must register within 30 days of commencing trading.
Value-Added Tax (VAT): Required if your turnover exceeds the VAT registration thresholds (€40,000 for services and €80,000 for goods).
Pay As You Earn (PAYE): If you have employees, you must register for PAYE to deduct income tax and social insurance contributions.
Consequences of Failing to Register
Choosing the Right Company Formation Provider
Benefits of Professional Assistance
When you work with a company formation service provider, it can make registering your business easier and help you meet all the necessary legal standards. They offer guidance on setting up your company structure, handling tax registration, and ongoing compliance.
What to Look for in a Formation Service Provider
When selecting a formation service provider, consider:
Reputation and reviews from other clients.
Range of services offered, including ongoing compliance support.
Pricing and transparency of fees.
DIY vs. Professional Registration
While it is possible to register a company on your own, using a professional service can save time and reduce the likelihood of errors. Consider the pros and cons based on your knowledge and resources.
Conclusion
Setting up a business in Ireland is a milestone when embarking on your entrepreneurial path.You can lay a foundation for your business by gaining insight into the key factors of company registration, such, as choosing the appropriate framework, adhering to legal requirements, and keeping accurate documentation.
If you need assistance with the company registration process or ongoing compliance, contact FORTI. Our experienced team is ready to assist you at each stage, making sure your business fulfils all criteria and runs seamlessly within the Irish tax framework. Allow us to handle the specifics while you concentrate on expanding your business.
Structural Changes
If your company structure changes, we handle all required CRO filings and statutory updates. Includes:
Director appointments or resignations
Share transfers or allotments
Company name changes
We ensure your company records remain accurate and legally compliant.
Strike
If you decide to close your company, we manage the full voluntary strike-off process, including compliance review, documentation, and filing with the Companies Registration Office (CRO), ensuring the company is properly and safely dissolved.
Additional CRO Filings
Director changes, share transfers, share allotments, company name changes or other statutory updates.
RBO Filing / Ownership Updates
Required whenever shareholders or beneficial ownership changes (25%+). We prepare and submit the update to the Central Register to keep your company compliant
Registered Office Address
Secure and reliable registered office solution to improve your business reputation. This add-on service provides an official business address for company registration and ensures important business correspondence is handled professionally. Includes:
Official registered business address
Use for company registration
Handling of business correspondence
Professional business presence
Reliable address for official records
Full Company Secretary Service
Our full company secretary service ensures your company adheres to corporate governance standards. This includes maintaining statutory registers, filing annual returns, handling board resolutions, and advising on legal compliance. By outsourcing this service, you can reduce administrative workload and ensure your company avoids compliance-related risks.
Register of Beneficial Owners (RBO) Filing / Update
Every Irish company must file and maintain accurate beneficial ownership details with the Central Register of Beneficial Owners (RBO). Our service includes:
Preparation and electronic filing with the Central RBO
Review of 25%+ ownership or control thresholds
Confirmation of submission for your records
Required within 5 months of incorporation and whenever shareholding changes. Failure to file can result in significant penalties — we ensure your company remains fully compliant.
Strike Off
If you need to close your company — whether within the first year or later — we manage the entire voluntary strike-off process professionally and compliantly. Our team handles:
Director resolutions and required documentation
Pre-strike-off compliance review
Preparation and filing with the Companies Registration Office (CRO)
We ensure your company is properly wound down to avoid delays, penalties, or future compliance issues.
Please note: CRO filing fee and required newspaper advertisement costs are separate.
Digital Marketing Services (Free Consultation)
Reaching your audience effectively is key to growth. This free consultation introduces startups and small businesses to digital marketing strategies, including social media management, search engine optimisation (SEO), and online advertising, tailored to your industry and goals.
Introduction to Website Development Company (Free)
Building a strong online presence is vital for any business. This free service connects you with experienced website development companies, offering startups and small businesses tailored consultations to help establish or upgrade their online platforms.
Modern businesses thrive on effective communication. This service provides VoIP phone solutions and professional call answering with calendar management and call forwarding. It ensures no business opportunities are missed while projecting a professional image to clients and partners.
6-Month Annual Return Filing
Filing the first Annual Return (B1) is an important requirement to keep your company compliant and in good standing. This service includes the preparation, filing, and management of all required documents for the year, such as financial statements, shareholder reports, and any necessary changes to the company structure. It allows you to focus on growing your business while ensuring your obligations are met. Includes:
Preparation and electronic filing
Deadline monitoring
Audit exemption protection
This filing is required even if no financial statements are due.
Annual Return Filing per Year
Annual returns are essential for keeping your company information up-to-date with the Companies Registration Office (CRO). This service ensures that all required information, such as directors, shareholders, and company financials, is filed accurately and on time, avoiding late penalties and maintaining good standing.
Annual Compliance Support
Annual compliance is critical for avoiding fines and maintaining good standing with regulatory authorities. This service includes the preparation, filing, and management of all required documents for the year, such as financial statements, shareholder reports, and any necessary changes to the company structure. It allows you to focus on growing your business while ensuring your obligations are met. Includes:
Annual Return (B1) filing
Statutory register maintenance
Deadline tracking
Audit exemption monitoring
Compliance advisory support
Ideal for directors who want ongoing professional oversight.
Annual Return (B1) Filing
Preparation and filing of yearly CRO Annual Return (after year one).
Helps maintain good standing and avoid late filing penalties.
Full Company Secretary Service
Our full company secretary service ensures your company adheres to corporate governance standards. This includes maintaining statutory registers, filing annual returns, handling board resolutions, and advising on legal compliance. By outsourcing this service, you can reduce administrative workload and ensure your company avoids compliance-related risks.
Historical filing and bookkeeping services are for businesses that have gaps in their financial year filings. We will require this information for compliance and reporting purposes, regardless of the gap duration.
Manage Annual Returns Deadline (Included)
File Annual Return in CORE (Included)
File PDF Financial Statements in CORE File Manager (Included)
Signing Annual Return and Bank Application Documents (Included (Limited)**)
Company Secretarial Paperwork Filing (Included)
Maintaining and Updating Company Registers (Included)
Drafting Minutes for Board Meetings (AGM Included) (Included)
Ongoing Company Secretarial Advice (Annual Limit) (Up to 300 minutes)
Countersignatures for Company Bank Applications/Reports (Not Included)
Traditional phone systems are transformed by VoIP (vocal over Internet Protocol) technology, which facilitates vocal communication over the internet. This technology is extensively employed in cloud-based phone services. The latest technology provides businesses with substantial advantages, such as seamless integration with a variety of digital tools and increased flexibility. Our call answering services ensure that you never miss an important call. We ensure that your business’s communication is both efficient and effective by managing your diary, receiving inquiries, and forwarding them to you.
Our Business Address Service will improve your company’s corporate image by providing a prestigious address for your correspondence. We will forward your business correspondence to an alternative address of your choosing via post for a nominal fee of €55 per month. This service is renewable annually, with an additional fee for forwarding general business correspondence.
If you need cloud based phone services, enquire now.
Company Formation
Includes CRO Filing Fee for Private Limited Company or DAC.
Manage Annual Returns Deadline (Included)
File Annual Return in CORE (Included)
File PDF Financial Statements in CORE File Manager (Included)
Signing Annual Return and Bank Application Documents (Included (Limited)**)
Company Secretarial Paperwork Filing (Included)
Maintaining and Updating Company Registers (Included)
Drafting Minutes for Board Meetings (AGM Included) (Included)
Ongoing Company Secretarial Advice (Annual Limit) (Up to 300 minutes)