Pradeep Dabas, ACCA, MIoD, MBA
Pradeep Dabas is a Chartered Certified Accountant (ACCA), Member of the Institute of Directors (MIoD), and founder of Forti, a Dublin-based accountancy and advisory firm helping Irish entrepreneurs and SMEs with company formation, bookkeeping, and compliance. He is also the founder of Salt Marketing, a Dublin-based digital marketing agency. Holding an MBA in Marketing and an ACCA qualification — both achieved in Dublin — and with over 20 years of experience in finance and business, Pradeep brings a rare combination of financial rigour and commercial thinking to every client relationship. He is also the creator of The Mentor Academy, an online education platform specialising in finance courses designed to help entrepreneurs and professionals take control of their financial future. Forti is based in Sandyford, Dublin and works with businesses across Ireland.
View all posts by Pradeep Dabas →
Ecommerce sellers carry more moving parts than most business owners when they stop trading — an OSS registration, possibly a foreign VAT registration tied to stored stock, and a marketplace account that keeps running whether you’re paying attention to it or not. Here’s what needs to be closed down deliberately, and what happens if it isn’t.
Why Ecommerce Sellers Are a Special Case
Most of the compliance failures we’ve covered in this series apply to any Irish business. Ecommerce sellers carry extra exposure on top: a Union OSS registration reporting sales across every EU state you sell into, potentially a local VAT registration in any country where you’ve stored stock, and — if you sell through Amazon, eBay or Etsy — a marketplace account that continues taking orders, holding your inventory, and generating transactions long after you’ve mentally ‘stopped.’ None of these switch off on their own, and each has its own separate deregistration process.
Deregistering From OSS: The Steps That Actually Matter
1. Notify Revenue electronically, through the VAT OSS section in ROS, that you wish to deregister. This must be done at least 15 days before the end of the calendar quarter prior to the quarter in which you intend to stop using the scheme.
2. File your final OSS return covering the last quarter of use, and pay any VAT still due — deregistering doesn’t cancel liability for supplies already made under the scheme.
3. Keep OSS records for the full 10-year retention period required under EU rules, even after deregistration — Revenue and other member states can still request them.
4. If you’re stopping trading altogether rather than switching schemes, also cancel your underlying Irish VAT registration via TRCN1 once all final returns are filed.
Miss the 15-day notice window and simply stop filing instead, and you risk a different outcome entirely: exclusion from the scheme by Revenue for non-compliance, which triggers a quarantine period during which you cannot re-register for OSS even if you resume trading. A deliberate, on-time deregistration and an enforced exclusion are not the same thing on your compliance record.
The Stock Problem: What Happens to Inventory You Still Hold
If you’re deregistering with stock still on hand, Revenue treats the retention of that stock — for personal use, write-off, or simply because it wasn’t sold — as a deemed supply, meaning VAT still needs to be accounted for on it in your final return. This is one of the most commonly missed steps in a rushed closure: sellers cancel the registration and quietly dispose of remaining stock without accounting for the VAT position on it first.
The bigger risk sits with sellers using Amazon FBA or another pan-EU fulfilment model. OSS never covered the stock itself — only the sale to the end consumer. If stock is still sitting in a warehouse in Germany or Poland when you deregister from OSS and cancel your Irish VAT number, the local VAT registration in that country doesn’t disappear with it. It has to be separately closed, and any stock still physically there needs to be cleared, transferred, or accounted for under that country’s own rules first.
Marketplace Accounts Don’t Close Themselves Either
Closing an Amazon, eBay or Etsy seller account is a commercial step, not a tax one — but leaving it active after you’ve stopped trading creates exactly the kind of loose end that causes problems later. Outstanding orders, returns, and marketplace-collected VAT under the deemed supplier rules can continue generating activity on an account you’ve mentally already closed, and reconciling that activity months later, against tax registrations that have already been cancelled, is far harder than closing everything in the right order at the time.
A Sensible Closing Order
Stop taking new orders across every channel and let existing orders and returns run to completion.
Clear or transfer any stock held in foreign warehouses, and close the associated local VAT registration in that country.
Account for VAT on any stock you retain rather than sell, in your final return.
Submit your OSS deregistration at least 15 days before the end of the prior quarter, and file the final OSS return.
Cancel your underlying Irish VAT registration via TRCN1 once all final returns are filed and settled.
Close the marketplace seller accounts themselves once orders, returns and payouts have fully settled.
If the business traded through a limited company, follow the CRO closure steps covered in Part 2 of this series — dormancy, voluntary strike-off, or restoration, depending on where things stand.
Case Studies
Case Study 1 — A Clean OSS Deregistration
A Shopify-based homeware seller decided to close the business at the end of a calendar quarter. The deregistration notice was submitted to Revenue in good time, the final OSS return was filed and paid, and the underlying Irish VAT registration was cancelled once no further stock remained. No penalties, no quarantine period, and no loose ends.
Case Study 2 — Stranded Stock in a German Warehouse
An Amazon FBA seller cancelled their Irish VAT registration and OSS scheme without first arranging for stock still held in Amazon’s German fulfilment centre to be cleared. The German VAT registration tied to that stock remained technically open, and Amazon continued to report inventory movements against it. The position was only resolved once the stock was removed and the foreign registration formally closed — a step that should have preceded, not followed, the Irish deregistration.
Case Study 3 — Missing the Notice Window
A multi-channel seller simply stopped filing OSS returns after winding the business down informally, without submitting a deregistration notice. Revenue excluded the registration for non-compliance rather than processing a clean deregistration, which placed the business in a quarantine period before it could register for OSS again — relevant a year later when the same founder started a new ecommerce venture and found the scheme temporarily unavailable to them.
(These case studies are illustrative composites reflecting patterns we see regularly among Irish ecommerce clients, not individual businesses.)
When an asset sale or a share sale involves specific Irish assets—such as land, buildings, business goodwill, or unquoted shares deriving their value from Irish land—specific financial thresholds apply:
The Triggers: A clearance certificate is required if the transaction value exceeds:
€500,000 for commercial property, land, business goodwill, or qualifying unquoted shares.
€1,000,000 for residential property.
The Withholding Penalty: If the seller fails to produce a valid clearance certificate to the buyer prior to or at closing, the purchaser is legally required to withhold exactly 15% of the gross purchase price and pay it directly to Revenue within 30 days.
Processing Timelines: Applications must be submitted electronically. Standard processing times typically range from 3 to 4 weeks, meaning applications should be initiated as soon as contracts are signed.
2. Company Registration History & Audit Exemption Rules
Filing histories are scrutinized heavily during corporate transactions due to the severe downstream impacts of a missed deadline:
Automatic Loss of Exemption: If a company files its annual return late by even a single day, it automatically loses its right to claim an audit exemption for that financial year and the subsequent financial year.
The Transaction Impact: If a company has traded through those years without an audit under the assumption it was exempt, it will be forced to commission a retrospective audit before a share sale can cleanly close. This causes severe transaction delays and often triggers price reductions from buyers.
3. Register of Beneficial Ownership (RBO) Compliance
The 14-Day Rule: Any internal corporate restructuring, share transfer, or new allotment must be updated on the central Register of Beneficial Ownership within 14 days of the change.
Due Diligence Friction: Discrepancies between the company’s internal share register and the public RBO register automatically flag during standard anti-money laundering checks, halting funds from being drawn down until corrected.
4. One Stop Shop (OSS) Timelines & Penalties
The Cut-off Logic: To stop using the Union OSS scheme, a business must notify Revenue by the 15th day of the final month of a calendar quarter (e.g., to exit from 1 October, notice must be submitted on or before 15 September). Missing this deadline locks the business into the scheme for the next full 3-month cycle.
The Quarantine Mechanic: A forced exclusion from the scheme due to persistent non-compliance (such as failing to file or pay for 3 consecutive quarters) results in an automatic 2-year suspension. During this time, the business cannot register for OSS in any EU Member State and must instead seek multiple local retail VAT registrations.
Data Retention Mandate: All records supporting OSS returns must be maintained digitally and made available upon request for exactly 10 years from the end of the year of the transaction.
5. Domestic VAT Cessation & Stock Asset Disposal
Deemed Supply Rule: Goods forming part of the assets of a business that ceases to trade are treated as sold by the business to itself.
Valuation: The VAT on unsold closing stock must be calculated based on the cost price (or purchase price) of the goods at the time of cessation, not the retail price.
Cancellation Mechanism: The domestic VAT cancellation is processed through an electronic registration facility once all final returns and liabilities hit zero.
6. Cross-Border Fulfillment & Marketplace Rules
Storage vs. Sale: Holding stock in a fulfillment center outside of Ireland immediately triggers a local VAT registration requirement in that host country. Canceling the Irish OSS scheme does not automatically close foreign VAT accounts.
Marketplace Rules: Digital platforms are responsible for collecting tax on certain transactions. However, if a merchant account is left active with automated returns or customer credits processing post-closure, the platform will continue to generate data entries that conflict with cancelled tax registrations.
Pre-Sale & Pre-Closure Sequence Checklist
Step
Compliance Channel
Metric / Deadline
1. Stock Liquidation
Marketplace / Warehouse
Clear, destroy, or legally transfer all foreign inventory out of non-Irish fulfillment hubs.
2. Foreign VAT Closure
International Tax Authorities
File final local returns and submit formal deregistration forms to every individual country where stock was stored.
3. Tax Clearance Certificate
Electronic Revenue System
Check status across all tax heads (VAT, Corporation Tax, PAYE/PRSI) 6–8 weeks before negotiations.
4. Deemed Supply Calculation
Domestic VAT Return
Value remaining Irish stock at cost price; include this figure on the final VAT return.
5. OSS Exit Notice
Electronic OSS Portal
Submit deregistration request 15 days or more before the quarter’s end.
6. Capital Gains Clearance
Electronic Revenue System
File clearance application if the transaction hits the €500k/€1m thresholds immediately upon exchange of contracts.
7. Domestic Cancellation
Electronic Revenue System
Submit formal cancellation for the underlying domestic VAT number once all liabilities are clear.
8. RBO Alignment
Central Register
Cross-reference the central RBO register against the current internal register of members at least 3 weeks prior to closing.
Frequently Asked Questions
1.Can I just stop filing OSS returns once I’ve stopped trading?
Ans: You can, but it’s the wrong way to close it. Simply stopping without notifying Revenue can result in exclusion from the scheme rather than a clean deregistration, which carries a quarantine period before you can register again.
2. Do I need to deregister OSS and Irish VAT at the same time?
Ans: Not necessarily at the same moment, but in the right order — OSS deregistration first (with its 15-day notice requirement), followed by cancellation of the underlying Irish VAT registration once all final returns are filed and settled.
3. What happens to VAT on stock I don’t sell before closing?
Ans: It’s treated as a deemed supply and needs to be accounted for in your final VAT return, whether you retain it, write it off, or dispose of it another way.
4. Does closing my Amazon or eBay seller account cancel my VAT obligations?
Ans: No. The marketplace account and your tax registrations are entirely separate. Closing one has no effect on the other, and outstanding marketplace activity can continue to affect a tax position you thought was already closed.
5. If stock is stored in another EU country, do I need to do anything before deregistering?
Ans: Yes. Clear or transfer the stock and close the local VAT registration in that country first — OSS and your Irish VAT registration never covered that separate obligation.
How Forti Helps
We handle the full sequence — OSS and VAT deregistration, foreign VAT closures tied to stored stock, and the underlying CRO position — so an ecommerce business closes cleanly across every channel, rather than leaving a registration open somewhere that resurfaces later.
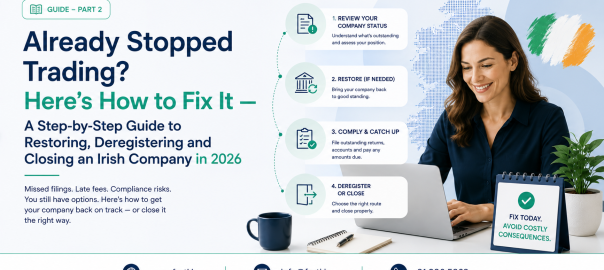
In Part 1, we looked at why ‘stopped trading’ isn’t the same as ‘closed down,’ and what it costs when business owners leave that gap unresolved. This follow-up is the practical playbook: the exact steps to restore a struck-off company, deregister properly with Revenue, close a company the right way, or keep a dormant one compliant — with the current CRO fees and timelines for each route.
Step One: Work Out Which Situation You’re Actually In
Before picking a fix, confirm the starting point. The route — and the cost — depends entirely on which of these applies to you right now.
Your company is still on the CRO register, but annual returns are overdue — you’re at risk, but not yet struck off.
Your company has already been struck off and dissolved — you need restoration if you want it back.
Your company is trading-inactive but compliant so far — you want to formally mark it dormant or close it properly before anything lapses.
You stopped self-employment as a sole trader — your fix runs through Revenue and, if you registered a business name, the CRO’s RBN3 form.
Search the CRO’s public register (cro.ie) for your company name or number — it will show your last filed annual return and current status, which tells you immediately which path below applies.
Path A: Restoring a Struck-Off Company
If it’s been less than 12 months since dissolution — Administrative Restoration
1. File Form H1 through the CRO’s CORE portal. The filing fee is €300, payable by bank draft, CRO deposit account, or online payment — cheques are no longer accepted.
2. File every outstanding annual return, each with its financial statements. Late filing penalties apply per return (€100 plus €3/day, capped at €1,200), though on a restoration the cumulative late-filing exposure across the last three returns is capped at €3,600.
3. If the company was struck off for Revenue non-compliance rather than CRO non-filing, you’ll also need written confirmation from Revenue that all outstanding statements have been delivered before the CRO will process restoration.
4. Confirm the company still meets the Section 137 requirement for an EEA-resident director (or holds the relevant bond), and that director/secretary details are up to date.
5. Once the Registrar is satisfied, the company is restored and treated, for continuity purposes, as if it had never been dissolved — though the gap in filings and the strike-off itself remain on the public record permanently.
If it’s been more than 12 months — Court Order Restoration
After the 12-month administrative window closes, restoration can only happen through the High Court, under Section 738 of the Companies Act 2014, provided fewer than 20 years have passed since dissolution.
This route requires a solicitor, a letter of no objection from the CRO’s Enforcement Section, confirmation from Revenue that all liabilities are discharged, and a court hearing before the order is filed with the CRO (a further €15 fee). It is slower, adds legal costs on top of the same outstanding CRO penalties and Revenue confirmations, and can take several months from start to finish — which is exactly why administrative restoration, actioned promptly, is the route worth protecting.
Path B: Closing a Company Properly (Voluntary Strike-Off)
If the company is solvent, has no outstanding creditors, and you genuinely want to close it rather than restore or reactivate it, voluntary strike-off is the cheapest and cleanest route — a fraction of the cost of letting the CRO strike it off involuntarily and dealing with the fallout later.
1. Confirm the company meets the Section 733 conditions: it has ceased trading (or never traded), has no assets or liabilities, and is not the subject of any court proceedings.
2. Ensure all Revenue tax registrations are cancelled and any final returns filed — the CRO’s H15 process assumes no outstanding Revenue position.
3. File Form H15 through CORE. The filing fee is €15.
4. Place a newspaper advertisement (published within 30 days of your CRO submission) announcing the intention to strike off, and submit the full page of that newspaper alongside the H15.
5. The CRO publishes a notice in the CRO Gazette. Any party has 90 days to object using Form H16; if no valid objection is received, the company is struck off and dissolved in an orderly, planned way — not an enforcement action against you.
Path C: Deregistering Correctly With Revenue
Whether you’re closing a company, pausing it as dormant with no further tax activity, or winding up a sole trade, Revenue registrations don’t cancel themselves — you have to tell them.
1. Submit a Tax Registration Cancellation Notification (Form TRCN1), or cancel online through ROS/myAccount where the facility is available, for each registration that no longer applies: VAT, employer PAYE, Corporation Tax, or Income Tax.
2. File all outstanding returns up to the date of cessation first. Cancelling the registration stops future obligations — it does not remove liability for periods before the cessation date.
3. Account for VAT on any assets or stock retained at the point of deregistration; Revenue treats this as a deemed supply in your final VAT return.
4. If you employed staff, complete final payroll submissions and issue final pay and tax details before cancelling your employer PAYE registration.
5. Keep the cancellation confirmation Revenue issues — you’ll need it if you later apply to have a company restored to the CRO register, since the CRO requires written confirmation that all Revenue statements were delivered.
Path D: Keeping a Dormant Company Properly Compliant
If the plan is to keep the company on the register — perhaps to protect a name, hold an asset, or pause before restarting
dormancy is a valid, low-cost status, but it still comes with a fixed annual routine.
Hold a directors’ meeting before the financial year end to formally record the decision that the company is dormant and will claim the dormant company audit exemption, minuted in accordance with Section 365.
File the CRO annual return (Form B1) every year, on time, with a balance sheet carrying the required dormant company exemption statement.
Submit a nil Corporation Tax return (CT1) to Revenue within nine months of the financial year end, every year, without exception.
Leave VAT and employer PAYE registrations cancelled unless there’s a specific reason to keep them live — an unused live VAT number is one of the most common sources of unexpected penalties.
Diarise the Annual Return Date itself; missing it even for a genuinely dormant company triggers the same late fees and, after repeated lapses, the same loss of audit exemption as an active company.
A Quick Reference: Fees at Each Stage
CRO Fees Table 2026
Action
CRO fee (2026)
Annual return (Form B1), filed online
€20
Late filing penalty per return
€100 + €3/day, capped €1,200
Voluntary strike-off (Form H15)
€15
Administrative restoration (Form H1)
€300
Court order restoration lodgement
€15 (plus legal costs)
Business name cessation (Form RBN3)
No fee
These are the direct CRO fees only. Revenue penalties, interest, and any professional fees for preparing outstanding accounts or liaising with Revenue sit on top, and are almost always the larger part of the final bill for anyone recovering from a lapse rather than acting proactively.
Case Studies: Three Business Owners Who Fixed It
Case Study 1 — Restored Within the 12-Month Window
A Dublin design consultancy discovered, eight months after the fact, that its company had been struck off for missing two annual returns. Because it was still inside the 12-month administrative window, the director filed Form H1, submitted both outstanding annual returns with accounts, paid the capped late filing penalties, and had the company restored within several weeks — materially cheaper and faster than the court route it would have needed a few months later.
Case Study 2 — A Clean Voluntary Strike-Off
A part-time online retailer decided to close permanently after two years of declining sales. Before applying to the CRO, the director cancelled the VAT registration, filed a final VAT return accounting for the small amount of remaining stock, and confirmed no creditors were outstanding. The Form H15 application, newspaper notice, and 90-day objection period ran smoothly, and the company was dissolved in an orderly way with no penalties and no restoration ever required.
Case Study 3 — Reactivating a Dormant Company Instead of Starting Fresh
A founder who had paused a company for eighteen months while exploring a new venture wanted to start trading through it again rather than incorporate a new entity. Because the company had continued filing its annual return and nil CT1 every year while dormant, reactivation simply meant registering for VAT and employer PAYE again and updating Revenue on the resumption of trading — no restoration, no penalties, and no gap in the company’s history.
(These case studies are illustrative composites reflecting patterns we see regularly among Irish business owners, not individual clients.)
Frequently Asked Questions
How quickly should I act once I realise a company has been struck off?
Immediately. Administrative restoration is only available within 12 months of dissolution — after that, the only route is a High Court application, which costs significantly more and takes considerably longer.
Can I do the administrative restoration myself, or do I need a solicitor?
Form H1 can be filed directly through CORE without a solicitor, provided you can gather the outstanding returns, accounts, and any required Revenue confirmation yourself. Court restoration, by contrast, generally requires a solicitor to prepare the court application.
What happens to contracts or a bank account if the company is later restored?
Restoration is treated, for continuity purposes, as though the company had never been dissolved, which is what makes it possible to pick up existing arrangements. In practice, banks and counterparties may still ask questions about the gap, so it’s worth having the restoration paperwork ready to show.
Do I need to cancel VAT before I can voluntarily strike off a company?
Yes, in practice. The voluntary strike-off process assumes no outstanding Revenue position, and a live VAT registration with returns still due will hold up or invalidate the application.
Is it cheaper to restore an old company or just incorporate a new one?
It depends on the value tied up in the old entity — its trading history, contracts, VAT registration, or name. If none of that matters, incorporating fresh is often simpler. If the company has an established track record, restoring it within the 12-month window is usually the better value.
What if I genuinely can’t afford the restoration or penalty costs right now?
Speak to Revenue and, where relevant, the CRO before the relevant deadlines pass. Revenue operates phased payment arrangements for tax debts, and addressing the position early — even in instalments — is materially better than letting a strike-off or court restoration become the only remaining option.
How Forti Helps
We handle the practical side of every path above — restoration filings, voluntary strike-off applications, Revenue deregistration, and ongoing dormant company compliance — so the paperwork gets done correctly the first time, rather than compounding into a bigger bill later.
Get Back on Track With Forti
Monthly bookkeeping and management accounts from €195/month + VAT
Irish company formation, CRO fee included: €250
Company restoration, voluntary strike-off and dormant company filing support available on reques
Whether you’re inside the 12-month restoration window, ready to close a company for good, or need a dormant company kept compliant, get in touch with the Forti team at forti.ie — the earlier you act, the fewer of these fees actually apply to you.
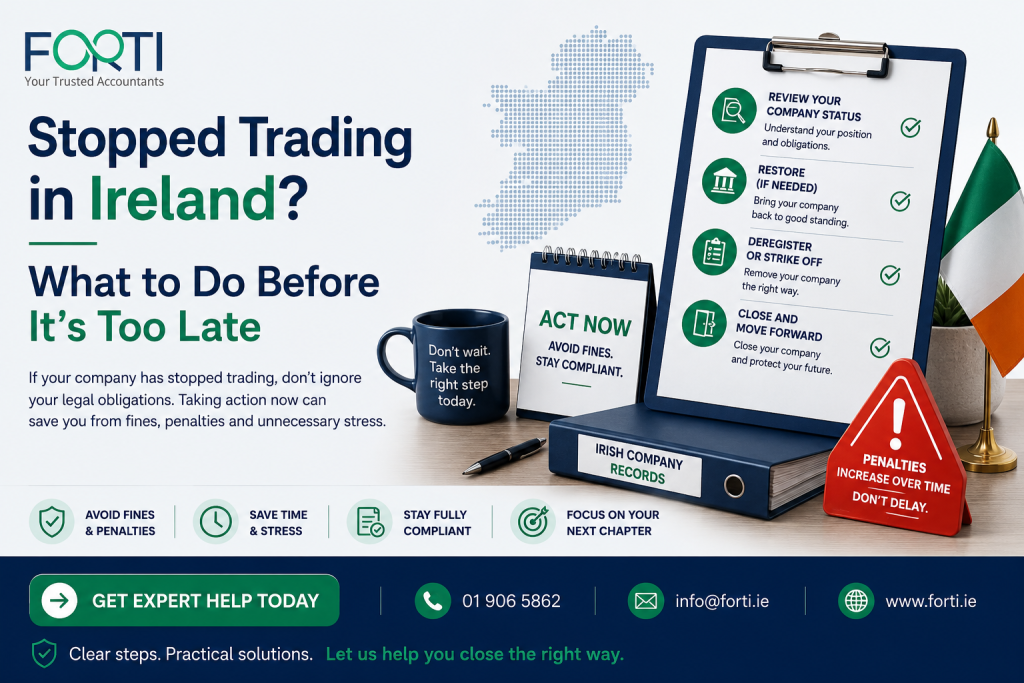
Every year, Irish business owners quietly stop trading and assume that’s the end of it. It isn’t — and in 2026, with the CRO and Revenue both enforcing more actively than at any point in recent years, that assumption is proving very expensive.
The Misconception That Costs Thousands
Closing the laptop is not the same as closing the company. When a shop stops taking orders, a contractor stops invoicing, or a founder simply moves on to something else, the company or business name they used doesn’t disappear along with the activity. It stays on the register at the Companies Registration Office (CRO), and it stays live with Revenue, until someone formally deals with it.
Throughout 2026, both the CRO and Revenue have sharply increased enforcement. Following the Companies (Corporate Governance, Enforcement and Regulatory Provisions) Act 2024, the CRO has fully resumed involuntary strike-off action against non-filing companies, and Revenue continues to apply fixed penalties and daily interest on unresolved VAT and tax positions regardless of whether a business is actually trading. Directors who assume that silence equals closure are the ones most often caught out.
Five Ways a Business Can Be ‘Not Trading’ — and What Each One Requires
1. Dormant Company (Still Registered, No Activity)
Under Section 365 of the Companies Act 2014, a company is dormant if it has no significant accounting transactions during the financial year and its only assets or liabilities are permitted ones (such as amounts due to or from group companies). A dormant company can qualify for audit exemption regardless of its size — but it is not exempt from filing. It must still file an annual return (Form B1) with the CRO every year and submit a nil Corporation Tax return (CT1) to Revenue within nine months of its year end. The single most common mistake we see is a director assuming ‘dormant’ means ‘no filing needed.’ It doesn’t.
2. Ceased Trading, But the Company Is Still on the Register
This is the grey zone that catches most people out. The business has stopped operating, but the company was never formally struck off or dissolved. Every statutory obligation continues exactly as before: CRO annual returns, corporation tax returns, and — critically — VAT and payroll registrations, which don’t cancel themselves. If you were VAT registered and don’t tell Revenue you’ve stopped trading, Revenue’s systems will continue to expect returns and will issue estimated assessments and penalties when they don’t arrive.
3. Sole Trader Who Stopped Self-Employment
Sole traders have it slightly simpler but the obligations are just as real. You need to notify Revenue that you’ve ceased self-employment, cancel any VAT and employer PAYE registrations that no longer apply, and file a final Income Tax return covering the period up to cessation. If you traded under a registered business name, you’re also required to notify the CRO of the closure within three months.
4. Voluntary Strike-Off (Closing Down Properly)
This is the correct route for a solvent company with no outstanding creditors that genuinely wants to close. Directors apply to the CRO using Form H15, confirm the company has ceased trading and has no assets or liabilities, and place a newspaper advertisement confirming the intention to close. Done correctly, this results in an orderly, planned dissolution — the opposite of what happens when a company is simply abandoned.
5. Involuntary Strike-Off (What Happens When Nothing Is Done)
This is the default outcome of doing nothing. When annual returns go unfiled, the CRO issues a statutory notice, followed — if there’s no response — by a public notice in the CRO Gazette. If the company still doesn’t act, it is struck off and dissolved. From that date, the company ceases to exist as a legal entity, limited liability protection ends, and anyone continuing to trade through it is doing so in a personal capacity. The full process typically runs several months from the first missed deadline, but once the Gazette notice is published, the clock moves quickly.
The Revenue Side: Obligations That Don’t Switch Off on Their Own
Ceasing to trade doesn’t cancel your tax registrations — you have to do that deliberately. Revenue requires a formal cancellation request (Form TRCN1, or notification through ROS) for VAT, employer PAYE, and Corporation Tax registrations. Until that’s done, Revenue’s systems keep expecting returns.
VAT: a fixed penalty of €4,000 can apply for late or non-registration, non-submission of returns, or incomplete and incorrect returns — each treated as a separate default. Unpaid VAT accrues daily interest at approximately 0.0274% per day (roughly 10% annualised).
Income Tax, Corporation Tax and CGT: unpaid liabilities accrue daily interest at approximately 0.0219% per day.
Failure to pay or file outstanding returns after a registration is formally ceased can still result in penalties and interest for the periods up to the cessation date — cancelling the registration doesn’t erase what was already due.
These are not nominal late fees that fade away on their own. They compound the longer a business owner leaves the position unresolved, and Revenue’s enforcement has become considerably more systemised in the past year.
The CRO Side: The Filing Obligation That Survives Closure of the Business
Compliance Failure Table
Compliance failure
Cost / consequence
Late annual return (Form B1)
€100 + €3/day, capped at €1,200
Late filing (more than once in 5 years)
Loss of audit exemption for 2 years
Forced statutory audit after losing exemption
Approx. €2,000–€8,000 per year
Persistent non-filing
Involuntary strike-off proceedings
Company struck off / dissolved
Loss of limited liability protection
Beyond the direct fees, a strike-off record is permanent and public. It shows up in due diligence for future investment, financing, or directorships, and directors of dissolved companies can face disqualification proceedings brought by the Corporate Enforcement Authority in more serious cases. Restoring a struck-off company is possible — administrative restoration within twelve months of strike-off, or a High Court application after that — but both routes involve legal costs, accumulated penalties, and outstanding filings, all of which must be cleared before restoration is granted
Case Studies: Three Business Owners, Three Outcomes
Case Study 1 — The Ecommerce Founder Who Just Stopped
A Dublin-based Shopify seller closed their online shop after eighteen months, moved on to full-time employment, and assumed the company would ‘wind down on its own’ since there was no activity left. Two annual returns were missed. The CRO issued a statutory notice, then a Gazette notice, and the company was struck off and dissolved roughly five months later. The founder discovered this only when a supplier queried an old invoice — by then, restoring the company required a court application, accumulated late filing penalties, and legal fees that came to several times what a proper voluntary strike-off would have cost at the outset.
Case Study 2 — The Consultant Who Forgot to Deregister VAT
An IT contractor stopped trading through their limited company to take up a permanent role, but never submitted a VAT cancellation request. Revenue’s system continued to expect bi-monthly VAT returns. After several periods with no returns filed, fixed penalties and daily interest began accumulating on an account that had, in reality, no further business activity. The position was only resolved once the company engaged an accountant to formally cancel the VAT registration and negotiate the outstanding penalties — a process that took weeks and cost considerably more than the five-minute cancellation would have, had it been done at the time trading stopped.
Case Study 3 — The ‘Dormant’ Company That Wasn’t Filing
A holding company set up for a property investment sat dormant for three years while its director focused on other ventures, on the assumption that a dormant company had no filing obligations at all. In fact, the company had missed its CRO annual returns for two consecutive years. This triggered the loss of audit exemption for the following two years, meaning the eventual return to compliance required a full statutory audit of accounts that, in substance, contained almost no transactions — an audit bill running into thousands of euro for a company that had done, quite literally, nothing.
(These case studies are illustrative composites reflecting patterns we see regularly among Irish business owners, not individual clients.)
How to Close, Pause, or Keep a Company Compliant — Properly
Decide early whether you’re pausing (dormant) or ending (strike-off) — the obligations are different, and ‘I’ll figure it out later’ is how both get missed.
If dormant: hold a directors’ meeting to formally record the dormancy decision, and keep filing your annual return and nil CT1 every year without fail.
If ceasing trading permanently: cancel VAT, employer PAYE and any other Revenue registrations via TRCN1 or ROS, file final accounts and a final tax return, and settle any outstanding liabilities.
If closing the company entirely: use the voluntary strike-off process (Form H15) while the company is solvent and has no outstanding creditors — this is materially cheaper and faster than recovering from an involuntary strike-off later.
If you traded under a registered business name as a sole trader, notify the CRO of the closure within three months using Form RBN3.
Frequently Asked Questions
If my company isn’t trading, do I still need to file anything?
Yes. A dormant or non-trading company still must file its CRO annual return every year and submit a nil Corporation Tax return to Revenue. Only a company that has been properly struck off or dissolved has no further filing obligation.
Can I just let Revenue and the CRO strike the company off on their own?
You can, but it’s the most expensive way to close a business. Involuntary strike-off leaves accumulated penalties, a permanent public compliance record, and — if you need the company back — a restoration process that costs far more than a planned voluntary strike-off.
What happens to my personal liability if the company is struck off?
Limited liability protection ends on dissolution. If the business continues to operate in any form afterwards, it’s being carried on in a personal capacity, without the legal protection the company structure was providing.
I stopped trading as a sole trader — is there anything to file with the CRO?
Only if you registered a business name. In that case, you must notify the CRO of the closure within three months using Form RBN3. You’ll also need to notify Revenue and file a final Income Tax return.
Does cancelling my VAT registration clear penalties from before the cancellation?
No. Cancelling a registration stops future obligations; it doesn’t remove liability for returns or payments that were already due before the cessation date. Outstanding periods still need to be filed and settled.
Can a struck-off company be restored?
Usually yes. Administrative restoration is available within twelve months of strike-off provided all filings are brought up to date and penalties paid. After that window, restoration requires a High Court order, which involves legal costs and takes considerably longer.
What’s the cheapest way to avoid all of this?
Make the decision — dormant, wind down, or close — while the company is still in good standing, and act on it immediately rather than leaving it unresolved. Every one of the case studies above would have cost a fraction of the eventual bill if addressed in the first few months.
How Forti Helps
Whether a company is dormant, has stopped trading, or needs to be closed down properly, we handle the CRO filings and Revenue cancellations that keep the process clean — so it doesn’t turn into a strike-off, a forced audit, or a personal liability problem months down the line.
Talk to Forti Before You Walk AwayMonthly bookkeeping and management accounts from €195/month + VATIrish company formation, CRO fee included: €250Dormant company filings, VAT/PAYE deregistration and voluntary strike-off support available on request.
If you’re thinking about pausing, closing, or you’ve already stopped trading and aren’t sure what’s still outstanding, get in touch with the Forti team at forti.ie before the CRO or Revenue make the decision for you.
For Irish-based online sellers shipping to customers across the EU, VAT is rarely simple — and getting it wrong is one of the most expensive mistakes a growing ecommerce business can make.
Why Ecommerce VAT Trips Up Even Careful Founders
Most Irish ecommerce founders start out registered for VAT in Ireland and assume that covers them. It doesn’t — not once sales cross into other EU member states. The rules that determine where VAT is due, at what rate, and under which scheme change the moment a business starts selling cross-border, and Revenue’s enforcement of these rules has tightened considerably as EU-wide reporting has become more joined up.
The good news is that the framework, once understood, is manageable. The two things that matter most are knowing your registration thresholds and knowing whether the One Stop Shop (OSS) scheme is right for your business — and both of those depend heavily on which platform, or mix of platforms, you’re actually selling through.
Step One: Categorise Your Sales Channels
Before any registration decision can be made, you need to know which category each of your sales channels falls into. VAT treatment is not the same across Shopify, Amazon, eBay and Etsy — the platform’s role in the transaction changes who is legally responsible for charging and remitting VAT.
Your Own Storefront: Shopify, WooCommerce, BigCommerce
On a self-hosted or owned storefront, you are the vendor of record for every sale. There is no intermediary collecting VAT on your behalf. This means your checkout needs to determine the customer’s location, apply the correct VAT rate, and your business needs to report that sale under either standard Irish VAT or the OSS scheme, depending on where the buyer is based. Full responsibility — and full liability if it’s done incorrectly — sits with you.
Online Marketplaces: Amazon, eBay, Etsy
Marketplaces are treated differently under EU ‘deemed supplier’ rules introduced in 2021. For certain transactions — mainly consignments valued under €150 imported from outside the EU, and sales by non-EU sellers to EU consumers — the marketplace itself is deemed to be the supplier for VAT purposes and collects and remits the VAT instead of you. Critically, this does not apply to every transaction: EU-based sellers shipping EU-held stock to EU consumers are generally still responsible for their own VAT, even when the sale happens through Amazon or eBay. Assuming the marketplace ‘has it covered’ across the board is one of the most common — and costly — misconceptions we see.
Multi-Channel and Hybrid Sellers
Most growing Irish ecommerce businesses end up selling through more than one channel — a Shopify store for brand and margin, plus Amazon or Etsy for reach. This is entirely normal, but it means your VAT reporting has to be built channel-by-channel: some sales collected and remitted by the marketplace, others fully your responsibility, all feeding into a single, reconciled VAT position. Trying to manage this with a single blended assumption across all channels is where errors creep in.
Irish VAT Registration Thresholds
Ireland applies two separate thresholds depending on what you’re selling. Once your turnover in any continuous 12-month period exceeds the relevant figure, VAT registration in Ireland becomes mandatory.
Registration trigger
Irish threshold
Supply of services
€42,500
Supply of goods
€85,000
Many ecommerce sellers combine goods and services (for example, a product business that also sells digital add-ons or consulting), which is where the calculation gets more complex. It’s worth reviewing your revenue mix at least quarterly rather than waiting for a year-end surprise.
Which Registration Applies — and at What Revenue Level
Once you know your channel mix, the next question is which registration(s) you actually need. For most Irish ecommerce sellers, it isn’t one registration — it’s a combination that builds up as revenue and reach grow.
Irish domestic VAT registration — required once you cross €42,500 (services) or €85,000 (goods) in Irish-based turnover. This is your baseline registration regardless of where else you sell.
EU OSS (Union scheme) — required once your total cross-border B2C sales into other EU member states exceed €10,000 in a calendar year. Below that figure you may continue charging Irish VAT on those sales; above it, OSS (or local registration in each country) becomes necessary.
Import One-Stop Shop (IOSS) — relevant if you import and sell goods valued at €150 or less directly to EU consumers from outside the EU. IOSS lets you charge VAT at the point of sale and avoid customers being hit with surprise import VAT on delivery.
Local country VAT registration — triggered independently of OSS the moment you store stock in another EU country, most commonly through Amazon FBA or a pan-EU fulfilment network. OSS covers the sale; it does not cover the stock movement or the fact that you now have a taxable presence in that country.
Intrastat — a separate statistical filing once your intra-EU goods movements pass the relevant threshold, regardless of your VAT or OSS status (covered in more detail below).
The practical implication: a Shopify-only seller under €10,000 in EU sales might need nothing beyond standard Irish VAT. The same business, once it starts using Amazon FBA with stock held in Germany, could simultaneously need Irish VAT, OSS, a German VAT registration and Intrastat reporting — four obligations arising from one growth decision. This is precisely why channel and fulfilment choices should be reviewed with your accountant before scaling, not after.
The One Stop Shop (OSS) Scheme, Explained
The OSS scheme was introduced to simplify EU VAT for cross-border sellers, and for most Irish ecommerce businesses selling B2C into other member states, it’s the better option than registering for VAT in every country you sell into.
One registration, filed through Revenue in Ireland, covers your VAT obligations across all EU member states where you sell to consumers.
You charge the VAT rate of the customer’s country, not Ireland’s, on qualifying cross-border B2C sales.
Returns are filed quarterly, consolidating all EU sales into a single OSS return rather than dozens of local filings.
OSS applies once your total cross-border B2C sales into other EU states exceed €10,000 in a calendar year (a separate, EU-wide distance-selling threshold from the Irish domestic thresholds above).
The trade-off is that OSS requires precise record-keeping: you need to track the customer’s country for every sale, apply the correct local VAT rate, and reconcile it all at quarter-end. This is where a lot of founders — perfectly capable of running the commercial side of the business — start to lose time and accuracy.
Don’t Forget Intrastat
If your ecommerce business moves physical goods across EU borders (holding stock in an overseas fulfilment centre is a common trigger), you may also have an Intrastat reporting obligation, separate from your VAT return. Intrastat tracks the physical movement of goods between EU member states for statistical purposes, and thresholds and filing frequency depend on your volume of intra-EU trade. It’s a common blind spot for sellers using pan-EU fulfilment models, since the obligation exists independently of whether you’re OSS-registered.
The Most Common Compliance Mistakes We See
Registering for VAT in Ireland but continuing to charge Irish VAT on cross-border B2C sales that should carry the customer’s local rate under OSS.
Missing the €10,000 EU-wide distance-selling threshold because it’s tracked separately from the Irish domestic thresholds.
Treating marketplace sales (Amazon, Etsy, eBay) as fully compliant by default — deemed supplier rules mean the marketplace may account for VAT on your behalf, but only for certain transaction types.
Overlooking Intrastat obligations when stock is held or moved through overseas warehouses.
Reconciling VAT annually instead of monthly, which turns small errors into large, hard-to-unwind ones.
Case Studies: Three Irish Sellers, Three Different Paths
Case Study 1 — Emerald Home Goods (Shopify, direct-to-consumer)
Emerald Home Goods sells homeware exclusively through its own Shopify store, shipping from a single warehouse in Dublin. As an owned-storefront seller, Emerald is the vendor of record for every transaction. Once EU sales (outside Ireland) passed €10,000 in a calendar year, Emerald registered for OSS through Revenue, allowing it to charge the correct local VAT rate for each EU customer through a single quarterly return rather than registering separately in each country. Because all stock stays in Ireland, no Intrastat or additional local VAT registrations were triggered — OSS alone covered the cross-border position.
Case Study 2 — CelticTech Gadgets (Amazon FBA, pan-EU fulfilment)
CelticTech Gadgets sells electronics accessories through Amazon, using Amazon’s pan-EU fulfilment network to hold stock in Germany and Poland for faster delivery. Because Amazon is the marketplace for these sales, deemed supplier rules meant Amazon collected and remitted VAT on qualifying transactions. However, storing stock in Germany and Poland created a taxable presence in each country, independent of Amazon’s role — meaning CelticTech needed local VAT registration in both, alongside its existing Irish VAT registration, and a monthly Intrastat filing to report the stock movements. OSS was not sufficient on its own because it doesn’t cover the cross-border movement of a seller’s own stock.
Case Study 3 — Aisling Crafts (Etsy and eBay, hobby to business)
Aisling Crafts began as a part-time Etsy shop selling handmade candles and grew into a registered business within eighteen months. Early sales stayed under both the Irish threshold and the €10,000 EU OSS threshold, so no VAT registration was required. As UK and EU orders grew, Aisling crossed the OSS threshold first, followed by the Irish domestic threshold shortly after. Because the business tracked its channel-by-channel revenue from the outset, both registrations were completed proactively rather than in response to a compliance query from Revenue — avoiding any late-registration penalties or backdated VAT exposure.
(Emerald Home Goods, CelticTech Gadgets and Aisling Crafts are illustrative composites based on common patterns we see across Irish ecommerce clients, not individual businesses.)
Frequently Asked Questions
Do I need to register for VAT if I only sell within Ireland?
Only once your turnover exceeds the relevant Irish threshold — €42,500 for services or €85,000 for goods in any continuous 12-month period. Below that, registration is optional, though some businesses register voluntarily to reclaim VAT on costs.
If Amazon collects VAT on my sales, do I still need to register?
Possibly. Amazon’s deemed supplier rules only apply to specific transaction types — mainly low-value imports and non-EU seller sales. If you’re an Irish seller with EU-held stock, you very likely still carry the VAT obligation yourself, and may need OSS or local registration regardless of Amazon’s involvement.
Does OSS replace the need for Irish VAT registration?
No. OSS is an additional scheme for reporting cross-border B2C sales into other EU states. You still need standard Irish VAT registration once you exceed the domestic threshold, and OSS sits alongside it for EU sales beyond the €10,000 distance-selling threshold.
What happens if I store stock in another EU country?
Holding stock abroad — commonly through Amazon FBA or a European 3PL — generally creates a local VAT registration requirement in that country, along with an Intrastat obligation, regardless of your OSS status. This is one of the most frequently missed obligations for scaling sellers.
How often do OSS and Intrastat returns need to be filed?
OSS returns are filed quarterly. Intrastat filing frequency depends on your volume of intra-EU trade, but is typically monthly once the threshold is triggered.
What are the penalties for getting this wrong?
Penalties can include interest and fixed penalties on late or incorrect VAT, backdated liabilities if registration should have happened earlier, and in more serious cases, Revenue audit exposure. The cost of correcting a multi-country VAT position retrospectively is almost always higher than the cost of setting it up correctly from the start.
How Forti Helps Ecommerce Sellers Stay Compliant
This is exactly the kind of complexity we handle day-to-day for Irish ecommerce clients — from initial VAT and OSS registration through to ongoing monthly bookkeeping and quarterly OSS filings. We build the reporting so that country-by-country VAT is tracked correctly at the point of sale, not reconstructed under pressure at return time.
Work with Forti
Monthly bookkeeping and management accounts from €195/month + VAT
Irish company formation, CRO fee included: €250
VAT, OSS registration and Intrastat compliance built in for ecommerce clients
Every week, people search for some version of the same question: “Can I hire someone to open a company in Ireland for me?” The answer is yes — and it is simpler, faster, and more affordable than most people expect.
Whether you are a non-resident founder wanting an EU base, an IT contractor transitioning from PAYE, a returning emigrant setting up a consultancy, or an international business establishing an Irish subsidiary — Forti Accountants handles the entire formation and compliance process on your behalf. You do not attend an office. You do not fill in CRO forms. You do not call Revenue. We do all of it.
Why Most People Want Someone Else to Handle This
Irish company formation is not technically complex — but it is time-consuming, procedurally specific, and easy to get wrong if you are not familiar with how the Companies Registration Office (CRO) and Revenue operate. The typical DIY journey involves:
Researching CRO requirements and choosing the correct company type
Drafting and filing a Constitution (previously called a Memorandum and Articles of Association)
Selecting and registering a company name, including conflict checks against the CRO register
Appointing at least one EEA-resident director — or arranging a Section 137 bond if non-EEA
Registering a company registered address in Ireland (a physical address, not a PO Box)
Filing Form A1 with the CRO — the primary incorporation document
Registering with Revenue for Corporation Tax, VAT, and Employer PAYE
Opening a business bank account — which itself requires certified company documents
Setting up payroll, bookkeeping, and real-time Revenue reporting (ERR) systems
Each step involves specific forms, reference numbers, and processing timelines. A single error — a misspelt director name, an incorrect PPSN, a missing signature field — can delay incorporation by weeks. For someone running a business or operating from abroad, this is not the best use of their time.
The Core Reason People Outsource Formation
It is not that the process is impossible. It is that the cost of getting it wrong — delays, incorrect registrations, compliance gaps from day one — far exceeds the cost of having a specialist handle it correctly the first time.
What “We Handle Everything” Actually Means
When Forti says we handle everything, that is a precise statement. Below is every task Forti manages on your behalf as part of a full company formation engagement:
Task
Handled by
When
Company name search and reservation
✔ Forti
Day 1
Constitution drafting (company rules document)
✔ Forti
Day 1
Form A1 preparation and CRO filing
✔ Forti
Day 1–2
Registered address provision (if needed)
✔ Forti
Day 1
EEA director arrangement (if applicable)
✔ Forti
Day 1–3
Revenue — Corporation Tax registration (TR2)
✔ Forti
Post-CRO
Revenue — VAT registration
✔ Forti
Post-CRO
Revenue — Employer PAYE registration
✔ Forti
Post-CRO
ROS (Revenue Online Service) setup
✔ Forti
Post-CRO
Xero cloud accounting setup + bank feed
✔ Forti
Week 1
Payroll system setup + first payrun
✔ Forti
Week 1–2
Bank account referral and documentation pack
✔ Forti
Week 1
Director’s service agreement template
✔ Forti
Week 1
Ongoing compliance calendar + deadline reminders
✔ Forti
Ongoing
Your role in the process is limited to: providing your personal details, signing completed documents electronically, and attending a single onboarding call of approximately 30–45 minutes. Everything else is handled by Forti.
The Step-by-Step Process — From First Call to Trading
Here is exactly what happens once you engage Forti to handle your company formation:
Free consultation call (Day 0)
A 30-minute call with your Forti accountant to understand your business type, revenue model, expected income, client base, and whether you need VAT registration, multiple directors, or specialist structure. No cost, no obligation.
Information collection (Day 1)
Forti sends you a short secure onboarding form — your full legal name, date of birth, home address, PPSN (or foreign tax identifier), and proposed company name preferences. This takes approximately 10 minutes to complete.
Name check and CRO filing (Day 1–2)
Forti searches the CRO register for conflicts, confirms your preferred name, drafts the Constitution, prepares Form A1, and files with the CRO electronically. Standard CRO processing takes 3–5 business days. Expedited processing (same-day) is available at an additional CRO fee of €50.
Certificate of Incorporation issued (Day 5–7)
The CRO issues your Certificate of Incorporation with your unique Company Registration Number (CRN). Forti receives it on your behalf and sends you a copy immediately.
Revenue registrations (Day 7–10)
Using your CRN, Forti registers the company with Revenue for Corporation Tax, VAT (if applicable), and Employer PAYE. Revenue assigns your Tax Reference Number (TRN). Forti handles all ROS access setup.
Banking and accounting setup (Week 2)
Forti provides a bank referral letter and full documentation pack for your business bank account application. Simultaneously, your Xero cloud accounting environment is set up with automated bank feeds.
Payroll and first invoice (Week 2)
Your director salary is configured on payroll and your first payslip is processed. If billing clients from day one, Forti provides an invoice template with your company number, VAT number, and correct Irish payment terms.
You start trading — Forti handles everything else
From this point, Forti manages your ongoing compliance: bi-monthly VAT returns, monthly payroll, annual financial statements, corporation tax return, and ERR reporting. You focus on your work.
Typical Timeline
From your first call to a fully operational company — registered with the CRO and Revenue, with accounting and payroll set up — takes approximately 10–14 business days in standard cases. Expedited CRO formation can issue your Certificate of Incorporation within 24 hours of filing.
Setting Up Remotely — No Irish Address Required
One of the most common questions from international enquirers: “Do I need to be in Ireland to set up the company?” The answer is no. Forti has completed formations entirely remotely for clients in the United States, Canada, Australia, the UK, across the EU, and the Middle East.
The Non-EEA Director Requirement
Irish company law requires at least one director ordinarily resident in an EEA country. If you are not EEA-resident, two compliant solutions are available:
Section 137 bond: A €25,000 insurance bond placed with a registered insurer — Forti arranges this on your behalf.
Nominee EEA director: Forti can refer you to a compliant nominee director service. The nominee has no operational control — they exist solely to satisfy the legal requirement.
Registered Address in Ireland
Every Irish company must have a registered address in Ireland — a physical address where CRO and Revenue correspondence is received. Forti provides a registered address service as part of the formation package. All correspondence received is scanned and forwarded to you digitally on the day of receipt.
Fully Remote Formation — What You Need to Provide
To set up an Irish company remotely through Forti, you need:
(1) a government-issued photo ID;
(2) proof of your home address;
(3) your PPSN if you have one — or a foreign tax identification number;
(4) approximately 10 minutes to complete an online form.
Everything else is handled by Forti.
Case Studies: Two Real Formation Stories
The following case studies are based on composite client profiles from Forti’s formation client base. Names and details have been fictionalised. Financial outcomes are realistic representations under current Irish Revenue rules.
1. Łukasz — Polish-born Software Engineer, Remote Formation from Warsaw
14 days
Call to trading
€700/day
Contract day rate
0
Forms filled by Łukasz
Łukasz is a senior DevOps engineer who moved from Ireland to Warsaw in 2022 after his employer went fully remote. In early 2026, he secured a contract with a Dublin-based fintech paying €700 per day. The client required him to invoice through an Irish-registered entity — either an umbrella company or his own limited company.
Background
Łukasz had no Irish address, no Irish bank account, and had not used his PPSN in several years. He had never formed a company before. He found Forti through an online search and booked a free consultation the same day.
What Forti handled
Confirmed Łukasz’s PPSN was still active with Revenue
Provided a registered Irish address for the company
Filed Form A1 with the CRO — Certificate of Incorporation issued in 4 business days
Registered the company for Corporation Tax and VAT with Revenue
Set up Xero with automated bank feeds linked to his Wise Business account
Issued his first invoice template — he sent it to his client on day 14
Key Complexity Resolved
Łukasz’s client required a VAT number on the invoice. Because his annual billing would exceed €40,000 from a single Irish client, VAT registration was mandatory. Forti registered the company for VAT within 5 days of the Certificate of Incorporation — meaning there was no delay to his first invoice.
Results after 12 months
Metric
Outcome
Gross annual revenue (200 days @ €700)
€140,000
Director salary extracted
€42,000
Employer PRSA contribution
€40,000
Corporation tax paid
€6,100
PSS surcharge
€0
Forms filled by Łukasz personally
0
Forti monthly fee
€195 + VAT
“I genuinely had no idea how to set up an Irish company from abroad. I assumed it would take months and involve a solicitor. Forti had it done in two weeks and I never had to travel to Ireland once. The whole thing was done over email and one video call.”
— Łukasz, DevOps Engineer, client since January 2026
2. Sinéad — Irish Marketing Consultant, Transitioning from Agency to Freelance
7 days
Call to incorporated
€95k
Year-one revenue
3
Active clients by month 3
Background
Sinéad spent eight years as a senior digital marketing manager at a Dublin agency before going independent in late 2025. She had two clients lined up and a clear service offering — brand strategy and performance media for Irish SMEs. Her projected year-one revenue was €90,000–€100,000.
Sinéad’s concern was not whether to form a company — she knew she needed one. It was about getting it right: the correct structure, the right VAT setup, and a system that would keep her compliant without consuming her time. A contractor friend referred her to Forti.
What Forti handled
Advised on optimal company structure — single-director LTD was appropriate
Confirmed VAT registration was required from day one given projected revenue
Filed Form A1 — Certificate of Incorporation issued in 7 business days
Registered for Corporation Tax, VAT (23%), and Employer PAYE with Revenue
Set up Xero with automated expense capture via Hubdoc
Configured payroll for a monthly director salary of €3,500 (€42,000 per annum)
Prepared client contract template and invoice template with correct Irish VAT wording
“What I valued most was that Forti didn’t just set up the company and disappear. They explained what I should be paying myself, when to think about pension contributions, and what to do at year-end — before those decisions became urgent. That proactive advice is what I was really paying for.”
— Sinéad, Marketing Consultant, client since November 2025
What It Costs — Transparent Pricing
Forti‘s formation and ongoing accounting fees are straightforward. There are no hidden charges, no surprise add-ons, and no annual fee hikes without notice.
Service
Fee
Notes
Initial consultation
Free
30–45 minute call, no obligation
Company formation (CRO filing + all Revenue registrations)
€200 + VAT
One-off. Includes name search, Form A1, TR2, VAT & PAYE registration
CRO standard processing fee
€50
Paid directly to CRO — not a Forti charge
Expedited CRO processing (same-day)
€100 additional
Optional — Certificate within 24 hours of filing
Registered office address (if needed)
€450/year + VAT
Includes scanning and digital forwarding of all correspondence
Section 137 bond (non-EEA directors)
At cost
Forti manages — typically €1,500–€2,000 first year
A qualified accountant charges €150–€300 per hour. Correct company formation — name checks, Constitution drafting, CRO filing, and all Revenue registrations — typically takes 4–6 hours of professional time. Forti’s flat formation fee of €200 + VAT represents significant value versus hourly billing, and eliminates the risk of errors that delay your trading start date.
10 Frequently Asked Questions
1. Do I need to be in Ireland to form an Irish company?
No. The entire formation process can be completed remotely. Forti handles all CRO filings and Revenue registrations electronically. You will need to provide proof of identity and address, sign documents electronically, and complete a short online information form. No in-person attendance is required at any stage. Forti has completed formations for clients based in the US, UK, Poland, UAE, Australia, and across the EU — all without the client setting foot in Ireland.
2. How long does it take to form an Irish company?
The CRO’s standard processing time is currently 3–5 business days from the date of filing. Once Forti has your information (typically day one of engagement), Form A1 is filed that day or the next. Your Certificate of Incorporation typically arrives within 5–7 business days. Expedited CRO processing is available for an additional €50 fee, issuing the Certificate within 24 hours. Revenue registrations follow and are typically completed within a further 5 business days. Total time from first contact to fully operational: approximately 10–14 business days.
3. What type of company should I form?
For the vast majority of Irish contractors, consultants, and small business owners, a Private Company Limited by Shares (LTD) is the correct structure. It requires a minimum of one director and one shareholder (who can be the same person), has no minimum share capital requirement, and benefits from the 12.5% Corporation Tax rate on trading profits. Forti will confirm the right structure during your initial consultation — in some cases a DAC or CLG may be more appropriate, and Forti will explain why.
4. I don’t have an Irish address — can I still form a company?
Yes. Every Irish company must have a registered address in Ireland where official CRO and Revenue correspondence is received. If you do not have an Irish address, Forti provides a registered address service at €450 per year + VAT. All official correspondence received is scanned and forwarded to you digitally on the day of receipt. This is entirely standard practice used by thousands of Irish companies.
5. Do I need a PPSN to form an Irish company?
Directors of Irish companies are required to provide a PPS number when registering with Revenue. If you are an Irish citizen or previously worked in Ireland, you will already have a PPSN — Forti can verify it is still active. If you have never held a PPSN and are not resident in Ireland, Revenue accepts foreign tax identifiers for non-resident directors. Forti navigates this process on your behalf.
6. What is the difference between company formation and company registration?
In common usage the terms are interchangeable. Technically, ‘formation’ describes the legal act of creating the company entity (CRO filing and Certificate of Incorporation), while ‘registration’ refers to the broader combined process of formation plus Revenue tax registrations. When Forti handles your formation, both are included: CRO filing and all Revenue registrations are managed as a single, complete process for the one flat fee.
7. Can Forti set up a company for me if I already have a UK company?
Yes — this is a common scenario since Brexit. Many UK-based businesses want an Irish (and therefore EU) entity for regulatory reasons, EU client relationships, or EU procurement access. Forti handles this as a standard formation. Your Irish company will be a separate legal entity from your UK company, with its own CRN, tax reference, and bank account. Forti can also advise on intercompany arrangements and transfer pricing considerations.
8. What ongoing responsibilities do I have after the company is formed?
An Irish LTD has several annual compliance obligations: filing an Annual Return with the CRO; submitting a Corporation Tax return (CT1) within 9 months of your financial year-end; filing VAT returns (bi-monthly for most companies); running monthly payroll; and meeting Enhanced Reporting Requirements (ERR) for employee expenses in real time. All of the above are managed by Forti as part of the monthly service. You will never miss a filing deadline.
9. What happens if my company doesn’t trade for a while after formation?
A company that is not yet trading is known as a dormant company. Dormant companies still have Annual Return obligations with the CRO — failure to file results in late fees and, ultimately, the company being struck off the register. Revenue obligations are suspended during dormancy but must be formally notified to Revenue. Forti manages dormancy status on your behalf — we notify Revenue, file nil returns where required, and ensure your company remains in good standing.
10. Why use Forti rather than an online company formation service?
Online formation services typically file your Form A1 and stop there — you receive a Certificate of Incorporation and are left to handle Revenue registrations, VAT, payroll, accounting, and ongoing compliance yourself. Forti’s formation service is the beginning of a complete, managed accounting relationship. We handle the CRO filing, all Revenue registrations, Xero setup, payroll configuration, and ongoing monthly compliance — under one fee, with one point of contact, and with proactive tax planning built in from day one.
Ireland’s technology sector is booming. Software engineers, DevOps architects, data engineers, and product managers are commanding daily rates between €550 and €850+ — figures that permanently employed peers rarely see reflected in their monthly payslips.
This guide cuts through the jargon and shows you exactly what the numbers look like — whether you’re weighing up your first contract or optimising an existing limited company structure.
The Mindset Shift: Permanent Employee vs. IT Contractor
The most significant barrier between a talented technologist and the contractor life is not technical — it is psychological. Permanent employment offers guaranteed salary, employer pension, sick pay, and the comfortable illusion of job security. But here is the reality: the permanent contract is, in many ways, a wealth-limiting arrangement.
As a contractor, you reclaim the margin your employer captures on your skills — and the Irish tax system, when navigated correctly, allows you to keep far more of it.
From Trading Time for Salary to Selling Expertise at Market Rate
A permanent employee earning €85,000 per year takes home approximately €57,000 net after income tax, USC, and PRSI. That is it, regardless of the revenue your skills generate for your employer. An IT contractor billing €650 per day over 220 working days generates €143,000 in gross company revenue. Through a properly structured Personal Limited Company, the same individual can retain significantly more after-tax wealth and simultaneously build a substantial pension fund.
What Autonomy Actually Looks Like
Control over your rate — your skills have a market price; contracting lets you charge it
Tax efficiency through structure — your company pays 12.5% corporation tax, not your marginal income tax rate
Asset accumulation — your LTD becomes a vehicle for pension wealth and retained earnings
Flexibility — between contracts you choose: breaks, upskilling, travel
The shift from employee to contractor is not about risk tolerance — it is about recognising that you already take on risk as a PAYE worker (redundancy, restructuring, stagnant pay reviews), but receive none of the financial upside in return.
Business Structures: Umbrella Company vs. Personal LTD
Once you decide to contract, the next decision is how to structure your business. In Ireland, there are two primary routes. Neither is universally ‘right’ — the optimal choice depends on your income level, time horizon, and financial goals.
Comparison at a Glance
Factor
Umbrella Company
Personal LTD Company
Setup Speed
✔ Same day
2–5 business days
Admin Burden
✔ Very low — managed
Moderate — needs accountant
PRSI Class
✔ Class A (employee)
Class S (director)
Tax Efficiency
✘ Low — taxed as PAYE
✔ High — 12.5% CT rate
Pension Options
~ Limited personal only
✔ Unlimited employer PRSA
Expense Deductions
✘ Very limited
✔ Full business expenses
Wealth Building
✘ Minimal
✔ Significant potential
Ownership & Control
✘ None — umbrella employs you
✔ Full company ownership
Best Suited For
Short-term / first contracts
Consistent income >€80k p.a.
The Umbrella Company Route
An umbrella company acts as your employer of record. They invoice your end client or agency, deduct income tax, USC, and PRSI (Class A), and pay you a net salary — keeping a fee for the service.
The appeal: zero administrative overhead, instant start, and you retain access to Class A PRSI — maintaining entitlement to Jobseeker’s Benefit between contracts and contributing toward state pension eligibility.
The trade-off: you will be taxed at the marginal income tax rate (up to 40% + USC + PRSI) on almost all your contractor income. For a contractor billing €600/day, this typically results in significantly lower after-tax income compared to an LTD structure.
UMBRELLA COMPANIES: A WORD OF CAUTION
Not all umbrella companies are created equal. Some make claims about tax efficiency that are not compliant with Irish Revenue rules. Always verify that your umbrella company operates a fully PAYE-compliant model and is registered with Revenue as an employer.
The Personal Limited Company (LTD)
For contractors billing at sustained rates of €80,000 per annum or above, incorporating a Personal Limited Company is almost always the more financially intelligent structure. You become a director and shareholder of your own company. The company invoices clients, collects revenue, and pays 12.5% corporation tax on its profits.
Corporation Tax rate: 12.5% on trading profits (versus up to 52% marginal PAYE rate)
Salary extraction: Pay yourself efficiently, leveraging personal tax credits
Compliance is not optional. Understanding the rules protects your contracting income, your business, and your reputation. In 2026, three areas demand particular attention from IT contractors in Ireland.
The Karshan Case (2023) & Employment Status
In 2023, the Irish Supreme Court delivered its landmark judgment in Karshan (Midlands) Ltd v Revenue Commissioners. The court affirmed a five-step framework to distinguish genuine self-employment from what Revenue terms ‘disguised employment.
1. Mutual Obligation — Does the client have an obligation to offer work, and do you have an obligation to accept it? A genuine contractor can decline assignments. If you must accept whatever is offered, this suggests employment.
2. Substitution — Can you send a qualified substitute to perform the work in your place? If yes — and this right exists in practice — it strongly indicates self-employment.
3. Control — Does the client dictate how you work (tools, methods, hours), or do they simply define the outcome required? Genuine contractors control their own working methods.
4. Integration — Are you integral to the client’s business — on their systems, org chart, attending internal meetings as an employee would? Genuine contractors remain external service providers.
5. Economic Reality — Do you bear genuine financial risk? Do you invest in your own equipment, market services to multiple clients, and stand to profit or lose based on efficiency?
Risk: Reclassification
If Revenue determines that your contracting arrangement is effectively disguised
employment, the consequences can be severe — back-payment of PAYE, PRSI, and USC
with interest and penalties. Your contract and working practices must genuinely
reflect self-employment. The substance of the arrangement matters, not just the
paperwork.
The Professional Services Surcharge (PSS)
The Professional Services Surcharge is one of the most frequently misunderstood — and most expensive when mismanaged — elements of Irish contractor taxation.
Under Section 441 TCA 1997, a 15% surcharge applies to 50% of the undistributed trading income of a company providing professional services in a given accounting year. In plain terms: if your company earns significant profits and you leave them sitting in the company without extracting them or directing them to a pension, Revenue will levy an additional 15% charge on half of those retained profits — on top of the 12.5% corporation tax already paid.
How to Manage the PSS Effectively
Extract a reasonable salary — reduces retained profits and PSS exposure
Maximise employer PRSA contributions — reduces company profit before CT, directly reducing the PSS base (the single most powerful tool)
Pay dividends strategically — distributing profits reduces the ‘undistributed’ element subject to the surcharge
Time your year-end carefully — the PSS is calculated per accounting year; plan extractions before year-end
Work with a proactive accountant — the PSS is entirely avoidable with proper planning
Expenses & Enhanced Reporting Requirements (ERR)
Since 1 January 2024, Revenue’s Enhanced Reporting Requirements (ERR) mandate that employers — including director/shareholders of personal LTD companies — report certain expense payments to Revenue in real time via ROS.
The golden rule for business expenses remains unchanged: costs must be incurred wholly, exclusively, and necessarily for the purposes of the trade.
Expense Category
Deductible?
Notes
Professional indemnity & liability insurance
✔ Yes
Required by most contracts — fully deductible
Laptop, monitor, peripherals
✔ Yes
Capital allowances: 12.5% p.a. over 8 years
Software & SaaS subscriptions (business)
✔ Yes
Must be for business use — document this
Home office (heat, light, broadband)
~ Partial
Revenue e-worker flat rate or apportionment
Travel to client site (not home to office)
✔ Yes
Civil service mileage rates — must be logged
Professional development & training
✔ Yes
Relevant courses, certifications, conferences
Accountancy & legal fees
✔ Yes
Fully deductible as a business operating cost
Client entertainment / meals
✗ No
Revenue does not allow entertainment expenses
Commuting (home to regular workplace)
✗ No
Personal cost — not a business deduction
ERR Compliance in 2026
From 2024 onwards, Revenue ERR requires real-time digital reporting
of employee benefits and certain expense payments via ROS — before or
on the date the payment is made. Penalties apply for non-compliance.
Forti’s automated Xero-integrated workflows handle ERR reporting as standard.
The Numbers: Earning Potential & Wealth Building
Let’s put figures on what the contractor structure actually means. The following comparison uses realistic 2026 figures for a senior Irish IT professional — software engineer or architect level, 8–12 years of experience.
Scenario: Permanent PAYE vs. IT Contractor LTD (Same Skill Level)
Metric
PAYE Employee (€85k)
IT Contractor LTD (€650/day)
Gross annual income
€85,000 salary
€143,000 billing (€650×220)
Income tax & USC
~€24,720
Salary only: ~€12,000
PRSI
~€3,040
Director Class S: ~€5,700
Employer PRSA contribution
€4,250 (employer 5%)
€40,000 (unlimited, no BIK)
Corporation tax
N/A
~€6,400 on balance
Annual net cash take-home
~€57,240
~€34,200 net salary
Total annual wealth created
~€61,490
~€96,000+ (cash + pension)
Advantage vs. PAYE
—
+€34,500 per year
* Figures are illustrative based on 2026 Revenue bands. Individual circumstances and allowable deductions will vary. Always seek personalised advice from a tax-focused accountant.
Key Market Figures — IT Contracting in Ireland, 2026
Typical IT contractor daily rate in Dublin: €550 – €850+
Irish Corporation Tax rate on trading profits: 12.5%
Employer PRSA contributions: Unlimited (no BIK since Finance Act 2023)
Marginal PAYE rate (income tax + USC + PRSI): up to 52%
The PRSA Revolution: Tax-Free Wealth Through Your Company
The 2023 Finance Act delivered a game-changing provision for IT contractors. From 1 January 2023, employer contributions to an employee’s PRSA are no longer subject to the Benefit in Kind caps that historically limited their effectiveness.
In practical terms, your limited company can now pay any amount into your PRSA as an employer contribution. These contributions are:
Fully deductible against your company’s corporation tax liability
Not subject to Benefit in Kind — no income tax, USC, or PRSI arises on you
Growing tax-free within the pension fund until retirement
Accessible from age 60 with up to 25% as a tax-free lump sum
The Pension Advantage In Numbers
€40,000 contributed to a PRSA by your LTD as an employer contribution
costs the company approximately €40,000 (reducing its CT liability by
€5,000). The same €40,000 extracted as salary would be subject to up
to 52% marginal tax — costing nearly €20,800 in personal tax. The
pension route is, in many scenarios, 2x more capital-efficient.
Accountancy Fee Price Guide — Ireland 2026
One of the most common questions from contractors considering a personal LTD is: how much does proper contractor accounting actually cost? The honest answer is: less than you think, and far less than the value it delivers.
Full-service LTD contractor accounting in Ireland — covering VAT returns, monthly payroll, bookkeeping, year-end financial statements, and corporation tax returns — typically ranges from €150 to €250+ per month plus VAT.
Service Comparison
Service
Market Range
Forti Accountants
VAT returns (bi-monthly)
✓ Basic
✓ Full + Revenue ERR
Payroll processing
✓ Director only
✓ Salary + dividend optimised
Bookkeeping
Basic
✓ Xero real-time cloud
ERR compliance (2024+)
✗ Not included
✓ Included as standard
Year-end accounts + CT1
✓
✓
PSS & pension planning
✗ Reactive only
✓ Proactive quarterly review
Karshan status review
✗
✓ Contract review included
Dedicated tech-specialist
✗ Shared team
✓ Named accountant
Typical monthly cost
€150–€200 +VAT
From €195 +VAT
Why Technology Makes the Difference
Not all accountancy practices are equal — and the difference is rarely in the technical knowledge. It is in the systems, responsiveness, and whether your accountant is reactive (catching problems after the fact) or proactive (preventing them and actively growing your wealth).
Forti Accountants is built specifically for Ireland’s technology professional sector — software engineers, DevOps leads, data architects, and tech founders across Dublin and remote-first roles.
Xero-integrated bookkeeping — real-time P&L, VAT position, and cash flow visibility at any moment
Automated digital workflows — expense capture via Hubdoc, automated bank feeds, digital approval
Proactive tax planning — quarterly review calls to optimise salary, pension, and dividend timing
ERR compliance built in — all required real-time Revenue reporting handled as standard
A contractor billing €143,000 annually who avoids the PSS through
proper pension planning typically saves €6,000–€10,000 per year in
unnecessary surcharge. Forti’s service from €195/month costs €2,340
per year — the proactive planning alone delivers a net return of
3×–4× the accountancy fee before counting additional corporation
tax savings.
🚀
Initial Setup
(First 6 Months)
UMBRELLA COMPANY
✓
Zero administrative setup required
€
Income taxed entirely under PAYE
📄
Retained only ~51% of gross earnings
➜
📈
Optimised Transition
PERSONAL LTD COMPANY
🏢
Set up via Forti & Xero
%
Taxed at 12.5% CT rate
↗
Net wealth retention >72%
Client Case Studies & FAQs
Real-world contractor outcomes & expert answers — Forti Accountants, June 2026
The following case studies are based on composite client profiles from Forti’s contractor client base. Names and identifying details have been fictionalised. Financial figures are realistic representations of outcomes achievable under current Irish Revenue rules. The FAQs address the questions we hear most frequently from IT professionals considering or already operating through a limited company.
From Permanent Dev to €130k Contractor: Ciarán’s Story
€85,000
Previous PAYE salary
€650/day
Contracting day rate
+€38,400
Additional annual wealth
Background
Ciarán is a senior software engineer with eleven years of experience, specialising in cloud-native architecture on AWS and Azure. In early 2024, his employer — a Dublin-based fintech — announced a restructuring that eliminated his role. Rather than accept the first permanent offer that came his way, Ciarán contacted Forti to explore whether contracting was a viable path.
At the time, Ciarán was earning €85,000 per year in a permanent PAYE role. His net monthly take-home after income tax, USC, and PRSI was approximately €4,700. He had a modest PRSA with €42,000 accumulated over eight years — largely because his employer’s contributions were the minimum 3% and he had not made significant personal top-ups.
The Challenge
Ciarán’s hesitations were typical of a first-time contractor. He worried about the administrative burden of running a company, was unclear on the tax implications, and was concerned about losing his Class A PRSI entitlement — particularly Jobseeker’s Benefit protection between contracts.
After a detailed free consultation with Forti, it became clear that Ciarán’s skills were in extremely high demand in the Dublin contract market, with day rates for his profile ranging from €620 to €720. We walked him through the Karshan employment status framework, the Personal LTD structure, and modelled the difference between umbrella and LTD routes at his income level. The numbers made the decision straightforward.
The Solution: Personal LTD + Aggressive PRSA Strategy
Forti incorporated Ciarán’s company — CKD Tech Solutions Ltd — within four business days of engagement. We registered for VAT (standard 23% on IT services), set up payroll, and onboarded him to Xero with automated bank feeds from his company current account.
The key insight from Ciarán’s tax planning session was that he had significant scope to use employer PRSA contributions to rebuild his pension fund rapidly — something the post-2023 Finance Act changes made dramatically more effective. We structured his extraction as follows:
Annual director salary: €42,000 — efficiently utilising personal tax credits and standard rate band
Employer PRSA contribution: €45,000 per year — fully deductible for the company, zero BIK on Ciarán
Retained profit in company: managed below PSS threshold through salary + pension extraction
VAT billing: registered and filing bi-monthly returns via ROS — managed entirely by Forti
ERR compliance: all expense payments reported in real time via automated Xero workflow
Karshan Compliance Check
Ciarán’s contracts with his two clients were reviewed by Forti against the five-step Karshan framework. We confirmed:
(1) no mutual obligation — he works project-by-project;
(2) right of substitution is included in his contracts;
(3) he supplies his own MacBook Pro and cloud tooling;
(4) he bills via company invoice, not staff email;
(5) he carries professional indemnity insurance of €1m and bears genuine financial risk.
His self-employed status is robust.
Results After 12 Months
Metric
Outcome
Gross company revenue (220 days @ €650)
€143,000
Net annual salary extracted (after tax)
€34,100
Employer PRSA contribution (tax-free wealth)
+€45,000
Corporation tax paid
€6,200
PSS surcharge
€0 — fully avoided through planning
Total annual wealth created (cash + pension)
~€79,100
vs. previous PAYE net + employer pension
+€17,600 additional per year
PRSA fund balance after 12 months
€87,000 (incl. prior + investment growth)
Forti monthly fee
€195 + VAT
Beyond the numbers, Ciarán reported that the Xero dashboard transformed his relationship with his company finances. For the first time, he could see his corporation tax liability in real time — meaning no year-end surprises. Quarterly planning calls with Forti ensured that dividend timing and salary levels were always optimised before deadlines, not after them.
Ciarán’s Take
“I put off contracting for two years because I thought the admin would be overwhelming.
Forti made it completely straightforward. I now earn significantly more, my pension is
growing faster than it ever did in permanent employment, and I have more control over
my working life. The free consultation was the best phone call I made in 2024.”
Optimising an Existing LTD: Aoife’s PSS Wake-Up Call
€8,400
PSS saved in year one
€750/day
Current day rate
€55,000
Pension contribution, year 1
Aoife is a Data Architect with fourteen years of experience, working primarily in the financial services and insurance sector. She has been contracting through her own limited company — Aoife Brennan Data Consulting Ltd — for six years, having made the transition from a permanent role in 2019 at a rate of €580 per day.
By early 2025, Aoife’s rate had grown to €750 per day and her company was generating approximately €165,000 in annual revenue. She had been using a general accounting practice for her annual returns and had assumed her affairs were in good order. A conversation with a fellow contractor at a Dublin tech meetup prompted her to reach out to Forti for a second opinion.
The Problem: An Avoidable Tax Leak
When Forti reviewed Aoife’s prior year accounts, three issues were immediately apparent.
Professional Services Surcharge: Aoife’s previous accountant had not structured her profit extraction to avoid the PSS. In the prior tax year, she had paid €8,400 in PSS that was entirely avoidable — money that should have gone into her pension fund instead.
Suboptimal salary level: She was drawing a salary of €60,000 — well above the efficient extraction level — pushing a significant portion of her income into the 40% tax band unnecessarily, when a lower salary combined with pension contributions and dividends would have been more efficient.
No employer PRSA in place: Despite the 2023 Finance Act changes removing BIK limits on employer PRSA contributions, her previous accountant had not set up an employer PRSA arrangement. Aoife had been making personal PRSA contributions from her after-tax salary — by far the least efficient route.
THE COST OF REACTIVE ACCOUNTING
In Aoife’s case, the combination of avoidable PSS, suboptimal salary extraction,
and the absence of an employer PRSA arrangement meant she had effectively overpaid
— in unnecessary tax and foregone pension efficiency — by an estimated €18,000–€22,000
in a single year. This is not unusual. Many contractors with existing LTDs are in
the same position without realising it.
The Solution: Restructure, PRSA Setup, and Ongoing Planning
Forti took over Aoife’s company accounting from the beginning of her new financial year. The restructuring involved several immediate changes:
Salary reduced to €42,000: efficiently uses personal credits and stays within the standard rate band
Employer PRSA established: Aoife’s company now makes annual employer PRSA contributions of €55,000 — zero BIK, fully CT-deductible
PSS exposure eliminated: with profits correctly routed through salary and pension, retained undistributed income is now managed below the level at which the surcharge becomes significant
Xero migration: Aoife’s bookkeeping moved to real-time Xero cloud accounting — giving her live visibility on VAT position, director loan account, and CT liability at all times
ERR compliance activated: all expense payments, including her monthly home office allowance and client travel, are now reported in real time in compliance with 2024 Revenue ERR rules
Quarterly review calls: Forti conducts a structured Q4 planning session each October to optimise year-end extraction before the company’s financial year closes
Results: Year One with Forti
Metric
Outcome
Gross company revenue (220 days @ €750)
€165,000
Director salary (tax-efficient level)
€42,000
Net salary after tax
~€34,100
Employer PRSA contribution
+€55,000
Corporation tax on remaining profit
~€7,100
PSS surcharge
€0 — eliminated vs. €8,400 prior year
Total wealth created (cash + pension)
~€89,100
Improvement vs. prior accountant setup
+€26,000 in year one
Cumulative pension fund (after restructure)
€142,000 and growing
Aoife’s case is a reminder that having a limited company is only the starting point. The real wealth-building potential of an IT contractor LTD is unlocked through ongoing, proactive tax planning — not annual compliance filing.
10 Questions IT Contractors Ask Forti Most
Should I use an umbrella company or set up my own limited company?
For contractors earning consistently above €80,000–€100,000 per year, a Personal Limited Company almost always delivers significantly better financial outcomes. The umbrella route taxes your income at the same marginal PAYE rates as a permanent employee — up to 52% — with no opportunity to retain profits at the 12.5% corporation tax rate or make tax-efficient employer pension contributions. The umbrella does retain Class A PRSI (useful for Jobseeker’s Benefit between contracts), which is a genuine benefit for early-stage or intermittent contractors. If you are testing contracting for the first time or taking a single short-term contract, umbrella can be a practical starting point. But for anyone planning to contract consistently for more than 12 months at market IT rates, the limited company is almost always the right structure.
How much does it cost to set up a limited company in Ireland?
Incorporating a private limited company through the Companies Registration Office (CRO) costs €50 online. In practice, your accountant will typically handle the incorporation as part of their onboarding — Forti includes company formation, VAT registration, PAYE employer registration, and Xero setup within the initial onboarding process. There is no additional charge for setup beyond the standard CRO filing fee. The ongoing cost is your monthly accountancy fee — Forti’s full-service LTD management starts from €195 per month plus VAT, which covers VAT returns, payroll, bookkeeping, ERR compliance, year-end accounts, and corporation tax return.
What is the Professional Services Surcharge and do I need to worry about it?
The Professional Services Surcharge (PSS) is a 15% charge applied to 50% of a company’s undistributed professional service income in a given accounting year (Section 441 TCA 1997). It exists to prevent contractors from accumulating profits inside their company and deferring personal tax indefinitely. For a company retaining €60,000 of undistributed profit, the surcharge could add approximately €4,500 on top of the corporation tax already paid. The good news is that the PSS is entirely avoidable with proper planning. By extracting a reasonable salary, making employer PRSA contributions, and timing dividend payments before year-end, virtually all IT contractors working with Forti pay zero PSS. The surcharge is not inevitable — it is a penalty for lack of planning.
Can my limited company make pension contributions on my behalf without it being taxed as income?
Yes — and this is one of the most powerful wealth-building tools available to Irish IT contractors. Since the Finance Act 2023, employer contributions to an employee’s PRSA are no longer subject to the historical Benefit in Kind caps that previously limited their usefulness. Your limited company can now make employer PRSA contributions of any amount. These contributions are: (1) fully deductible against your company’s corporation tax liability at 12.5%; (2) not treated as a benefit in kind on you as the employee or director — so no income tax, USC, or PRSI arises; and (3) invested tax-free within the pension fund until retirement. For a contractor billing €143,000 per year, directing €40,000–€55,000 annually into a PRSA through the company is both legal and highly efficient. Over a 10-year contracting career, this builds a substantial pension fund — far exceeding what would be achievable through personal pension contributions from after-tax salary.
What is the Karshan case and does it affect my contracting status?
The Karshan (Midlands) Ltd v Revenue Commissioners case (Irish Supreme Court, 2023) is the leading Irish authority on distinguishing genuine self-employment from disguised employment. The court affirmed a five-step test — covering mutual obligation, right of substitution, control, integration, and economic reality — that Revenue will apply when assessing whether a contractor is truly independent or effectively an employee of their client. For IT contractors, the risk of reclassification as an employee is real — and the consequences are severe: back-payment of PAYE, USC, and PRSI with interest and penalties. The key practical steps to protect your status include: ensuring your contract does not contain mutual obligation clauses, retaining a right of substitution, supplying your own equipment, maintaining professional indemnity insurance, billing through your company (not as an individual), and working for more than one client where possible. Forti reviews client contracts against the Karshan framework as part of our onboarding process.
Do I need to charge VAT as an IT contractor in Ireland?
If your annual turnover from IT services exceeds €40,000 (the current registration threshold for services), you are legally required to register for VAT in Ireland. Most IT contractors register voluntarily from day one even if below the threshold, because VAT-registered clients can reclaim the VAT you charge — meaning it is not a cost to them — and registration signals professionalism. The standard VAT rate for IT services in Ireland is 23%. You collect VAT on invoices, submit bi-monthly VAT3 returns to Revenue, and pay over the net VAT collected. If your clients are EU-based businesses (outside Ireland), different rules apply under the EU reverse-charge mechanism — your Forti accountant will ensure your invoices are structured correctly for each client arrangement.
How do I pay myself from my limited company in the most tax-efficient way?
The most tax-efficient extraction strategy for most IT contractor LTDs in 2026 combines three elements: (1) Director salary of approximately €42,000 — this uses your personal income tax credits and standard rate band efficiently without pushing large amounts into the 40% bracket; (2) Employer PRSA contributions — use the post-2023 Finance Act rules to route as much as commercially reasonable into a PRSA before extracting further cash; (3) Dividends — once salary and pension are optimised, remaining profits can be extracted as dividends, subject to Dividend Withholding Tax (DWT) at 25% unless you are able to claim an exemption. The precise optimal mix depends on your personal circumstances, the company’s profit level, and your other income sources. Forti models this individually for each client at our quarterly review sessions.
What business expenses can I deduct through my limited company?
Allowable expenses must be incurred wholly, exclusively, and necessarily for the purposes of your trade. For IT contractors, this typically includes: professional indemnity and public liability insurance; hardware (laptop, monitor, keyboard — claimed via capital allowances at 12.5% per annum over 8 years); business software and SaaS subscriptions; travel to client sites (not home to a fixed office — civil service mileage rates apply); a portion of home utility costs if you work from home (either the Revenue flat rate or a vouched apportionment); relevant professional development and training courses; and accountancy and legal fees. Items that are not deductible include: client entertainment and meals; commuting from home to a regular fixed place of work; and any expense with a personal as well as business element where the business purpose is not the primary driver. Since 2024, ERR rules also require that certain expense reimbursements to directors are reported to Revenue in real time — Forti handles this automatically.
What happens to my limited company if I take a break between contracts or return to permanent employment?
Your limited company continues to exist as a legal entity regardless of whether it is actively trading. If you take a gap between contracts — whether a planned career break, extended holiday, or period of personal leave — the company simply has no income during that period. Compliance obligations (annual return to the CRO, corporation tax return) still apply even for a dormant or low-activity period. If you return to permanent employment, you have several options: keep the company dormant (useful if you plan to contract again in future), voluntarily strike the company off the register if you are certain you will not use it again, or — if the company has retained profits — continue to extract them in a tax-efficient manner even while employed elsewhere. Forti advises clients on the most appropriate approach for their individual situation. Importantly, a gap between contracts does not affect the validity of your LTD structure or create any automatic Revenue compliance issue.
How do I find the right accountant for my IT contractor limited company — and what should I expect to pay?
The right accountant for an IT contractor LTD is one who: (a) specialises in the contractor and technology sector and understands the nuances of employment status, PSS, and PRSA planning; (b) uses cloud-based accounting (Xero or equivalent) for real-time visibility; (c) handles ERR compliance as standard rather than as an add-on; (d) offers proactive quarterly planning rather than purely reactive year-end filing; and (e) charges a transparent, all-inclusive monthly fee. In Ireland, full-service IT contractor LTD accounting ranges from approximately €150 to €250+ per month plus VAT. Be wary of very low-cost providers who may not include ERR compliance, VAT filing, or year-end accounts in their headline price. Forti Accountants charges from €195 per month plus VAT — fully inclusive of VAT returns, payroll, Xero bookkeeping, ERR reporting, annual financial statements, and corporation tax return, with proactive tax planning included as standard. We offer a free initial consultation with no obligation. Book at www.forti.ie.
Ireland has become one of the most strategically important jurisdictions in Europe for company formation. Its 12.5% Corporation Tax rate, English-language legal system, common law framework, EU membership, and deep talent pool in technology and financial services make it the jurisdiction of choice for thousands of international founders and established businesses every year.
What many people do not realise is that you do not need to be in Ireland to form anIrish company. The entire process — from name registration to Revenue setup to operational accounting — can be completed remotely, typically within 10–14 business days, by engaging an Irish-based accountant with specialist formation expertise.
Why Ireland? The Case for an Irish Entity in 2026
12.5%
Corporation Tax on profits
27
EU member states — full access
#1
EU ease of doing business
English
Only English-language EU common law jurisdiction
The strategic advantages of an Irish company
EU market access: An Irish-registered company is a full EU entity, entitled to trade freely across all 27 EU member states, access EU funding, and bid for EU public procurement contracts.
12.5% Corporation Tax: Ireland’s headline CT rate is one of the lowest in the developed world and applies to trading profits generated by Irish-resident companies.
English-language legal system: Ireland operates under common law — familiar to UK, US, Australian, and Canadian founders — with all company law and contracts conducted in English.
Double taxation treaties: Ireland has treaties covering 76 countries, reducing withholding tax on dividends, interest, and royalties.
R&D tax credits: A 25% R&D tax credit on qualifying expenditure — accessible to technology companies from day one.
Established ecosystem: Ireland hosts European HQs of Google, Meta, Apple, LinkedIn, Stripe, and hundreds of other technology firms.
POST-BREXIT NOTE FOR UK BUSINESSES
Since January 2021, UK-registered companies no longer have automatic access to the EU single market. An Irish subsidiary provides UK businesses with a compliant EU legal entity — enabling continued EU trading relationships, EU regulatory compliance, and access to EU clients who require an in-EU counterparty.
Who This Guide Is For — and What Each Audience Needs to Know
Remote Irish company formation requirements differ significantly depending on who you are and where you are based. Here is what each of the four primary audiences needs to know.
Non-Irish founders seeking an EU base
Founders based in the US, Middle East, Asia, or non-EU Europe who want an EU-registered entity to access EU markets, customers, or regulatory status.
Key need: EEA director solution (Section 137 bond or nominee), registered Irish address, and Revenue setup for VAT on EU transactions.
UK businesses post-Brexit
UK companies establishing an Irish subsidiary to maintain EU trading relationships, hold EU regulatory licences, or serve EU clients who require an in-EU counterparty.
Intercompany agreement between UK parent and Irish subsidiary governs the commercial relationship — Forti provides a standard template
Transfer pricing rules apply — intercompany transactions must be on arm’s-length terms and documented
Your Irish subsidiary files annual Irish accounts and a Corporation Tax return independently of your UK filings
Irish citizens living abroad who want to set up an Irish company — often to provide services to Irish clients or establish a business before returning home.
PPSN confirmation required — Forti verifies this is still active before filing
Registered address provided if no Irish home address
As an Irish citizen you are EEA-resident regardless of where you live — no Section 137 bond required if you are the sole director
International companies — Irish subsidiary
Established businesses outside Ireland forming a subsidiary for European operations, IP holding, or EU regulatory compliance.
Corporate director arrangements may be applicable — Forti advises on configuration
Intercompany structure and transfer pricing documentation required
Alignment with parent entity’s group reporting — Forti coordinates with your group accountants
The Legal Requirements — What Irish Law Actually Demands
The Companies Act 2014 governs all aspects of Irish company law. For a standard Private Limited Company (LTD), the requirements for remote formation are as follows:
Requirement
Detail
If you don’t meet it
Minimum one director
Any individual aged 18+ — no nationality restriction
N/A — always met by the founder
EEA-resident director
At least one director ordinarily resident in EEA
Section 137 bond or nominee director
Company secretary
Any person or body corporate — can be the sole director in some structures
Forti can act as company secretary
Registered Irish address
Physical address — not a PO Box — for CRO correspondence
Forti provides at €450/year + VAT
Share capital
No minimum — typically €1 issued share capital
N/A
Constitution
Written document setting out the company’s rules
Forti drafts this on your behalf
Annual Return (CRO)
Filed annually — first due within 6 months of incorporation
Late fees and eventual strike-off
RBO registration
Beneficial owners registered within 5 months of incorporation
Criminal offence — Forti handles as standard
Corporation Tax return
CT1 filed within 9 months of financial year-end
Interest and surcharges on late filing
IMPORTANT: THE BENEFICIAL OWNERSHIP REGISTER (RBO)
Ireland’s Register of Beneficial Owners requires all Irish companies to register details of individuals who ultimately own or control more than 25% of the company. This is a legal obligation separate from the CRO filing. Forti handles RBO registration as part of the formation process. Failure to register is a criminal offence.
The Remote Formation Process — Step by Step
Here is the complete remote formation process as managed by Forti — from your first enquiry to a fully operational Irish company.
1. Free consultation — Day 0
A 30–45 minute video or phone call to understand your situation: business type, country of residence, revenue model, client base, and whether any specialist requirements apply (EEA director, bond, subsidiary structure, group intercompany). No cost, no commitment.
2. Secure information collection — Day 1
Forti sends a secure digital onboarding form. You provide: full legal name, date of birth, home address, nationality, PPSN or foreign tax identifier, preferred company name options, and intended business activity. Approximately 10–15 minutes.
3. Identity verification — Day 1–2
Forti conducts AML due diligence — a regulatory requirement for all formation agents. You provide a copy of your photo ID and proof of address (utility bill or bank statement dated within three months). All verification is handled digitally.
4. Name check and Constitution drafting — Day 2
Forti checks your preferred company name against the CRO register for conflicts and restricted words. The Constitution is drafted and prepared for your electronic review and signature.
5. Form A1 filing with the CRO — Day 2–3
Forti files Form A1 electronically via the CRO’s CORE system. Standard processing: 3–5 business days. Expedited (same-day) processing available for an additional €50 CRO fee.
6. Certificate of Incorporation issued — Day 5–8
The CRO issues your Certificate of Incorporation with your Company Registration Number (CRN). Forti sends it to you immediately in digital and physical format.
7. RBO registration — Day 6–8
Forti registers your company’s beneficial owners with the Central Register of Beneficial Ownership. This is a separate filing from the CRO and is a legal obligation. Handled by Forti as standard.
8. Revenue registrations — Day 8–12
Using your CRN, Forti registers the company with Revenue for: Corporation Tax, VAT (mandatory above €40,000 annual turnover for services), and Employer PAYE. Revenue issues your Tax Reference Number and VAT number.
9. Banking, accounting and payroll setup — Week 2
Forti provides a bank referral pack for your business account application. Xero cloud accounting is set up with automated bank feeds. Payroll is configured. Your first invoice template is provided.
10. You trade — Forti manages everything else
From this point Forti handles all ongoing compliance: bi-monthly VAT returns, monthly payroll, Annual Return to CRO, year-end financial statements, and Corporation Tax return — with quarterly planning calls included.
WHAT YOU DO IN THIS ENTIRE PROCESS
Complete one online form (10–15 minutes). Upload two documents (photo ID and proof of address). Sign two documents electronically (Constitution and director consent). Attend one onboarding video call (30–45 minutes). That is it. Every other step is handled by Forti.
Case Studies: Three Remote Formation Stories
The following case studies are based on composite profiles from Forti’s remote formation client base. Names and details have been fictionalised. Financial outcomes are realistic representations under current Irish Revenue rules.
Case Study 01 · UK Business Post-Brexit
Meridian Digital — London-based SaaS company establishing an Irish EU subsidiary
18 days
First call to trading
€420k
EU revenue in year one
3
EU enterprise clients onboarded
Background
Meridian Digital is a London-headquartered SaaS company with 28 employees providing compliance workflow software to financial services firms. Following Brexit, two of their largest EU prospects declined to proceed to contract without an EU-registered counterparty. Their legal team recommended establishing an Irish subsidiary as the fastest and most cost-effective route.
Meridian’s CFO contacted Forti after a recommendation from their London accountant, who did not have Irish formation expertise. The key requirements were: establish the Irish subsidiary quickly, ensure proper intercompany documentation, and have a compliant accounting structure in place before the first EU invoice was issued.
What Forti handled
Incorporated Meridian Digital Ireland Ltd — CRN issued within 5 business days
Registered for Corporation Tax and VAT with Revenue
Drafted an intercompany services agreement between the UK parent and Irish subsidiary governing software licensing fees and management charges
Provided guidance on transfer pricing requirements — ensuring intercompany transactions were on arm’s-length terms and documented
Set up Xero for the Irish entity with a separate chart of accounts from the UK parent
Advised on VAT treatment of software services supplied to EU business clients including correct application of the reverse charge mechanism
COMPLEXITY RESOLVED: TRANSFER PRICING
The UK parent charged the Irish subsidiary a licensing fee for use of the software platform. Forti advised that this fee must reflect the arm’s-length value of the licence and must be documented in a formal transfer pricing policy. This was prepared as part of the formation engagement, ensuring Revenue compliance from day one.
Results
Metric
Outcome
Time from first call to first EU invoice issued
18 business days
EU enterprise clients onboarded in year one
3 (previously blocked by lack of EU entity)
Irish subsidiary year-one revenue
€420,000
Corporation Tax paid by Irish entity
€28,500 (12.5% on trading profit)
Revenue compliance issues
None
“We’d been stalling on EU expansion for 18 months because of the counterparty issue. Forti had the Irish entity operational in under three weeks, with proper intercompany documentation that our legal team approved. It unblocked two significant contracts immediately.”
— CFO, Meridian Digital (anonymised), client since March 2025
Case Study 02 · Non-Irish Founder / EU Base
Priya — Indian-born product consultant, forming an Irish company from Dubai
12 days
Call to incorporated
€137k
Year-one company revenue
0
Trips to Ireland required
Background
Priya is a senior product strategy consultant based in Dubai, working with technology startups across MENA and Europe. She secured a 12-month contract with a Dublin-based startup — the client required her to invoice through an EU-registered entity. Priya had no prior connection to Ireland and no Irish address, bank account, or tax history.
Her primary concerns were: whether she could form the company without travelling to Ireland, how to handle the EEA director requirement as a non-EEA resident, and how long the process would take given her contract start date was six weeks away.
What Forti handled
Confirmed that a Section 137 bond was the appropriate EEA director solution — arranged entirely by Forti
Provided Forti’s registered address as the company’s registered office
Filed Form A1 — Certificate of Incorporation received in 4 business days
Opened a Wise Business account — completed remotely using the Certificate of Incorporation and Forti’s bank referral letter
Advised on the tax treatment of Priya’s UAE residence alongside her Irish company
THE CROSS-BORDER TAX CONSIDERATION
Priya’s situation involved two tax jurisdictions — the UAE (where she lives) and Ireland (where her company is registered). The Irish company pays Irish Corporation Tax at 12.5% on its profits. When Priya extracts salary or dividends, Irish payroll tax and DWT rules apply. Forti coordinated with Priya’s UAE tax adviser on the Ireland-UAE double taxation agreement.
Results
Metric
Outcome
Time from first call to Certificate of Incorporation
12 business days
Trips to Ireland required
0
Section 137 bond arranged
Yes — by Forti, before CRO filing
Year-one company revenue
€137,000
Corporation tax paid (Irish entity)
~€8,400
“I was genuinely surprised at how straightforward the process was. I assumed forming a company in a country I had never lived in would involve lawyers, notarised documents, and months of waiting. Forti handled everything in under two weeks.”
— Priya, Product Consultant, client since October 2025
Case Study 03 · Returning Irish Emigrant
Declan — Irish software architect, forming from Vancouver before returning home
9 days
Call to incorporated
€165k
Projected year-one revenue
€55k
PRSA pension contribution, year one
Background
Declan is a senior software architect from Cork who spent eight years working in Vancouver. In late 2025, he decided to return to Ireland and set up as an independent contractor. He had two Irish clients lined up at €750 per day and wanted the company set up and operational before he returned — so he could begin invoicing immediately on arrival.
Declan’s PPSN had not been used in eight years. He was not certain it was still active. He found Forti through a recommendation in an Irish expat online community.
What Forti handled
Verified Declan’s PPSN was still active with Revenue — it was, with no issues
Provided registered address until Declan established a permanent Irish address after his return
Filed Form A1 — Certificate of Incorporation issued in 4 business days
Registered for Corporation Tax, VAT, and Employer PAYE
Set up Xero and payroll — Declan had his first payslip within 10 days of incorporation
Modelled optimal extraction strategy — salary of €42,000 plus employer PRSA contribution of €55,000, eliminating PSS exposure
Provided a Karshan-compliant contract template for his two Irish clients
Results
Metric
Outcome
Time from first call to Certificate of Incorporation
9 business days
Projected year-one company revenue (220 days @ €750)
€165,000
Director salary (tax-efficient)
€42,000
Employer PRSA contribution
€55,000
PSS surcharge exposure
€0 — eliminated through planning
Company ready before Declan returned to Ireland
Yes — fully operational
“Having the company already up and running when I landed back in Ireland made an enormous difference. I hit the ground running — my first invoice went out in my first week back. Forti sorted everything while I was still in Canada.”
— Declan, Software Architect, client since January 2026
Fees and Timelines — What to Expect
Service
Fee
Notes
Company formation (CRO + all Revenue registrations)
€200 + VAT
One-off. Includes name search, A1, TR2, VAT, PAYE, RBO
CRO standard processing fee
€50
Paid to CRO directly — not a Forti charge
Expedited CRO processing (same-day)
€100 additional
Optional — Certificate within 24 hours of filing
Registered office address
€450/year + VAT
All correspondence scanned and forwarded digitally
Section 137 bond (non-EEA directors)
~€1,500–€2,000/yr
Forti arranges — renewed annually
Nominee EEA director (if preferred)
At cost — third party
Forti refers to regulated provider
Intercompany agreement (UK subsidiary)
Included in formation
Standard template — legal review by client’s solicitor recommended
TYPICAL TOTAL COST — YEAR ONE FOR A NON-EEA REMOTE FORMATION
Formation fee €200 + VAT, registered address €450 + VAT, Section 137 bond ~€1,750, monthly management €195 × 12 = €2,340 + VAT. Total year-one cost approximately €4,740 + VAT — for a fully compliant, professionally managed Irish limited company.
12 Frequently Asked Questions
Can I really form an Irish company without ever visiting Ireland?
Yes — completely. The entire process is handled digitally. You provide identity documents and sign electronically. Forti files all CRO and Revenue documents on your behalf. There is no requirement to attend any office, notarise documents in person, or be physically present in Ireland at any stage. Forti has completed formations for clients in over 20 countries without a single in-person meeting.
I’m based in the UK — do I need a Section 137 bond or a nominee director?
Since Brexit, UK residents are no longer considered EEA-resident for the purposes of Irish company law. If you are the sole director of your Irish company and ordinarily resident in the UK, you will need either a Section 137 bond (a €25,000 insurance bond, typically costing €1,500–€2,000 per year, arranged by Forti) or a nominee EEA director. For most UK founders, the Section 137 bond is the simpler and more common solution — it involves no third party having any role in your company and is renewed annually.
Does my Irish company need to have Irish employees or operations?
No — not for formation. An Irish company can be incorporated and maintained with no Irish-based employees. However, for the company to be tax-resident in Ireland (and thus benefit from the 12.5% CT rate), Revenue requires that the company is managed and controlled from Ireland. This is a substance test — key decisions about the company must be made in Ireland. Forti advises on how to meet this test, which typically involves documenting strategic decisions as having been made in Ireland.
What is the difference between the CRO and Revenue — and why register with both?
The Companies Registration Office (CRO) is the body that legally creates your company and issues your Company Registration Number. Revenue Commissioners is the Irish tax authority — responsible for Corporation Tax, VAT, and PAYE. You must register separately with Revenue to obtain a tax reference number, VAT number, and employer registration. These are two completely separate registrations. Forti handles both as part of the formation process, sequentially, within a single engagement.
Can a non-Irish company be a director of an Irish company?
Yes. A corporate entity can be appointed as a director of an Irish company — common for international subsidiaries where the parent company is a director of the Irish entity. However, at least one director must still be an individual (not a corporate entity), and the EEA residency requirement still applies to individual directors. Forti advises on the appropriate director configuration during the initial consultation.
How does VAT work for an Irish company billing international clients?
VAT treatment depends on who your client is and where they are based. Irish clients: charge Irish VAT at 23% for most services. EU business clients (B2B): the EU reverse charge mechanism applies — you invoice without Irish VAT. EU consumer clients (B2C): the One Stop Shop (OSS) scheme may apply. UK clients (post-Brexit): reverse charge typically applies for B2B services. Non-EU international clients: generally outside the scope of Irish VAT. Forti ensures your invoice templates are configured correctly for your specific client mix.
Can I open an Irish business bank account remotely?
Yes. The most practical options in 2026 are: Revolut Business — fully remote account opening, excellent for international transactions; Wise Business — remote opening, multi-currency, ideal for companies billing in multiple currencies; AIB/Bank of Ireland — possible remotely with Forti’s bank referral letter, though may require a video verification call. Forti provides a bank referral letter and full documentation pack for all newly formed companies, which significantly accelerates the account opening process.
What is the Beneficial Ownership Register (RBO) and must I register?
Yes — registration is a legal requirement. Every Irish company must register the details of its beneficial owners — individuals who ultimately own or control more than 25% of the company. Failure to register within five months of incorporation is a criminal offence. Forti registers your company with the RBO as a standard part of the formation process and manages the annual confirmation of beneficial ownership details thereafter.
I already have a company in another country. Can I use it as the basis for an Irish entity?
You cannot transfer an existing foreign company into the Irish register — an Irish company must be newly incorporated under Irish law. However, your existing foreign company can be the shareholder (and potentially a director) of the new Irish company, creating a parent-subsidiary structure. This is the standard approach for international businesses establishing an Irish subsidiary. Forti advises on the appropriate corporate structure, intercompany arrangements, and transfer pricing obligations.
How long does the whole process take?
In standard cases: CRO processing takes 3–5 business days after filing. Revenue registrations take a further 5–7 business days. Banking and accounting setup takes approximately 5 business days. Total: 10–14 business days from your first call to a fully operational company. Expedited CRO processing (same-day Certificate of Incorporation) is available for an additional €50 fee, reducing the timeline to approximately 8–10 business days. Non-standard formations requiring a Section 137 bond or corporate director arrangements may take 2–3 additional business days.
Do I need an Irish solicitor to form an Irish company?
No — not for a standard private limited company formation. A qualified accountant or formation agent such as Forti can handle all CRO and Revenue filings without a solicitor’s involvement. A solicitor may be advisable for: complex shareholder agreements between multiple founders; regulatory licence applications; or significant property, IP, or asset transactions associated with the company. For the vast majority of remote formations, Forti handles everything without the need for a solicitor.
What ongoing support does Forti provide after the company is formed?
Forti’s formation engagement is the beginning of an ongoing professional relationship. After formation, Forti provides: monthly payroll processing; bi-monthly VAT return preparation and filing; real-time Xero cloud bookkeeping with automated bank feeds; Enhanced Reporting Requirements (ERR) compliance; Annual Return preparation and CRO filing; year-end financial statements; Corporation Tax return (CT1); quarterly review calls covering salary optimisation, pension strategy, and dividend timing; and proactive alerts on regulatory changes. All covered under a single transparent monthly fee from €195 + VAT.
Introduction: Your Finances Are Either a Brake or an Accelerator
Here is a question worth sitting with: When you last spoke to your accountant, were you talking about the past or the future?
If the answer is the past, you are not alone. The majority of Irish SMEs engage with their accountant primarily at year-end, producing accounts that tell the story of what already happened. The books get filed, the tax gets paid, and everyone moves on. Until next year.
But the most competitive Irish businesses are doing something fundamentally different. They are treating their finance function not as an administrative obligation, but as the engine room of their growth strategy. They are using real-time data, strategic forecasting, and outsourced CFO expertise to make faster, better decisions than their competitors.
This blog post is for the ambitious Irish business owner who suspects there is more value in their numbers than they are currently extracting. Whether you are a two-person startup in Dublin or a 50-person scale-up in Cork, the principles are the same: strategic accountancy, done properly, does not just keep you compliant. It makes you grow faster.
At Forti Accountants, we have seen this transformation up close. In the pages that follow, we will walk you through exactly how it works.
Section 1: Company Formation — The Decisions Made on Day One That Echo for a Decade
Most founders treat company formation as a box to tick. Register with the CRO, set up a bank account, get a tax number, and get on with it. This is understandable. In the early days, your energy belongs in winning customers, not navigating corporate structure.
But the decisions made at formation — share structure, directorship, holding company architecture, pension arrangements, and tax residency — are not cosmetic. They are the load-bearing walls of your entire financial future. Getting them wrong is expensive. Getting them right is a compounding advantage.
Share Structure: More Than a Legal Formality
How shares are split between founders and early employees sends signals to future investors, creates legal obligations during exits, and determines how value is distributed when the business succeeds. A poorly constructed share structure can create deadlock, complicate fundraising rounds, and generate unexpected Capital Gains Tax exposure for founders who were never properly advised.
At Forti, we routinely work with founders who arrive having issued shares with no vesting schedule, no shareholder agreement, and no tax-efficient structure in place. Unwinding that at Series A is painful and expensive.
Holding Companies and Group Structures
For businesses with real ambition, establishing a group structure early — a holding company with an operating subsidiary — can provide enormous tax efficiency. Dividends can be paid up to the holdco tax-free. Property assets can be held at the holdco level, shielded from trading risk. Intellectual property can be developed in a tax-advantaged structure. None of this is available to the sole trader or the single-entity limited company.
The cost of setting up the right structure at day one is a fraction of the cost of restructuring later. More importantly, the right structure creates options. And in business, options are everything.
Personal Tax Planning from the Outset
Irish entrepreneur relief, pension contributions through the company, and director salary-versus-dividend planning are all tools that must be considered from the start. A founder who takes a modest salary and draws dividends efficiently can retain significantly more personal wealth than one who takes all income as salary and pays the higher rate of PAYE.
The bottom line: Treat company formation as a strategic exercise, not an administrative one. The structure you choose today is the foundation upon which everything else is built.
Case Study A | The Tech Startup: Lumi Analytics
Year 1 — Two former fintech employees, Ciara and Donal,
incorporated Lumi Analytics in 2021 with Forti Accountants’ support.
Rather than a standard 50/50 share split, we structured a vesting
schedule with a one-year cliff and three-year vest, protecting both
founders. We set up a group structure from day one, with IP held at
holdco level.
Outcome: When Lumi raised a €1.2m seed round eighteen
months later, their cap table was clean, their IP was protected, and
investor due diligence took three weeks rather than three months.
Their lead investor specifically cited the quality of their financial
governance as a differentiator.
Section 2: Bookkeeping and Tech Stack — From Receipts in a Shoebox to Real-Time Intelligence
Let us be blunt about something. If your bookkeeping system consists of a spreadsheet, a folder of email receipts, and a quarterly call with your accountant, you do not have a finance function. You have a time bomb.
The move from manual bookkeeping to cloud-based, real-time accounting is one of the highest-ROI upgrades an Irish business can make. Not because of the software itself, but because of the data and decisions it unlocks.
The Modern Accounting Tech Stack
The leading cloud accounting platforms available to Irish businesses include Xero, QuickBooks Online, and Sage Business Cloud. At Forti, we primarily work with Xero, which we regard as best-in-class for growing Irish SMEs. When integrated with the right tools, it creates a genuinely powerful financial intelligence system:
Xero —
Core ledger, invoicing, bank feeds, payroll integration, and VAT returns. Real-time bank reconciliation means your books are always current.
Dext (formerly Receipt Bank) —
Employees photograph receipts on their phone. Dext extracts the data using OCR, categorises it, and pushes it directly into Xero. The shoebox is dead.
HubDoc —
Fetches supplier invoices and bank statements automatically, eliminating manual document collection.
Stripe / GoCardless Integration —
For SaaS and subscription businesses, revenue recognition can be automated, removing hours of manual reconciliation.
Spotlight Reporting or Fathom —
Beautiful, client-ready management accounts and dashboards that translate your Xero data into strategic insight.
From Backward-Looking to Forward-Looking
Here is the real shift. When your books are maintained in real-time, you stop looking backward and start looking forward. You know your current cash position not at month-end, but today. You can see exactly which clients owe you money and when it is due. You can compare actuals versus budget in real time. You can model the impact of hiring a new employee before you make the offer.
This is not theoretical. This is how fast-growing Irish businesses make decisions that their slower competitors cannot. Speed of insight equals speed of action.
The ROI of Clean Books
Consider a business turning over €2m per year. Poor bookkeeping typically costs that business in several ways:
Late invoicing and poor debtor management: conservative estimate of €40,000 to €80,000 tied up in outstanding receivables at any given time.
VAT overclaims or underclaims: potential penalties and interest running into thousands of euro.
Missed tax reliefs and allowances: Irish businesses routinely miss R&D tax credits, capital allowances, and section 481 film relief because they lack the data visibility to identify them.
Poor cash flow management: leading to unnecessary overdraft fees or missed investment opportunities.
The cost of a well-managed outsourced bookkeeping solution is a fraction of these losses. At Forti, our bookkeeping clients typically find that the service pays for itself within the first quarter.
Case Study A | Lumi Analytics — Continued
Year 2 — With Forti managing their books on Xero with
Dext integration, Lumi’s founders had real-time visibility into their
monthly recurring revenue, churn rate, and runway. When a major client
threatened to delay payment by 90 days, Ciara spotted it in her Xero
dashboard within 48 hours and proactively renegotiated terms — avoiding
a cash crunch that could have been fatal at their stage.
Outcome: Clean, real-time data gave Lumi the confidence
to invest in two additional engineers six weeks ahead of schedule,
accelerating their product roadmap and enabling them to close two
enterprise contracts before a competitor could.
Section 3: The VAT Trap — How Mismanaging VAT Pushes Business Owners to the Wall
If there is one area of Irish business tax that causes disproportionate damage to otherwise healthy companies, it is VAT. Not because VAT is uniquely complicated, but because the penalties for getting it wrong are severe, swift, and unforgiving.
And unlike income tax, which is assessed annually, VAT is a recurring obligation. Get it wrong twice a year, every year, and the damage compounds.
How VAT Works in Ireland — A Quick Refresher
Irish VAT-registered businesses collect VAT on their sales (output VAT) and reclaim VAT on their purchases (input VAT). The difference is remitted to Revenue. For most businesses, VAT returns are filed bi-monthly. Larger businesses may file monthly; smaller businesses may qualify for annual returns.
The standard VAT rate in Ireland is 23%, with reduced rates of 13.5% (applicable to construction, certain hospitality services, and energy) and 9% (certain tourism and hospitality activities). Getting the rate wrong is not just a technical error. It is a liability.
The Cost of Getting VAT Wrong
Missing the filing deadline (currently the 19th of the month following the end of the VAT period) results in an immediate surcharge. Revenue applies a surcharge of 5% on the VAT due for late returns, up to a maximum of €12,695 per return. If you miss two returns in a year, you could be facing a €25,000 bill before penalties and interest are even calculated.
Underpayment of VAT exposes you to interest charges of 0.0219% per day — which sounds small until you calculate it on a €50,000 underpayment over 18 months. The number becomes €7,200 in interest alone, on top of the original liability.Revenue VAT audits are not random. They are triggered by anomalies: VAT ratios that do not match industry norms, irregular return patterns, or tip-offs. A VAT audit is not a conversation you want to have when your books are in disarray. Revenue can go back four years in a standard audit, and they frequently do.
The Cash Flow Dimension
Here is the dimension that catches business owners off guard. VAT is not your money. The moment you raise an invoice inclusive of VAT, that VAT portion belongs to Revenue. It is being held in trust. But it sits in your bank account. Many business owners — particularly in cash-hungry early stages — spend it.
When the VAT return comes due, the money is not there. They cannot pay. Revenue adds surcharges. Cash flow tightens further. They defer the next VAT payment. The hole gets deeper. We have seen businesses with strong underlying revenues facing genuine insolvency because of a VAT spiral that began with a single missed payment.
⚠️ Warning: The VAT Spiral — How It Escalates
Month 1: Business misses VAT deadline. 5% surcharge applied. €2,500 on a €50,000 bill.
Month 3: Unable to pay, business defers next return. Revenue initiates enforcement proceedings.
Month 5: Revenue appoints a sheriff to collect. Bank account garnished. Payroll at risk.
Month 6: Business owner approaches their bank for emergency credit. Bank reviews accounts and sees the Revenue debt. Declines.
Month 8: Business, which had revenues of €800,000 last year, is technically insolvent due to a €75,000 VAT liability that spiralled from a single missed deadline.
This is not a hypothetical. This is a pattern Forti Accountants has been called in to resolve. And in every case, the tragedy is that it was entirely preventable.
How Forti Accountants Keeps VAT Under Control
Our VAT management service covers:
Accurate and timely preparation of bi-monthly VAT returns using real-time Xero data.
VAT rate review to ensure you are applying the correct rates across all product and service lines.
Input VAT maximisation, ensuring you are claiming every allowable input credit.
Inter-company and cross-border VAT guidance for businesses trading with EU customers or suppliers post-Brexit.
Revenue Audit support, should your business ever be selected for review.
Clean VAT compliance is not just about avoiding penalties. It is a signal to your bank, your investors, and your future acquirers that your business is well-managed. It is a competitive advantage.
Case Study B | The Turnaround: Meridian Facilities Management
The Problem — In 2022, Declan O’Brien, founder of Meridian Facilities
Management, reached out to Forti Accountants in what he described as a state of controlled panic.
His €1.4m turnover cleaning and facilities business had accumulated €68,000 in VAT arrears
across four consecutive missed bi-monthly returns. Revenue had issued a demand. His bank was
reviewing his overdraft facility. He had four weeks of cash runway.
What had gone wrong? Declan had been doing his own bookkeeping on a spreadsheet.
His invoicing was inconsistent. He was mixing VAT-exclusive and VAT-inclusive pricing in different
contracts, underclaiming input VAT on materials, and had completely missed the two-tier VAT rate
applicable to some of his contracts. His last accountant had prepared year-end accounts but had
not been reviewing VAT returns.
The Forti Intervention — Within two weeks, our team had reconciled 18 months
of accounts, corrected the VAT position (finding that Meridian had actually been overclaiming
in certain categories), entered into a phased payment arrangement with Revenue, and migrated
Declan’s books entirely to Xero with Dext.
Outcome: Meridian avoided insolvency. The Revenue arrangement reduced the
immediate liability pressure. Within six months, Declan’s books were clean, his cash flow
was predictable, and he was able to approach his bank for a €150,000 facility to fund
equipment for two new contracts.
Section 4: Strategic CFO Services — From Compliance to Competitive Advantage
There is a point in every growing business when the finance function needs to evolve. The question is not whether you need strategic financial leadership. The question is when, and at what cost.
A full-time CFO in Ireland typically commands a salary of between €100,000 and €180,000 per annum, plus benefits and equity. For most Irish SMEs and scale-ups, that is not feasible until revenues comfortably exceed €5m or €6m. But the decisions that require CFO-level thinking arrive long before the balance sheet can justify the hire.
This is precisely the gap that fractional and outsourced CFO services fill. At Forti, our strategic CFO offering gives growing businesses access to board-level financial expertise at a fraction of the cost of a full-time hire.
What a Strategic CFO Actually Does
It is worth distinguishing between what a bookkeeper does, what a compliance accountant does, and what a strategic CFO does. They are not interchangeable:
Bookkeeper:
Records what happened. Categorises transactions. Reconciles accounts.
Compliance Accountant:
Prepares statutory accounts. Files tax returns. Ensures you are meeting legal obligations.
Strategic CFO:
Determines what should happen next. Models scenarios. Identifies capital requirements. Advises on pricing, margin, and investment decisions. Prepares you for fundraising, acquisition, or exit.
The compliance function tells you where you have been. The strategic CFO function tells you where you are going and how to get there faster.
Key Deliverables of the Forti Strategic CFO Service
Financial Modelling and Forecasting
We build dynamic, rolling 12-month financial models that allow you to test strategic decisions before you make them. What happens to your runway if you hire two senior engineers? What is the revenue impact of moving from a one-time payment model to subscription? What is the minimum contract value you need to close this quarter to hit profitability? These are not questions you can answer with last year’s accounts.
Runway Analysis and Cash Flow Management
For funded startups and growing businesses, runway is survival. We maintain real-time visibility on your cash position, forecast future cash flows under multiple scenarios, and give you clear sight lines on when you need to raise, when you can invest, and when to conserve.
Businesses that understand their runway make better decisions. They do not under-hire when they can afford to scale and do not panic when a large debtor is slow. Clarity of cash position is a strategic asset.
Capital Allocation and Investment Decisions
Growth requires capital allocation decisions: which channel to invest in, whether to build or buy, whether to take on debt or dilute equity. These decisions have long-term consequences that go well beyond next quarter’s P&L. Our CFO team brings rigorous analysis to these decisions, stress-testing assumptions and modelling downside scenarios.
Investor Readiness and Fundraising Support
If you are planning to raise equity funding, the quality of your financial presentation is a direct signal of the quality of your management team. Investors and their due diligence advisors scrutinise financial models, management accounts, and board reporting packs. Forti prepares clients for fundraising the right way: clean books, robust models, clear investor narrative, and data rooms that do not raise red flags.
We have supported Irish businesses in raising funding from Enterprise Ireland, angel syndicates, and institutional VCs. In every case, the quality of financial governance has been a significant factor in investor confidence.
Board and Management Reporting
As your business grows, your stakeholders — co-founders, investors, board members, lenders — require clear, regular financial reporting. We produce professional monthly management accounts and board packs that give your stakeholders the information they need to fulfil their oversight role and support your decision-making.
Case Study A | Lumi Analytics — Continued
Year 3 — With Forti operating as their fractional CFO, Ciara and Donal began preparing for a Series A raise. Our team built a five-year financial model, prepared investor-ready management accounts for the preceding 24 months, and supported the preparation of a data room that addressed likely investor due diligence questions proactively.
We identified that Lumi’s revenue recognition methodology had an inconsistency that would have been flagged by any competent investor’s accountant during due diligence. We corrected it before it became a problem.
Outcome: Lumi closed a €4.2m Series A round in Q1 2024. The lead investor’s CFO commented that Lumi’s financial governance was among the strongest they had seen in an Irish seed-stage company. Valuation at close: €18m.
Case Study B | Meridian Facilities Management — Continued
Year 2 Post-Forti Engagement — With his books clean and his VAT in order, Declan was ready to think strategically for the first time. Our CFO team identified that Meridian’s most profitable contracts were in pharmaceutical and food manufacturing facilities — a segment requiring higher compliance standards but commanding 40% higher margins than commercial office cleaning.
We built a three-year growth model focused on sector specialisation, modelled the cost of obtaining ISO 14001 and ISO 45001 certification (a prerequisite for larger pharmaceutical contracts), and prepared a business case for a €300,000 bank facility to fund the certification process and equipment upgrade.
Outcome: Declan secured the facility in Q3 2024. By the end of 2025, Meridian had grown revenue from €1.4m to €2.9m, gross margin had improved from 28% to 41%, and the business was being approached by a trade buyer valuing it at €4.2m — a business that eighteen months earlier had nearly been wound up over a VAT spiral.
Section 5: The Full Picture — What Strategic Accountancy Looks Like in Practice
Let us bring this together. A business that engages with Forti Accountants across all dimensions of our service is not just compliant. It is operating with genuine competitive advantage.
Here is what that looks like in practice:
Formation:
The structure is right from day one. Shares are properly constituted. Tax efficiency is built in. The company is ready for investment.
Bookkeeping:
Real-time books mean real-time decisions. The finance function is not a lag indicator. It is a live dashboard.
VAT and Compliance:
Returns are filed on time, every time. Revenue relationships are clean. The business is never at risk of a compliance spiral.
Management Accounts:
Every month, the leadership team receives clear, professional accounts that translate the numbers into strategic insight.
Strategic CFO:
Board-level financial leadership at a fractional cost. Fundraising support. Capital allocation expertise. Runway visibility. A finance partner who is as invested in your growth as you are.
This is not a luxury reserved for large businesses. At Forti, we work with businesses at every stage of growth, and we design our service to scale with you. You do not need all of this on day one. But you need to know it is available when you need it.
Ready to Turn Your Finance Function Into a Growth Engine? Book Your Strategic Financial Review.
Most business owners know their numbers are not where they need to be. They know their bookkeeping is behind, their VAT returns are stressful, and they have never had a proper conversation about their financial strategy. They just have not had the time to deal with it.
Here is what we know from working with hundreds of Irish businesses: the cost of delay is always higher than the cost of action.
Forti Accountants is inviting ambitious Irish businesses to book a complimentary 45-minute Strategic Financial Review. This is not a sales call. It is a structured conversation about your business, your numbers, and your ambitions. By the end of it, you will have a clear picture of:
Where your finance function currently stands relative to best practice.
The specific risks and gaps in your current accounting setup.
The three or four highest-impact changes you could make right now.
How a partnership with Forti could accelerate your growth trajectory.
This offer is for you if:
You are turning over €500,000 or more and know your finance function has not kept pace with your growth.
You are planning to raise funding in the next 12 to 24 months and want your books investor-ready.
You have had VAT or compliance issues and want to make sure they never happen again.
You want a finance partner, not just an accountant who shows up at year-end.
The case studies referenced in this blog post are fictionalised composites based on real business scenarios. Any resemblance to specific individuals or companies is coincidental. All financial figures are illustrative. This blog post does not constitute financial or legal advice. Forti Accountants recommends that all businesses seek tailored professional advice appropriate to their specific circumstances.
The Amazon Opportunity — and Why Accounting Catches Sellers Out
Ireland has one of the fastest-growing cohorts of Amazon sellers in Western Europe. From cottage industry crafters selling handmade goods to entrepreneurs running six-figure private label operations from a home office in Leinster, the Amazon marketplace has opened up genuinely global distribution to Irish businesses of every size.
But there is a gap that catches almost every Amazon seller at some point: the gap between what Amazon pays you and what you actually owe Revenue. Amazon is extraordinarily good at getting your products in front of customers. It is not, however, your accountant, your tax adviser, or your compliance officer. The platform handles some VAT on your behalf in some markets — but the responsibility for your Irish income tax, your VAT registration obligations, your EU compliance, and your bookkeeping sits squarely with you.
The sellers who get into trouble are not usually the ones who are deliberately cutting corners. They are the ones who did not know what they did not know. This guide sets out to fix that.
EU law — Amazon reports your sales data to Revenue quarterly
How Amazon Income Is Taxed in Ireland
Every euro of profit you make from selling on Amazon is taxable income in Ireland. The way that income is taxed depends on your business structure — whether you operate as a sole trader or through alimited company. Most new Amazon sellers start as sole traders and many stay that way; some reach a point where incorporation makes financial sense. We cover the comparison in Section 8.
Sole Traders — Self-Assessment and Form 11
If you sell on Amazon as a sole trader, your Amazon profits are added to any other income you have (employment, rental, investments) and taxed under the self-assessment system. You must:
Register for income tax with Revenue if your non-PAYE income exceeds €5,000 net or €30,000 gross in a tax year
File an annual Form 11 tax return by 31 October each year for the previous tax year (extended to mid-November if filing and paying via ROS)
Pay Preliminary Tax for the current year at the same time — typically 100% of your previous year’s liability, or 90% of your estimated current year liability
Pay Class S PRSI at 4.2% on your net trading profits (with a minimum contribution of €500/year)
Pay USC on all income above €13,000 per year — in bands of 0.5%, 2%, 3%, and 8%
Your Amazon profit is not your Amazon turnover. It is your sales revenue less all allowable business expenses. See Section 7 for a full list of what you can claim. This distinction matters enormously — many sole trader Amazon sellers overpay tax because they do not claim all the expenses they are entitled to.
THE PRELIMINARY TAX TRAP
A common shock for first-year Amazon sellers: when your business takes off and you file your first Form 11, you may owe both your first year’s tax balance and preliminary tax for the current year simultaneously. On profits of €50,000, that combined bill can easily reach €25,000–€30,000.
The fix is straightforward but requires planning: set aside approximately 30–35% of your net Amazon profits into a separate tax savings account every month. Do not wait for October to calculate what you owe.
Income Tax Rates (2026)
Income Level
Rate
Notes
First €42,000 (single person)
20% income tax
Standard rate band — increases for married couples / civil partners
Above €42,000
40% income tax
Higher rate on all income above threshold
USC Band 1: €0–€12,012
0.5%
Universal Social Charge
USC Band 2: €12,013–€25,760
2%
USC Band 3: €25,761–€70,044
3%
USC Band 4: Above €70,044
8%
Class S PRSI (self-employed)
4.2%
Minimum €500/year; rises to 4.35% from Oct 2026
A sole trader Amazon seller making €60,000 net profit in 2026 faces an effective total tax rate (income tax + USC + PRSI) of approximately 42–45% on the income above the standard rate band. This is a significant cost, and it is one of the primary reasons established Amazon sellers consider incorporating.
Limited Companies — Corporation Tax
A limited company pays corporation tax at 12.5% on Irish trading profits — substantially lower than the top personal income tax rate of 40%. However, corporation tax is only one layer: getting money from the company into your personal pocket involves salary (PAYE), dividends, or a combination, each with its own tax implications. We cover this in Section 8.
VAT Registration — Your Irish Obligations
VAT is one of the most frequently misunderstood obligations for Irish Amazon sellers — and one of the most expensive to get wrong. There are two distinct layers to think about: your Irish VAT obligations (whether you need to register here) and your EU VAT obligations (whether you need to register or use OSS in other member states). This section covers the Irish side. Section 4 covers the EU picture.
When Must an Irish Amazon Seller Register for VAT?
In Ireland, VAT registration is mandatory when your taxable turnover exceeds the relevant threshold:
Supply Type
VAT Registration Threshold
Notes
Goods
€80,000 per year
Most Amazon sellers selling physical products fall here
Services
€40,000 per year
Applies if your primary supply is a service rather than goods
Both goods and services
Lower threshold applies
If you supply both, use the goods threshold if goods dominate
Once registered, you must charge Irish VAT at the appropriate rate (23% standard rate for most goods), file VAT returns (typically bi-monthly), and pay VAT to Revenue on time. You can also reclaim input VAT on business purchases — including stock, packaging, software, and professional fees.
DO NOT WAIT UNTIL YOU HIT THE THRESHOLD
Many Amazon sellers only register for VAT when they realise they have already exceeded the threshold. At that point, they owe VAT on all sales from the date they should have registered — not the date they actually did. Revenue can also charge interest and penalties on the under-declared VAT.
If your Amazon business is growing quickly, get a VAT adviser involved early. Registering voluntarily before you hit the threshold is often the right move — particularly because VAT registration lets you reclaim input VAT on stock and business costs from day one.
Some building materials, hospitality-related goods
9% (Second reduced)
Newspapers, certain sports facilities
Limited application for most Amazon sellers
0% (Zero-rated)
Children’s clothing/footwear, most food, books
Exempt but still reportable on VAT return
Can I Reclaim VAT on My Amazon Costs?
Yes — once VAT registered, you can reclaim the VAT element of allowable business expenses, including:
Stock purchases from VAT-registered Irish or EU suppliers (who issue valid VAT invoices)
Packaging, labelling, and fulfilment materials purchased in Ireland
Software subscriptions that have an Irish VAT element
Professional fees (accountant, solicitor, consultant) from Irish VAT-registered providers
Import VAT paid on goods brought into Ireland from outside the EU (via C79 certificate)
Amazon’s fees themselves (referral fees, FBA fees) are generally subject to a reverse charge mechanism rather than direct VAT — your accountant will handle this correctly on your VAT return.
EU VAT, One Stop Shop (OSS), and Amazon FBA
If you sell on Amazon to customers across Europe — or if you use Amazon’s Fulfilment by Amazon (FBA) service with stock stored in EU warehouses — you have EU VAT obligations that go well beyond your Irish registration. This is the area where Irish Amazon sellers are most frequently non-compliant, and where the financial exposure can be largest.
The EU-Wide Distance Selling Threshold
Since July 2021, a single EU-wide threshold of €10,000 applies to cross-border B2C (business to consumer) sales. If your total cross-border B2C sales to EU customers across all countries combined exceed €10,000 in a calendar year, you are required to either:
Register for the One Stop Shop (OSS) in your home EU member state (Ireland) and file quarterly OSS returns accounting for VAT in each destination country, OR
Register for VAT individually in each EU country where you have customers
For most Irish Amazon sellers selling B2C across Europe, OSS is the correct and most efficient route — one return, filed in Ireland, covering all EU member states. However, OSS is not a complete solution for all Amazon sellers.
OSS Does NOT Cover Everything — FBA Changes the Picture
The One Stop Shop scheme only applies to cross-border B2C sales. It does not cover:
Sales from locally-stored stock — if Amazon holds your inventory in a German warehouse and you sell to a German customer, that is a domestic German sale, not a cross-border sale. It falls outside OSS and requires a German VAT registration.
Intra-community stock transfers — when Amazon moves your goods between fulfilment centres in different EU countries, those movements are treated as self-supplies and must be reported locally.
B2B (business to business) sales — OSS only applies to B2C transactions.
Import VAT — on goods imported from outside the EU, separate IOSS rules or local import VAT procedures apply.
PAN-EU FBA SELLERS – CRITICAL CHANGE FROM JANUARY 2026
If you use Amazon’s Pan-European FBA (Pan-EU FBA)
programme, Amazon moves your stock between fulfilment centres in multiple
EU countries to optimise delivery times. From
1 January 2026, Pan-EU FBA requires VAT registration in a
minimum of five countries: Germany, France, Poland, Italy, and Spain.
Storing inventory in any EU country — even temporarily, even if Amazon moves
it there without your direct instruction — creates a
local VAT registration obligation in that country regardless
of your sales volume. Many Irish FBA sellers are currently non-compliant with
local VAT registrations in Germany, France, and Poland. Revenue authorities in
those countries are now actively cross-referencing Amazon’s DAC7 data against
their local VAT registration databases.
OSS Returns — Deadlines and Rates
If registered for OSS in Ireland, you file quarterly OSS returns through Revenue Online Service (ROS). Deadlines are:
Quarter
Period
Filing Deadline
Q1
January – March
30 April
Q2
April – June
31 July
Q3
July – September
31 October
Q4
October – December
31 January (following year)
Each OSS return must account for sales in each destination EU country at that country’s applicable VAT rate. VAT rates vary significantly across the EU — German standard VAT is 19%, French is 20%, Italian is 22%. Your accounting software or VAT service needs to apply the correct rate for each sale by destination country.
THE FIX
If you use FBA and sell across Europe, you almost certainly need specialist
eCommerce VAT advice. The OSS + local registration combination that most
Pan-EU FBA sellers require is not something a generalist accountant typically
handles. Forti.ie specialises in exactly this — contact us for a VAT position review.
DAC7 — Why Revenue Already Knows What You’re Earning
Here is something every Irish Amazon seller needs to understand: Revenue does not rely solely on self-reported income to know what you earn on Amazon. Since January 2024, Amazon has been legally required to report your earnings directly to EU tax authorities under the DAC7 Directive — and it has been doing so on a quarterly basis.
What Is DAC7?
DAC7 (Council Directive 2021/514) is EU legislation that requires digital marketplace operators — including Amazon, Etsy, eBay, and Airbnb — to collect and verify information about their sellers and report that information to the relevant national tax authorities each year. In Ireland, Amazon reports to Revenue. Revenue then exchanges data with other EU member states.In Ireland, the reporting threshold that triggers DAC7 inclusion is €2,000 in total consideration or 30 or more transactions in a reporting period. The vast majority of active Amazon sellers will exceed both thresholds.
What Information Does Amazon Share with Revenue?
Amazon provides Revenue with the following seller information each reporting year:
Your full legal name and business name
Your address and Tax Identification Number (Irish PPS number or company tax number)
Your total gross sales revenue for the year, broken down by quarter
The number of transactions you completed
Any fees deducted by Amazon (referral fees, FBA fees, etc.)
Details of bank accounts to which Amazon pays you
WHAT THIS MEANS IF YOU HAVE NOT FILED
Revenue now has three years of DAC7 data on Irish Amazon sellers — covering 2023, 2024, and 2025 — all submitted by Amazon directly. In 2026, that represents sufficient historical data for Revenue to identify sellers who have not registered for income tax, not registered for VAT, or significantly under-declared their Amazon income./strong>
If your Amazon income has not been declared to Revenue, this is not a situation where you can hope it goes unnoticed. The data is already there. Acting now — via a voluntary qualifying disclosure — is significantly less costly than waiting for Revenue to make contact.
DAC7 and You — What To Do
If you are a compliant Irish Amazon seller with all income declared, VAT filed, and tax returns submitted accurately, DAC7 is not a problem. It is simply Revenue having visibility that matches what you have already told them.
If you are not yet compliant, or uncertain about your compliance position, the correct approach is:
1. Conduct a compliance review
Establish what income has been earned, what has been declared, and what the gap might be.
2. Quantify any underpayment
Work out the income tax, USC, PRSI, and VAT that may be outstanding.
3. Make a qualifying disclosure
Before Revenue contacts you, a voluntary qualifying disclosure significantly reduces penalties — from up to 100% of the underpayment down to 3–20%. The window is before Revenue initiates contact about a specific liability.
4. Get compliant going forward
Register for income tax and VAT as required, file returns, and maintain proper records.
Amazon Bookkeeping — Reconciling Your Payouts
Amazon’s payment system is notoriously complex from a bookkeeping perspective. The amount that lands in your bank account every two weeks is not your revenue — it is a net settlement figure after Amazon has deducted dozens of line items including referral fees, FBA fees, advertising charges, storage fees, returns, refunds, and adjustments. Treating your bank deposits as your income figure is one of the most common — and most expensive — accounting mistakes Irish Amazon sellers make.
Understanding Your Amazon Settlement
Each Amazon settlement report contains:
Item
What It Represents
Tax Treatment
Product sales
Gross revenue from customer purchases
Taxable income — record as turnover
Shipping credits
Amounts customers paid for shipping
Taxable income if you receive it
Referral fees
Amazon’s commission (typically 8–15% of sale price)
Allowable business expense
FBA fees
Picking, packing, and shipping fees charged by Amazon
Allowable business expense
FBA storage fees
Monthly charges for warehouse space
Allowable business expense
Advertising (PPC)
Amazon Sponsored Products / Brands costs
Allowable business expense
Returns and refunds
Gross refunds to customers
Reduces turnover; also releases some fees
Promotional rebates
Discounts funded by Amazon
Reduces gross revenue
Vine programme fees
Costs for Amazon Vine review programme
Allowable business expense
Loan repayments
Amazon Lending repayments if applicable
Principal is balance sheet; interest is P&L
Correct Bookkeeping Methodology
The correct approach for Amazon seller bookkeeping is:
Record gross product sales as turnover — not the net settlement amount
Record each category of Amazon fees as a separate expense line — this gives you visibility on your cost structure and ensures all deductible costs are captured
Reconcile your settlement reports to your bank deposits every settlement period — any discrepancy needs to be investigated
Track inventory purchases separately as stock (a balance sheet item, not immediately an expense — it becomes cost of goods sold when the items are sold)
Record VAT separately from revenue, particularly if selling to OSS-liable countries at different rates
Maintain records of returns and refunds by month to correctly adjust your VAT position
Software Recommendations for Amazon Sellers
Managing Amazon bookkeeping manually in a spreadsheet becomes impractical above modest volumes. The following platforms integrate with Amazon Seller Central and can import settlement data automatically:
A2X — specifically built for Amazon sellers; automatically categorises Amazon transactions and maps them to accounting software
Xero or QuickBooks — combined with A2X for automated settlement reconciliation; both support Irish VAT returns and OSS filing
Linnworks or Katana — for sellers with complex multi-channel inventory management needs
Whatever software you use, the key is ensuring your data is reconciled correctly before your accountant files your returns. Garbage in, garbage out — and in this case, garbage out means an incorrect tax return and the risk of Revenue scrutiny.
THE FIX
A dedicated eCommerce accountant who understands Amazon’s settlement structure
will save you significantly more than their fee in correctly claimed expenses
and correctly filed VAT returns. Forti.ie works with Amazon sellers across
Ireland — contact us to discuss your bookkeeping setup.
Allowable Expenses for Amazon Sellers in Ireland
One of the most significant ways an Irish Amazon seller can legally reduce their tax bill is by correctly identifying and claiming all allowable business expenses. Your taxable profit is your revenue minus allowable expenses — every euro of genuinely incurred business expense that you fail to claim increases your tax bill unnecessarily.Revenue allows deductions for expenses that are wholly and exclusively incurred for the purpose of the trade. For Amazon sellers, the following categories typically qualify:
Cost of Goods Sold (COGS)
The single largest deductible expense for most Amazon sellers. This includes:
Purchase price of inventory sold during the year
Import duties, customs charges, and freight costs on stock purchases
Cost of product samples and testing
Quality inspection fees paid to third-party inspectors (e.g. in China)
Note: Inventory that has not yet been sold is a balance sheet asset (stock), not an immediate expense. Only the cost of goods actually sold in the tax year is deducted from that year’s profit.
Amazon Platform Fees
Referral fees (Amazon’s commission on each sale)
FBA fees (pick, pack, and ship per unit)
FBA storage fees (monthly and long-term storage)
Amazon Seller Central subscription (Individual or Professional plan fee)
Sponsored Products and Sponsored Brands advertising spend
Amazon Vine programme fees
Returns processing fees
Removal and disposal fees for stranded or unsellable inventory
Logistics and Fulfilment
Freight forwarder fees (sea or air freight from supplier to Amazon warehouse)
Courier and shipping costs (if using FBM — Fulfilment by Merchant)
Third-party logistics (3PL) costs if you use a prep centre in Ireland or the UK
Photography, graphic design, and brand asset creation
Other Allowable Expenses
Home office costs — a proportion of rent/mortgage interest, utilities, and broadband if you work from home (Revenue approved method)
Business banking fees and payment processing charges
Relevant training courses, books, and subscriptions
Travel expenses for supplier visits or trade shows (wholly business-related)
Capital allowances on equipment (computer, camera, office furniture) at 12.5% per year over 8 years
EXPENSES THAT ARE NOT ALLOWABLE
The following are commonly claimed incorrectly and disallowed by Revenue: personal clothing (unless a uniform or specialist protective clothing), meals and entertainment without a clear business purpose, personal phone costs not exclusively for business, and capital items expensed as revenue (they must be capitalised and claimed via capital allowances).
Sole Trader vs Limited Company for Irish Amazon Sellers
The question of whether to operate as a sole trader or through a limited company is one of the most important financial decisions an Irish Amazon seller can make. The right answer depends on your profit level, your personal financial situation, and your plans for the business. There is no universal correct answer — but there are clear indicators.
SOLE TRADER — DRAWBACKS
✗ All profits taxed at personal rates (up to 40% + USC + PRSI)
✗ Combined effective tax rate can exceed 50% on higher earnings
✗ Personal liability for all business debts
✗ Less scope for tax planning and retained earnings
✗ May look less credible to some suppliers
LIMITED COMPANY — ADVANTAGES
✓ 12.5% corporation tax on trading profits
✓ Profits retained in company taxed at 12.5% vs 40%+ personally
✓ Limited liability protection
✓ More tax planning options (salary + dividends)
✓ Can own IP, assets, invest surplus profits tax-efficiently
When Does Incorporation Make Sense for an Amazon Seller?
As a general rule of thumb, incorporation typically makes financial sense when your Amazon net profit exceeds €40,000–€50,000 per year and you do not need to extract all of that profit personally to live on. If you can leave retained profits in the company (investing in stock, growth, or other purposes), the tax saving from paying 12.5% corporation tax instead of 40%+ personal income tax is substantial.An Amazon seller making €80,000 net profit as a sole trader might face a combined income tax / USC / PRSI bill of around €34,000–€38,000. The same profit in a limited company paying corporation tax at 12.5% results in a company tax bill of €10,000 — leaving €70,000 in the company. The director then draws a tax-efficient salary (typically set to maximise PRSI credits without hitting the 40% band) and takes the remainder as dividends when and if needed.
INCORPORATION IS NOT ALWAYS THE RIGHT MOVE
A limited company comes with additional compliance costs: annual CRO filing,
directors’ returns, corporation tax returns (Form CT1), potential audit
requirements at higher turnover, and payroll to run if you pay yourself a
salary. The accounting fees are higher. For a seller making €30,000 net
profit who needs all of that to live on, the tax savings from incorporation
may not outweigh the compliance costs.
Take professional advice before incorporating. Forti.ie will model the tax
position for you across both structures so you can make an informed decision
based on your specific numbers.
Case Studies
The following case studies are based on real client situations handled by the Forti.ie team. Names, identifying details, and specific figures have been changed or anonymised. They are illustrative of the types of challenges Irish Amazon sellers face and how specialist accounting support resolves them.
1. The Handmade Goods Seller Who Did Not Know About VAT
Background:
A sole trader in the west of Ireland had been selling handmade homeware products on Amazon.co.uk and Amazon.de for three years, building turnover to approximately €95,000 per year. She operated from home and managed everything herself, including her own bookkeeping on a spreadsheet.
The Problem:
When she came to Forti.ie, she had never registered for VAT in Ireland and had not filed a self-assessment tax return for any of the three years she had been trading. She was aware she should probably be doing something but had not known what. Her combined unpaid Irish income tax, VAT, and PRSI across three years was estimated at approximately €48,000 before interest and penalties. She had also not registered for VAT in Germany despite having significant sales to German customers — a separate exposure.
What We Did:
We conducted a full compliance review, reconstructed her accounts for all three years from Amazon settlement reports and bank records, and quantified the exact liability. We then prepared and filed an unprompted qualifying disclosure with Revenue for the Irish liabilities. Simultaneously, we engaged a German VAT agent to address the German registration and file back-returns with the German tax authority under their voluntary disclosure equivalent.
The Outcome:
The qualifying disclosure resulted in penalties being capped at 3% of the Irish liability rather than the potential 100%. The total amount paid, including all tax, PRSI, VAT, interest, and penalties, was approximately €54,000 — substantially less than the unmanaged exposure would have been. She was then set up with a proper accounting and VAT compliance system going forward, including quarterly OSS filings through Revenue.
2. The FBA Seller Unaware of Pan-EU Stock Obligations
Background:
A private label seller in Dublin had been using Amazon Pan-European FBA for two years, selling into markets across Germany, France, Spain, Poland, and Italy. He was VAT-registered in Ireland and filed regular Irish VAT returns. He believed he was compliant because he had ‘sorted VAT’. His turnover had grown to approximately €320,000 across EU markets.
The Problem:
A review of his account revealed he had VAT registration obligations in Germany, France, Poland, Spain, and Italy due to Amazon storing his inventory in fulfilment centres in all five countries. He had no local VAT registrations in any of those countries. His Irish VAT return was also incorrectly treating EU sales as if OSS applied to all of them — but OSS cannot cover domestic sales from locally-stored stock. Additionally, DAC7 data submitted by Amazon to German tax authorities had flagged his inventory presence and triggered a registration demand letter from the German Finanzamt.
What We Did:
Forti.ie coordinated VAT registrations in all five required countries through specialist local agents in each jurisdiction. Back-filings were completed in Germany, France, and Poland under their respective voluntary disclosure frameworks where available. His OSS filings were reconstructed to correctly exclude domestic sales from local stock. His Irish VAT returns were also corrected to remove the incorrectly claimed input VAT on German import VAT (which should have been reclaimed locally in Germany).
The Outcome:
The total cost of remediation — registrations, back-filings, penalties, and professional fees across all jurisdictions — was approximately €28,000. Had he waited for Revenue authorities in each country to complete their investigations, the exposure would have been significantly higher. His business is now fully compliant across all five EU markets with automated VAT filing managed by Forti.ie on an ongoing basis.
3. The Successful Seller Who Incorporated at Exactly the Right Time
Background:
A sole trader in Cork had been selling sports nutrition products on Amazon for four years, growing from a side income to a primary income of approximately €110,000 net profit per year. He was registered for income tax and VAT, filed his Form 11 on time each year, and had a reasonable grasp of his obligations. His problem was a growing tax bill: as a sole trader on €110,000 net profit, he was paying approximately €48,000 in combined income tax, USC, and PRSI — leaving him €62,000 to live on.
The Problem:
He approached Forti.ie asking whether incorporation would save him money, and if so, when and how to do it. He had heard from other sellers that a limited company would reduce his tax bill but was unclear on the specifics and worried about compliance complexity.
What We Did:
We modelled his tax position across four scenarios: remaining as a sole trader; incorporating immediately; incorporating and paying himself a salary only; incorporating and taking salary plus dividends. The analysis showed that by incorporating and drawing a salary of €42,000 (using the full standard rate band) plus dividends of €25,000 at a point that suited his personal cash needs, his overall tax position could be improved materially. The remaining profits, retained in the company and reinvested in stock, were taxed at 12.5% rather than at personal rates. We managed the incorporation, registered the company with the CRO and Revenue, transferred trading to the new entity, set up payroll, and established the correct dividend policy.
The Outcome:
In the first full year of trading through the limited company, his combined personal and company tax bill reduced from approximately €48,000 to approximately €27,000 — a saving of €21,000, against annual accounting fees of €3,800. The retained profits in the company are now being used to fund new product launches. He has since expanded to three additional product lines and is on track for €200,000 turnover this year.
Frequently Asked Questions
The following questions are among the most common we receive from Irish Amazon sellers. They cover the practical day-to-day compliance questions that arise when running an Amazon business in Ireland in 2026.
Do I need to register for VAT to sell on Amazon in Ireland?
Not immediately — but you may need to sooner than you think. If your Amazon turnover from goods exceeds €80,000 in a 12-month period, VAT registration in Ireland is mandatory. However, even below this threshold, you may need to register for EU OSS if your cross-border EU sales exceed €10,000. And if you use Amazon FBA with stock stored in other EU countries, you may need local VAT registrations in those countries regardless of your sales volume. Review your position early — do not wait until you breach a threshold.
Does Amazon collect and pay VAT on my behalf?
It depends on the marketplace and transaction type. Amazon operates as a deemed supplier for certain sales — particularly sales by non-EU sellers to EU customers. For Irish-registered Amazon sellers selling on Amazon.co.uk or EU marketplaces, Amazon may collect and remit VAT in certain circumstances (e.g. UK sales under the UK marketplace facilitator rules). However, for your Irish VAT obligations and your OSS obligations on cross-border EU sales, you remain responsible. Amazon’s VAT Calculation Service can assist with setting correct VAT rates, but it does not file your returns or manage your registrations. Do not assume Amazon has handled your VAT compliance.
I sell on Amazon as a hobby — do I still owe tax?
If you are making a profit — even occasionally — Revenue takes the view that this is a taxable trade, not a hobby. The distinction between hobby and trade in Irish tax law is not based on how casually you approach the business; it is based on whether you are engaging in a systematic and sustained effort to make a profit. Most Amazon sellers, even those who started as hobbyists, meet this test. If your non-PAYE income (including Amazon income) exceeds €5,000 net or €30,000 gross in a tax year, you must register for self-assessment and file a Form 11.
What is DAC7 and does it affect me?
DAC7 is EU legislation that requires digital marketplace operators (including Amazon) to report seller earnings and transaction details to EU tax authorities annually. In Ireland, Amazon reports directly to Revenue. The threshold that triggers inclusion in DAC7 reporting is €2,000 in total income or 30 or more transactions in a reporting period. The vast majority of active Amazon sellers exceed this. Since January 2024, Amazon has submitted annual DAC7 reports to Revenue. Revenue now has several years of data on Irish Amazon sellers’ earnings — making undisclosed Amazon income significantly easier to identify.
What is the One Stop Shop (OSS) and do I need to use it?
The One Stop Shop (OSS) is an EU VAT simplification scheme that allows you to file a single quarterly VAT return in Ireland covering B2C sales to customers in all 27 EU member states, rather than registering for VAT in each country individually. You need to use OSS (or register locally in each country) once your total cross-border EU B2C sales exceed €10,000 per year. OSS does not cover sales of goods stored in other EU countries — those require local VAT registrations regardless of the OSS threshold.
Should I use Amazon FBA or FBM from a tax perspective?
From a pure Irish tax perspective, both FBA and FBM create the same Irish income tax obligations. The difference arises with EU VAT: FBA significantly increases your EU VAT complexity because Amazon may store your goods in multiple EU countries, creating local VAT registration obligations in each of those countries. FBM (Fulfilment by Merchant), where you ship directly from Ireland, typically only creates OSS obligations for cross-border B2C sales above €10,000. Many sellers choose FBA for its operational and sales rank benefits, but they should do so with full awareness of the VAT compliance requirements — and budget for the cost of managing multiple EU VAT registrations.
How far back can Revenue go if I have not declared my Amazon income?
Revenue can generally go back 4 years for innocent errors in self-assessment. Where deliberate non-compliance, fraud, or neglect is involved, there is no fixed time limit. Given that DAC7 reporting started for the 2023 tax year (submitted by Amazon in January 2024), Revenue now has at minimum the 2023 and 2024 tax years as a starting point. The appropriate response if you have undisclosed Amazon income is to take professional advice and make an unprompted qualifying disclosure to Revenue before Revenue contacts you. This significantly reduces the applicable penalties.
What expenses can I claim against my Amazon income?
You can claim any expense that is wholly and exclusively incurred for the purpose of your Amazon trade. This includes cost of goods sold (inventory), Amazon fees (referral, FBA, advertising, storage), freight and logistics costs, packaging, accounting and VAT compliance fees, Amazon seller tools and software, a portion of home office costs, capital allowances on business equipment, and professional development costs. You cannot claim personal expenses, the personal portion of dual-purpose costs, or capital items that should be depreciated via capital allowances.
When should I consider incorporating my Amazon business as a limited company?
The general trigger point for considering incorporation is when your Amazon net profit exceeds €40,000–€50,000 per year and you do not need to extract all of that profit personally for living expenses. The tax saving from paying 12.5% corporation tax on retained profits versus 40%+ personal income tax on those same profits can be substantial. However, incorporation also brings additional compliance costs (payroll, CT1 returns, CRO filings, higher accounting fees) that need to be weighed against the tax savings. Take professional advice before making this decision — the right answer depends on your specific financial situation.
What records do I need to keep as an Irish Amazon seller?
You are required to maintain records for a minimum of 6 years from the end of the relevant tax year. Records should include: Amazon settlement reports for all periods, purchase invoices for all stock and business expenses, records of inventory (opening stock, purchases, closing stock), bank statements, VAT records (sales, purchases, OSS returns), and correspondence with Revenue. Amazon settlement reports can be downloaded from Seller Central — we recommend downloading and archiving these monthly, as historical data may not be available indefinitely.
Eight essential topics every Irish employer needs to understand — from PAYE Modernisation and PRSI classes to My Future Fund pension auto-enrolment and Revenue audit risk. Accurate as of May 2026.
Payroll is one of the most legally sensitive and operationally complex obligations any Irish employer carries. Get it right and it’s invisible — a process that just happens every month. Get it wrong and you’re dealing with Revenue interest charges, penalties, back-PRSI demands, and stressed staff who’ve been taxed incorrectly for months.
This guide covers the eight areas that matter most for Irish SMEs in 2026. It’s written by the payroll team at Forti.ie and reflects current Irish law, Revenue guidance, and the significant changes introduced by Budget 2026 — including the launch of My Future Fund pension auto-enrolment in January 2026, updated PRSI rates from October 2025, and the expanded Enhanced Reporting Requirements now well into their second year.
Whether you’re a seasoned operator doing a compliance sense-check, a startup taking on your first employee, or an owner-manager wondering whether running payroll yourself is still the right call — there’s something here for you.
Are You Paying Your Staff Correctly? What Irish SMEs Get Wrong About Payroll
Since 1 January 2019, Ireland operates a real-time PAYE reporting system. Every time you pay an employee, you must submit a Payroll Submission Request (PSR) to Revenue on or before the date of payment. Gone are the old year-end P35 returns. The obligation is now continuous, automated, and closely monitored.
Most businesses have adapted to this shift — but adaptation isn’t the same as compliance. Below are the most common mistakes Irish SMEs are still making in 2026, and what they typically cost.
€2,000 Personal Tax Credit per employee (2026) €2,000 Employee (PAYE) Tax Credit per employee (2026) 11.25% Employer PRSI (Class A higher rate, Oct 2025) 0.0219% Revenue interest charge per day on underpayments
Mistake 1 — Submitting Payroll Reports Late
Under PAYE Modernisation, the PSR must be filed on or before the payment date — not the day after, not whenever it suits. Revenue’s systems are automated, and even a single day’s delay registers as a late filing. Repeat offences trigger compliance risk flags and can prompt a Revenue enquiry.
The Fix
Set a locked payroll processing date at least one business day before payment date. If your payroll software supports automated PSR submission, use it — and confirm the submission receipt before funds leave your account.
Revenue issues updated RPNs throughout the year — when a new employee joins, when tax credits change, when someone starts a second job, or when Revenue adjusts a liability from a previous year. Many employers pull the RPN once at the start of the year and never again. The result: employees paying the wrong amount of tax, often too much, and a reconciliation headache later.
With both the Personal Tax Credit and Employee Tax Credit standing at €2,000 each in 2026 — providing a combined annual credit of €4,000 for most employees — even small mismatches compound over 12 months.
The Fix
Pull fresh RPNs from Revenue’s systems before every payroll run — not just in January. This is automated in any compliant payroll software platform. If you’re running payroll manually, make it a non-negotiable pre-run step.
Mistake 3 — Applying Wrong PRSI Classes
PRSI classification errors are amongst the most expensive payroll mistakes, because incorrect PRSI means underpayments to the Social Insurance Fund — and Revenue will recover those underpayments with interest. The most problematic areas are proprietary directors (often coded as Class A when they should be Class S) and part-time employees who should be on Class J. See Section 3 for a full PRSI class breakdown.
Mistake 4 — Not Reporting Benefits in Kind (BIK) Through Payroll
Private health insurance, company vehicles, gym memberships, subsidised loans, and employer-provided accommodation are all examples of Benefits in Kind — taxable benefits that must be processed through payroll. Many SMEs either don’t know what qualifies as BIK, or assume small amounts won’t matter.
One notable positive change from 1 October 2025: meals provided by an employer to all employees on the employer’s own premises, eaten on site, are no longer treated as a taxable BIK. Working lunches provided on site for genuine business reasons are also excluded. However, this exemption is specifically for employer-premises, all-staff arrangements — selective or off-site dining still attracts BIK treatment.
The Fix
Maintain a live log of all non-cash benefits provided to employees. Review Revenue’s BIK guidelines annually — rates and exemptions do change. The annual small benefit exemption (e.g. gift vouchers) remains capped at €1,500 per employee per year in 2026, with a maximum of five qualifying benefits.
Mistake 5 — Missing My Future Fund Obligations
This is 2026’s biggest new payroll obligation. Since 1 January 2026, Ireland’s pension auto-enrolment scheme — My Future Fund — is live. Employees aged 23–60 earning over €20,000 per year who are not already contributing to a workplace pension through payroll must be automatically enrolled. Employer contributions are 1.5% of gross salary, matched by the employee, with the State adding €1 for every €3 saved. Contributions are capped on gross earnings up to €80,000. See Section 5 and the FAQ for full details.
Important — PRSI Rate Changes
From 1 October 2025, employer PRSI (Class A) is 11.25% for employees earning above €552 per week, and 9% below that threshold. Employee PRSI is 4.2%. A further increase — employer to 11.40%, employee to 4.35% — takes effect 1 October 2026, as part of Ireland’s multi-year Social Insurance Fund roadmap. Make sure your software is updated ahead of each change.
The Hidden Cost of Running Payroll In-House for Irish Businesses
Plenty of Irish business owners run payroll themselves and assume they’re saving money. On the surface, it looks simple — enter the hours, apply the tax credits, press send. In reality, the true cost of in-house payroll is almost always higher than the invoice from a professional payroll provider.
Here’s what most owner-managers aren’t counting when they do the sums.
The Time Cost
Processing payroll for even five employees — pulling RPNs, running calculations, checking PRSI classes, handling ERR submissions, managing BIK valuations, keeping up with legislative changes — easily takes three to five hours per month for someone who isn’t a specialist. For ten or more employees, you’re into a full day or more.
At an owner-manager’s effective hourly rate, that time has a cost. And unlike a payroll provider’s invoice, that cost never appears on a budget sheet, never gets reviewed, and never gets questioned.
Running It Yourself
3–8 hours of your time per month
Software subscription (often underused)
Keeping up with legislative changes yourself
Error risk falls entirely on you
Revenue compliance is your responsibility
No specialist cover if something goes wrong
Time away from revenue-generating activity
Outsourcing to Forti.ie
Fixed monthly cost — fully visible on your P&L
RPN management included
ERR submissions handled
PRSI and BIK compliance checked
My Future Fund / NAERSA submissions
Legislative updates applied automatically
Expert support if Revenue queries arise
RUNNING IT YOURSELF
3–8 hours of your time per month
Software subscription (often underused)
Keeping up with legislative changes yourself
Error risk falls entirely on you
Revenue compliance is your responsibility
No specialist cover if something goes wrong
Time away from revenue-generating activity
OUTSOURCING TO FORTI.IE
Fixed monthly cost — fully visible on your P&L
RPM management included
ERR submissions handled
PRSI and BIK compliance checked
My Future Fund / NEARSA submissions
Legislative updates applied automatically
Expert support if Revenue queries arise
The Error Cost
Revenue charges interest at 0.0219% per day on underpaid tax — approximately 8% per year. That’s before penalties, which can reach 100% of the underpaid amount in cases Revenue determines to be careless or deliberate. Payroll errors rarely affect one month. They tend to compound — the same incorrect PRSI class running for 12, 24, or even 36 months before being caught.
A single misfiled PRSI class on a director’s salary of €80,000 — Class A instead of Class S — can create a liability running to several thousand euro, plus interest, by the time it surfaces.
The Compliance Cost
Irish payroll law changes frequently. The 2024–2026 period alone has brought PRSI rate increases, the launch of My Future Fund, new ERR requirements, updated BIK rules for employer-provided meals, changes to the small benefit exemption, statutory sick pay obligations, and increases to the National Minimum Wage (now €14.15 per hour from January 2026). Keeping pace with all of this while running a business is a genuine challenge.
When something is missed, the cost typically isn’t the payroll error itself — it’s the Revenue intervention that follows, and the professional fees required to manage it.
The Statutory Sick Pay (SSP) Consideration
Ireland’s Statutory Sick Pay scheme introduced a new employer obligation: as of 2024, employers must pay employees a minimum of 5 days of statutory sick pay per year at 70% of their normal daily wage (capped at €110 per day). The scheme was designed to increase to 10 days by 2025, subject to Government review. These payments must be correctly processed through payroll. Many in-house operators are either unaware of this obligation or unsure how to apply it correctly alongside their existing sick pay arrangements.
The Bottom Line
Before deciding to keep payroll in-house, do a genuine cost-benefit analysis that includes your own time, the realistic risk of errors, and the cost of staying current with Irish payroll law. For most SMEs with five or more employees, outsourcing to a specialist is both cheaper and lower-risk than the alternative.
PRSI Classes Explained — Are You Categorising Your Employees Correctly?
Pay Related Social Insurance (PRSI) is one of the most commonly misunderstood elements of Irish payroll. The class assigned to each worker determines how much they — and their employer — contribute to the Social Insurance Fund, and it determines their entitlement to state benefits including the State Pension, Jobseeker’s Benefit, Maternity Benefit, and the new pay-related Jobseeker’s Benefit scheme.
There are 11 PRSI classes. Most private sector employees fall into Class A. But the exceptions matter enormously, and getting them wrong creates a liability that can run for years before anyone notices.
Class
Who It Applies To
Employee Rate (2026)
Employer Rate (2026)
Key Benefits Covered
A Most Common
Employees in private sector earning €352/week
4.2%
11.25% / 9%
Full range incl. State Pension (Contributory)
J
Employees earning ≤€352/week; employees aged 66+;
some occupational categories
Officeholders (e.g. non-exec directors, MEPs);
certain unearned income
4.2%
0%
No benefits
M
Employees/self-employed with no PRSI liability
(nil contribution)
0%
0%
No benefits
B, C, D
Most public servants recruited before 6 April 1995
(civil servants, Gardaí, Army)
Lower modified rates
Lower modified rates
State Pension (Non-Contributory) route;
no Jobseeker’s Benefit
H
Permanent Defence Forces officers recruited
after 6 April
Full rate
Full rate
Full range
*9% applies where weekly earnings are ≤€552; 11.25% applies above that threshold. From 1 October 2026, rates increase to 4.35% (employee) and 11.40% / 9.15% (employer).
The Proprietary Director Problem
This is the single most common and expensive PRSI classification error in Irish SMEs. A proprietary director is defined as a director who, alone or with a spouse and/or minor children, owns or controls more than 15% of the ordinary share capital of a company.
Proprietary directors must be on Class S — not Class A — for the income they receive from that company. Class S means the director pays PRSI at 4.2% on their own account but there is no employer PRSI contribution. This is frequently mishandled in two ways:
Coding a proprietary director as Class A: The employer incorrectly pays 11.25% PRSI on the director’s salary. This results in overpayments to the Social Insurance Fund — and creates complexity when the error is eventually identified and needs to be unwound.
Treating a salaried director who is not a proprietary director as Class S: They should actually be Class A. This leads to underpayments and the director losing entitlement to Class A benefits like Illness Benefit and Jobseeker’s Benefit.
High Risk Area
Revenue and the Department of Social Protection cross-reference payroll data and PRSI records. Incorrect director PRSI classification is frequently identified during compliance checks. Back contributions plus interest can run to significant sums, particularly for companies that have been trading for several years.
The Class J Threshold — Critical for Part-Time and Seasonal Workers
Employees earning €352 or less per week should be on Class J, not Class A. This applies regardless of whether they are full-time or part-time, temporary or permanent. However — and this is important — if an employee works in a week where their earnings exceed €352, they revert to Class A for that week. Payroll must handle this dynamically, week by week.
A sliding scale PRSI credit applies for weekly earnings between €352 and €424 — up to €12 per week. This credit reduces the PRSI liability for lower-paid workers and must be correctly applied.
PRSI and My Future Fund: What’s Connected?
My Future Fund (auto-enrolment) eligibility is based on income and age — not PRSI class. However, both PRSI classification and My Future Fund enrolment are employer obligations that must be correctly maintained through payroll. An employee on Class J who earns over €20,000 annually and meets the age criteria may still be eligible for My Future Fund even though they’re not on Class A PRSI.
Action Point
Review every worker on your payroll — employees, directors, and part-timers. Confirm each person’s PRSI class against their actual employment status and shareholding. If any directors are approaching or above the 15% shareholding threshold, take professional advice before the next payroll run. The cost of getting this right now is a fraction of the cost of unwinding it after a Revenue compliance check.
What Every Irish Employer Needs to Know About the Enhanced Reporting Requirements (ERR)
The Enhanced Reporting Requirements (ERR) came into force on 1 January 2024 and represent one of the most significant expansions of employer reporting obligations since PAYE Modernisation itself. Despite being well into their second year, many Irish employers — particularly smaller SMEs — are still not fully compliant.
ERR requires employers to report certain non-taxable payments to employees to Revenue in real time — on or before the date the payment is made. The key word is non-taxable. Many employers assume that because a payment isn’t subject to PAYE, USC, or PRSI, Revenue doesn’t need to know about it. Under ERR, they do.
What Payments Must Be Reported Under ERR?
The three categories currently covered by ERR are:
Category
What’s Covered
Current Limit / Rate
Notes
Travel & Subsistence
Civil service mileage rates paid for business travel;
subsistence payments for overnight stays and day trips
Revenue civil service rates
(updated periodically)
Payments must not exceed Revenue-approved rates
to remain non-taxable
Remote Working Daily Allowance
Tax-free payments made to employees
working from home
€3.20 per remote working day
Employee must be working from home —
no hybrid or in-office on that day
Small Benefit Exemption
Non-cash benefits such as gift vouchers,
retail vouchers, experience days
Up to €1,500 per employee per year;
maximum 5 qualifying benefits
Must be non-cash; benefit cannot be a cash payment
or cash equivalent directly redeemable for cash
How Do You Submit an ERR Report?
ERR reports are submitted through the same channel as your standard Payroll Submission Request — via your payroll software or Revenue Online Service (ROS). Unlike the PSR, which captures taxable payroll data, ERR is submitted as a separate return specifically for the non-taxable payments listed above. The deadline mirrors the PSR: on or before the date of payment.
Not all payroll software platforms support ERR natively. If yours doesn’t, or if you’re running payroll manually, you’ll need to file ERR separately through ROS. This is one of the more practical arguments for using a managed payroll service — ERR compliance is included as standard.
What Happens If You Don’t Comply?
Revenue initially adopted an educational stance when ERR launched, signalling a transitional period. That period is now over. Revenue is actively monitoring ERR compliance and has the power to treat failure to report as a PAYE compliance risk. In practice, non-compliance is increasingly flagging businesses for closer scrutiny of their overall payroll compliance — not just the ERR payments themselves.
Common ERR Errors to Avoid
Reporting expenses after payment: ERR is real-time. If you pay travel and subsistence on the 15th, the ERR must be filed by the 15th — not at the end of the month with payroll.
Confusing taxable and non-taxable travel payments: ERR is real-time. If you pay travel and subsistence on the 15th, the ERR must be filed by the 15th — not at the end of the month with payroll.
Treating cash payments as small benefit exemptions: The small benefit exemption covers non-cash benefits only. Gift vouchers are fine. A cash bonus is not, regardless of the amount.
The Fix
Conduct an immediate audit of all non-cash employee payments made in 2026. Confirm whether your payroll software supports ERR submission. If it doesn’t — or if ERR is an afterthought in your payroll process rather than an integrated step — consider a managed payroll solution that handles ERR compliance as part of the standard monthly service.
Employing Your First Member of Staff in Ireland? Here’s What You Need to Sort
Taking on your first employee is one of the most significant milestones for any Irish business. It’s also one of the most common points at which payroll compliance breaks down — not through negligence, but because there’s simply a lot to set up, and the sequence matters. Get the foundations right from day one and payroll runs smoothly. Miss a step and you’re unravelling it later under pressure.
Here is everything you need to have in place before paying your first employee in Ireland in 2026.
1. Register as an Employer with Revenue
Before you pay anyone, register as an employer using Revenue’s Online Service (ROS) or myAccount. You’ll receive an Employer Registration Number (ERN). Without this, you cannot process PAYE, PRSI, or USC, and you cannot receive RPNs for your employees. Registration is free and can typically be done in 24–48 hours, though it’s wise to allow a week.
2. Obtain Your Employee’s PPSN and RPN
Ask your employee for their Personal Public Service Number (PPSN). Once they’ve registered the employment with Revenue (via myAccount), Revenue will generate a Revenue Payroll Notification (RPN) which tells you their tax credits, cut-off points, and USC bands. Without a valid RPN, you must apply emergency tax — which means your employee pays significantly more tax until the RPN is received.
3. Issue a Written Contract of Employment
Under the Terms of Employment (Information) Acts, you must provide a written statement of core employment terms within five days of starting employment. A full written contract — covering pay, hours, leave entitlements, notice periods, and sick pay arrangements — is strongly recommended and must be provided within one month. Failure to do so creates an unfair dismissal and employment claims risk, separate from payroll compliance.
4. Set Up Payroll Software or a Managed Service
You are legally required to maintain detailed payroll records and submit PSRs and ERR reports to Revenue in real time. Manual spreadsheets are not compliant with this obligation. You need either Revenue-approved payroll software or a managed payroll provider. Payroll software must be capable of RPN retrieval, PSR submission, ERR filing, and — for eligible employees — My Future Fund NAERSA submissions.
5. Pay at Least the National Minimum Wage
The National Minimum Wage in Ireland from 1 January 2026 is €14.15 per hour for employees aged 20 and over. Sub-minimum rates apply for employees under 20, though these have been converging with the full rate as part of Government policy. Paying below the minimum wage exposes you to a claim before the Workplace Relations Commission (WRC) and can result in significant awards.
6. Understand PAYE, USC, and PRSI Deductions
Three deductions apply to most employees: Income Tax (PAYE) at 20% on the standard rate band and 40% above it; the Universal Social Charge (USC) applied in bands (0.5%, 2%, 3%, 8%); and PRSI at 4.2% (Class A employees in 2026). As an employer, you also pay Class A employer PRSI at 11.25% (above €552/week) or 9% (at or below €552/week) — this is your cost, on top of gross salary.
7. Assess My Future Fund (Pension Auto-Enrolment) Eligibility
If your new employee is aged 23–60, earns over €20,000 per year, and is not already contributing to a workplace pension through payroll, they must be enrolled in My Future Fund from 1 January 2026. You are required to register on the NAERSA employer portal, set up a payment method, and process contributions through payroll. In 2026, both you and the employee contribute 1.5% of gross salary, with the State adding €1 per €3 saved. Contributions apply to gross earnings up to €80,000.
8. Issue Payslips
Under the Payment of Wages Act, you must provide a written or electronic payslip for every pay period. The payslip must show gross pay, all deductions (PAYE, USC, PRSI, pension contributions), and net pay. Failure to provide compliant payslips is an offence and can result in WRC complaints.
9. Know Your Statutory Leave Obligations
From day one of employment, employees accrue statutory annual leave entitlements, public holiday entitlements, statutory sick pay rights (5 days per year at 70% of normal daily wage, capped at €110/day), and parental leave rights. These must be factored into payroll planning from the start — and any leave pay must be correctly calculated and reported.
First Employee Checklist Summary
Register as employer with Revenue → Get employee PPSN → Pull RPN → Issue contract → Set up payroll system → Confirm NMW compliance → Assess My Future Fund eligibility → Register on NAERSA → Provide payslips from day one → Record statutory leave entitlements.
Payroll Compliance in Ireland — What a Revenue Audit Could Uncover
Nobody wants a Revenue knock on the door. But understanding what a payroll audit looks like — how it’s triggered, what auditors look for, and what the consequences are — is one of the most valuable things an employer can know. Because the businesses who come through audits cleanly aren’t the ones who got lucky. They’re the ones who treated payroll as a compliance function, not an afterthought.
How Revenue Identifies Payroll Compliance Issues
Revenue’s PAYE Modernisation system generates real-time data on every employer’s payroll submissions. This gives Revenue unparalleled visibility into patterns, anomalies, and inconsistencies — far more than the old annual P35 return ever provided. The following patterns are known to trigger closer scrutiny:
Repeated late PSR submissions
Significant differences between reported payroll and a business’s VAT turnover (suggesting undisclosed cash wages)
PRSI class patterns that don’t match industry norms (e.g. a construction company with many employees on Class S)
No BIK reported on benefits typically associated with the business type (e.g. a car dealer with no company vehicle BIK)
Missing or incomplete ERR submissions
Employer PRSI contribution amounts that seem inconsistent with reported headcount
Significant changes in payroll without corresponding changes in the business’s turnover or VAT profile
Area Examined
Common Issues Found
PRSI classifications
Proprietary directors on Class A;
part-timers on wrong class
Benefits in Kind
Undeclared company cars, health insurance,
preferential loans
Contractor payments
Bogus self-employment; contractors who should
be employees
Dividends used to avoid PRSI;
benefits not processed through payroll
My Future Fund
Non-enrolment of eligible employees;
incorrect contribution processing
Payslip compliance
Failure to provide compliant payslips
to all employees
Employment records
Incomplete records; cash payments
without PAYE processing
Interest and Penalties — The Real Numbers
Revenue charges interest on underpaid tax and PRSI at a rate of 0.0219% per day — equivalent to approximately 8% per year. This interest runs from the date the payment was due, not the date it was discovered. A PRSI underpayment running for three years accrues roughly 24% in interest alone, before any penalties are applied.
Penalties on top of the underpayment and interest can reach:
Up to 3% of the tax/PRSI underpaid — for minor, non-deliberate errors
Up to 20% — for carelessness
Up to 40% — for deliberate non-compliance
Up to 100% — for serious deliberate non-compliance (with publication on Revenue’s list of tax defaulters)
These penalties are negotiable — but only within the qualifying disclosure framework, and only before Revenue makes contact.
The Qualifying Disclosure: Your Best Protection
A qualifying disclosure is a voluntary declaration to Revenue of a tax or PRSI underpayment, made before Revenue contacts the taxpayer about that specific issue. Making an unprompted qualifying disclosure:
Reduces penalties to 3% (minor errors) or 10–20% (more serious) instead of up to 100%
Avoids publication on Revenue’s defaulters list
Demonstrates good faith, which materially affects how Revenue handles the overall case
Gives you control over the timeline and resolution of the issue
Revenue can look back four years for innocent errors, and further for fraud or neglect. If you identify a payroll error today — even one that goes back several years — making a qualifying disclosure before Revenue contacts you is almost always the right course of action.
What to Do If You Suspect a Payroll Error
Don’t ignore it and hope for the best. Conduct an internal review, quantify the underpayment, and take professional advice before making any contact with Revenue. A qualified payroll professional or tax advisor can help you structure a qualifying disclosure correctly, minimise penalties, and manage the resolution process. The sooner you act, the lower the cost.
The Difference Between an Employee and a Contractor in Ireland — And Why It Matters for Payroll
The distinction between an employee and a self-employed contractor is one of the most consequential — and most frequently misapplied — in Irish employment and tax law. Getting it wrong doesn’t just create a payroll problem. It creates a PRSI liability, a PAYE liability, and potentially an employment rights liability, all at once.
Revenue has made bogus self-employment a compliance priority in recent years, and for good reason. The misclassification of employees as independent contractors denies the state PRSI contributions, denies employees social welfare entitlements they haven’t been contributing to, and typically reduces the cost base for the engaging business in ways that undercut competitors who properly employ their staff.
The Code of Practice on Determining Employment Status
The legal framework for employment status in Ireland is the Code of Practice on Determining Employment or Self-Employment Status of Individuals, produced jointly by Revenue, the Department of Social Protection, and the WRC. The Code is built around a series of indicators — no single factor is decisive, but together they determine whether a working relationship is one of employment or self-employment.
Factor
Points to Employment
Points to Self-Employment
Control
Employer controls when, where, and how work is done
Worker controls their own methods and schedule
Substitution
Must personally perform the work
Can send a substitute to do the work
Equipment
Employer provides tools, equipment, workspace
Worker provides their own tools and equipment
Financial risk
Paid regardless of outcome; no risk of loss
Bears risk of profit and loss from the work
Integration
Integrated into business — attends meetings,
has email, business card
Provides a service to the business from the outside
Exclusivity
Works exclusively or almost exclusively
for one client
Works for multiple clients simultaneously
Duration
Open-ended, ongoing engagement
Defined project with clear end date
Benefits
Receives holiday pay, sick pay, pension
No employment benefits received
What Are the Consequences of Misclassification?
If Revenue or the WRC determines that someone you treated as a contractor was actually an employee, the consequences can be severe:
Back PAYE and USC on all payments made to the “contractor” — often going back four years
Back employer and employee PRSI contributions — at Class A rates, calculated on all payments
Interest on all of the above at 0.0219% per day from the date each payment was due
Penalties of up to 100% of the tax underpaid
Employment rights claims from the individual — unfair dismissal, annual leave, redundancy
Potential publication on Revenue’s defaulters list for serious cases
The “Personal Service Company” Complexity
Some contractors operate through their own limited company — a common arrangement in Irish IT, finance, and construction. This doesn’t automatically resolve the employment status question. If the substance of the arrangement is that the individual performs work exclusively for one client, under the client’s direction, the Code of Practice may still conclude that the individual is effectively an employee of the client. Revenue has actively pursued this area, particularly in sectors where contractor structures are prevalent.
How to Protect Your Business
Risk Mitigation Steps
1. Apply the Code of Practice before engagement: Before engaging any individual as a contractor, work through the Code of Practice indicators. If the majority point toward employment, treat them as an employee.
2. Review existing contractor arrangements: If you have contractors who have been working exclusively for you for more than six months, under your direction, using your equipment, they likely fail the self-employment test. Restructure the arrangement now rather than waiting for Revenue to find it.
3. Document the basis for self-employment status: Keep a written record of why each contractor was determined to be self-employed. This is useful evidence in the event of a dispute.
4. Take professional advice on grey areas: Many contractor arrangements are genuinely ambiguous. A payroll or tax specialist can help you assess the risk and, where necessary, restructure the engagement correctly.
Year-End Payroll Checklist for Irish Employers
Year-end payroll is a critical compliance event for every Irish employer — and since the introduction of PAYE Modernisation, it looks very different from the old days of a single P35 return. The good news is that if you’ve been running a clean, compliant payroll throughout the year, the year-end process is largely a reconciliation rather than a discovery exercise. The bad news is that for many SMEs, year-end is when the chickens come home to roost.
Use this checklist to work through the key year-end obligations and ensure your business enters the new year in full compliance.
1. Finalise and Reconcile Payroll for the Tax Year
Reconcile your total payroll spend — gross pay, PAYE, USC, employee PRSI, and employer PRSI — against your payroll software records and bank payments for the year. Any discrepancies between what was deducted, what was submitted to Revenue via PSR, and what was actually paid over through P30 monthly remittances need to be identified and resolved before the year closes.
Submit a final PSR (marked as final for the tax year) for your last payroll run of the year. This signals to Revenue that the payroll year is complete for your business.
2. Issue Employment Detail Summaries (the P60 Equivalent)
Since the end of P60s in 2019, employees can access their own income and tax details for the year via Revenue’s myAccount portal — this is known as the Employment Detail Summary (EDS). As an employer, you don’t issue a physical document, but you should ensure all your PSR submissions for the year are accurate, because the EDS is generated directly from your payroll data. Any errors in your submissions will create incorrect EDS figures for your employees — and they will come back to you.
Communicate to your employees at year-end that they can access their EDS (and make a request for a PAYE reconciliation if they believe they’ve overpaid tax) via myAccount. This is a simple but appreciated act of good employee communication.
3. Declarations and Valuations for Benefits in Kind
December is the time to finalise your Benefits in Kind position for the year. This includes:
Company vehicles: Calculate the annual BIK value based on the original market value (OMV) and business use percentage. The BIK rate applied depends on the vehicle’s CO₂ emissions band and, for electric vehicles, its range. BIK on company vehicles must be reported through payroll.
Private health insurance: The employer’s cost of private health insurance for an employee (and their family, if covered) is a BIK. Ensure the annual premium has been correctly included in the employee’s gross income for the year.
Employer-provided accommodation: Where an employer provides rent-free or subsidised accommodation, the taxable value must be calculated and processed through payroll.
Preferential loans: Loans provided to employees at below Revenue’s specified interest rate create a BIK equal to the notional interest saving.
Small benefit exemption review: Confirm that all gift vouchers and non-cash benefits provided during the year stay within the annual €1,500 cap and the 5-benefit maximum. Any excess over the limit becomes taxable and must be processed through payroll.
4. Holiday Pay Reconciliation
Employees are entitled to a minimum of 4 weeks’ annual leave per year (or 8% of hours worked, whichever is less, for part-time workers). At year-end, reconcile leave taken against leave accrued for each employee. Any accrued but untaken annual leave that is carried over — or paid out, where your employment contracts provide for this — must be handled correctly in payroll.
Importantly, under the Organisation of Working Time Act, the method for calculating annual leave pay must reflect the employee’s normal weekly earnings — including regular overtime, shift premium, and similar recurring payments. Annual leave calculated on basic pay alone, where the employee regularly earns more, will be incorrect and may give rise to a WRC complaint.
5. Review and Verify My Future Fund Contributions
For the 2026 year-end, you should reconcile all My Future Fund contributions processed through payroll during the year. Confirm that:
All eligible employees (aged 23–60, earning >€20,000, not in an existing pension via payroll) were enrolled from their eligibility date
Employee contributions of 1.5% and employer contributions of 1.5% were correctly deducted and remitted to NAERSA each pay period
Any employees who opted out during their opt-out window (months 6–8) were correctly processed
New employees who became eligible during the year were enrolled at the correct point
Contribution records match the NAERSA portal statements
6. ERR Annual Review
Review all ERR submissions made during the year. Confirm that travel and subsistence payments, remote working allowances, and small benefit exemptions were all reported correctly and on time. If any payments were made but not reported under ERR, consider whether a voluntary correction is appropriate before Revenue identifies the gap.
7. Prepare for the January PRSI Rate Update (October 2026)
While not a year-end task in the traditional sense, budget preparation for 2027 must account for the PRSI rate increase on 1 October 2026: employer PRSI rises to 11.40% (higher band) and 9.15% (lower band); employee PRSI rises to 4.35%. Model the cost impact on your total payroll bill before setting headcount and salary budgets for the year ahead.
Payroll Checklist
✓
Final PSR submitted and marked as year-end
✓
PSR data reconciled to bank payments and P30 remittances
✓
All employee EDS figures checked for accuracy
✓
BIK valuations finalised and processed through payroll
✓
Annual leave accrual and outstanding balances reconciled
✓
My Future Fund contributions reconciled with NAERSA records
✓
ERR submissions reviewed and any gaps remedied
✓
Statutory sick pay records reconciled for the year
✓
All contractor payments reviewed for employment status risk
✓
Director PRSI classifications confirmed for the coming year
✓
October 2026 PRSI rate increases budgeted for
✓
Payroll records retained (minimum 6 years)
Record Retention
Irish employers are required to retain payroll records for a minimum of 6 years following the end of the tax year to which they relate. This includes payslips, PSR submissions, RPN records, ERR filings, BIK workings, expense claims, employment contracts, and My Future Fund contribution records. Revenue can request these during a compliance check or audit. Digital records are acceptable provided they are accurately maintained and accessible.
Frequently Asked Questions About Irish Payroll 2026
Q1. What are the current tax credits for employees in Ireland in 2026?
In 2026, both the Personal Tax Credit and the Employee (PAYE) Tax Credit are €2,000 each, giving most employees a combined credit of €4,000 per year. These credits reduced tax liability by €4,000 per year, effectively meaning the first €20,000 of income (at the 20% rate) is tax-free for a standard PAYE employee. There were no changes to income tax rates, bands, or the main tax credits in Budget 2026.
Q2. What is the employer PRSI rate in Ireland in 2026?
From 1 October 2025, the Class A employer PRSI rates are: 11.25% for employees earning more than €552 per week, and 9% for employees earning €552 or less per week. Employee PRSI (Class A) is 4.2%. From 1 October 2026, these increase to 11.40% / 9.15% (employer) and 4.35% (employee) as part of a multi-year increase schedule legislated to fund the Social Insurance Fund.
Q3. What is My Future Fund and who does it apply to?
My Future Fund is Ireland’s mandatory pension auto-enrolment scheme, which launched on 1 January 2026. It applies to employees aged 23–60 who earn more than €20,000 per year and are not already contributing to a workplace pension through payroll. In 2026, employees and employers each contribute 1.5% of gross salary, and the State adds €1 for every €3 saved. Contributions apply to gross earnings up to €80,000. Employers must register on the NAERSA portal and process contributions through payroll. Employees can opt out between months 6 and 8 but will be automatically re-enrolled every two years if they remain eligible.
Q4. What is the Enhanced Reporting Requirement (ERR)?
ERR, in force since 1 January 2024, requires employers to report certain non-taxable payments to Revenue in real time, on or before the date of payment. The three categories covered are: travel and subsistence payments (within Revenue’s civil service rates), the remote working daily allowance (€3.20 per day), and the small benefit exemption (non-cash benefits up to €1,500 per employee per year, maximum 5 benefits). ERR is filed separately from the PSR, through payroll software or ROS.
Q5. What PRSI class should a proprietary director be on?
A proprietary director — one who owns or controls more than 15% of the company’s share capital (alone or combined with a spouse/civil partner and minor children) — must be on Class S PRSI for income received from that company. Class S: employee contribution is 4.2%; employer contribution is 0%. This is one of the most common and costly payroll errors in Irish SMEs. Class S provides limited social welfare coverage compared to Class A — it does not cover Jobseeker’s Benefit or Illness Benefit, for example.
Q6. What is the National Minimum Wage in Ireland in 2026?
From 1 January 2026, the National Minimum Wage for employees aged 20 and over is €14.15 per hour. This applies to most employees, including full-time, part-time, temporary, casual, and seasonal workers. Employers in sectors with a Joint Labour Committee (JLC) registered employment agreement may be subject to higher sectoral minimum rates. Sub-minimum rates apply for employees under 20, though the gap has been narrowing.
Q7. How far back can Revenue audit payroll records?
Revenue can go back 4 years for innocent errors in payroll records. Where fraud or neglect is involved, there is no fixed time limit. Payroll records must be retained for a minimum of 6 years following the relevant tax year. Making an unprompted qualifying disclosure before Revenue contacts you significantly reduces penalties — from up to 100% of the underpayment down to 3–20%, depending on the nature of the error.
Q8. What is the difference between an employee and a self-employed contractor in Ireland?
Employment status in Ireland is determined using the Code of Practice on Determining Employment or Self-Employment Status of Individuals. Key factors include: who controls when, where, and how the work is done; whether the person can send a substitute; whether they supply their own equipment; whether they bear financial risk; and whether they work for multiple clients. No single factor is conclusive. If Revenue determines a contractor relationship is actually employment, the employer faces back PAYE, back PRSI, interest, and penalties — in addition to potential employment rights claims.
Q9. Do I need to report meals I provide to staff through payroll in 2026?
From 1 October 2025, meals provided by an employer to all employees on the employer’s premises, eaten on site, are no longer treated as a taxable Benefit in Kind. Working lunches or dinners on site provided for genuine business reasons are also excluded. This is a welcome simplification for many employers. However, selective arrangements (e.g. meals only for certain employees), off-site meals, or vouchers/allowances for food are likely to remain taxable BIK and must be processed through payroll accordingly.
PAYE Modernisation, My Future Fund, ERR, PRSI classifications, BIK reporting — managed payroll from Forti.ie covers every obligation, every month, so you can focus on your business.
This article is intended for general educational purposes only and does not constitute professional tax, legal, or accounting advice. Figures and rates are accurate as of May 2026 based on publicly available Revenue guidance, Budget 2026 measures, and current Irish legislation. Tax law and Revenue guidance change regularly — readers should always verify current rates with Revenue.ie or consult a qualified Irish accountant, tax advisor, or payroll professional for advice specific to their circumstances. Forti.ie accepts no liability for decisions made solely on the basis of this article.
Structural Changes
If your company structure changes, we handle all required CRO filings and statutory updates. Includes:
Director appointments or resignations
Share transfers or allotments
Company name changes
We ensure your company records remain accurate and legally compliant.
Strike
If you decide to close your company, we manage the full voluntary strike-off process, including compliance review, documentation, and filing with the Companies Registration Office (CRO), ensuring the company is properly and safely dissolved.
Additional CRO Filings
Director changes, share transfers, share allotments, company name changes or other statutory updates.
RBO Filing / Ownership Updates
Required whenever shareholders or beneficial ownership changes (25%+). We prepare and submit the update to the Central Register to keep your company compliant
Registered Office Address
Secure and reliable registered office solution to improve your business reputation. This add-on service provides an official business address for company registration and ensures important business correspondence is handled professionally. Includes:
Official registered business address
Use for company registration
Handling of business correspondence
Professional business presence
Reliable address for official records
Full Company Secretary Service
Our full company secretary service ensures your company adheres to corporate governance standards. This includes maintaining statutory registers, filing annual returns, handling board resolutions, and advising on legal compliance. By outsourcing this service, you can reduce administrative workload and ensure your company avoids compliance-related risks.
Register of Beneficial Owners (RBO) Filing / Update
Every Irish company must file and maintain accurate beneficial ownership details with the Central Register of Beneficial Owners (RBO). Our service includes:
Preparation and electronic filing with the Central RBO
Review of 25%+ ownership or control thresholds
Confirmation of submission for your records
Required within 5 months of incorporation and whenever shareholding changes. Failure to file can result in significant penalties — we ensure your company remains fully compliant.
Strike Off
If you need to close your company — whether within the first year or later — we manage the entire voluntary strike-off process professionally and compliantly. Our team handles:
Director resolutions and required documentation
Pre-strike-off compliance review
Preparation and filing with the Companies Registration Office (CRO)
We ensure your company is properly wound down to avoid delays, penalties, or future compliance issues.
Please note: CRO filing fee and required newspaper advertisement costs are separate.
Digital Marketing Services (Free Consultation)
Reaching your audience effectively is key to growth. This free consultation introduces startups and small businesses to digital marketing strategies, including social media management, search engine optimisation (SEO), and online advertising, tailored to your industry and goals.
Introduction to Website Development Company (Free)
Building a strong online presence is vital for any business. This free service connects you with experienced website development companies, offering startups and small businesses tailored consultations to help establish or upgrade their online platforms.
Modern businesses thrive on effective communication. This service provides VoIP phone solutions and professional call answering with calendar management and call forwarding. It ensures no business opportunities are missed while projecting a professional image to clients and partners.
6-Month Annual Return Filing
Filing the first Annual Return (B1) is an important requirement to keep your company compliant and in good standing. This service includes the preparation, filing, and management of all required documents for the year, such as financial statements, shareholder reports, and any necessary changes to the company structure. It allows you to focus on growing your business while ensuring your obligations are met. Includes:
Preparation and electronic filing
Deadline monitoring
Audit exemption protection
This filing is required even if no financial statements are due.
Annual Return Filing per Year
Annual returns are essential for keeping your company information up-to-date with the Companies Registration Office (CRO). This service ensures that all required information, such as directors, shareholders, and company financials, is filed accurately and on time, avoiding late penalties and maintaining good standing.
Annual Compliance Support
Annual compliance is critical for avoiding fines and maintaining good standing with regulatory authorities. This service includes the preparation, filing, and management of all required documents for the year, such as financial statements, shareholder reports, and any necessary changes to the company structure. It allows you to focus on growing your business while ensuring your obligations are met. Includes:
Annual Return (B1) filing
Statutory register maintenance
Deadline tracking
Audit exemption monitoring
Compliance advisory support
Ideal for directors who want ongoing professional oversight.
Annual Return (B1) Filing
Preparation and filing of yearly CRO Annual Return (after year one).
Helps maintain good standing and avoid late filing penalties.
Full Company Secretary Service
Our full company secretary service ensures your company adheres to corporate governance standards. This includes maintaining statutory registers, filing annual returns, handling board resolutions, and advising on legal compliance. By outsourcing this service, you can reduce administrative workload and ensure your company avoids compliance-related risks.
Historical filing and bookkeeping services are for businesses that have gaps in their financial year filings. We will require this information for compliance and reporting purposes, regardless of the gap duration.
Manage Annual Returns Deadline (Included)
File Annual Return in CORE (Included)
File PDF Financial Statements in CORE File Manager (Included)
Signing Annual Return and Bank Application Documents (Included (Limited)**)
Company Secretarial Paperwork Filing (Included)
Maintaining and Updating Company Registers (Included)
Drafting Minutes for Board Meetings (AGM Included) (Included)
Ongoing Company Secretarial Advice (Annual Limit) (Up to 300 minutes)
Countersignatures for Company Bank Applications/Reports (Not Included)
Traditional phone systems are transformed by VoIP (vocal over Internet Protocol) technology, which facilitates vocal communication over the internet. This technology is extensively employed in cloud-based phone services. The latest technology provides businesses with substantial advantages, such as seamless integration with a variety of digital tools and increased flexibility. Our call answering services ensure that you never miss an important call. We ensure that your business’s communication is both efficient and effective by managing your diary, receiving inquiries, and forwarding them to you.
Our Business Address Service will improve your company’s corporate image by providing a prestigious address for your correspondence. We will forward your business correspondence to an alternative address of your choosing via post for a nominal fee of €55 per month. This service is renewable annually, with an additional fee for forwarding general business correspondence.
If you need cloud based phone services, enquire now.
Company Formation
Includes CRO Filing Fee for Private Limited Company or DAC.
Manage Annual Returns Deadline (Included)
File Annual Return in CORE (Included)
File PDF Financial Statements in CORE File Manager (Included)
Signing Annual Return and Bank Application Documents (Included (Limited)**)
Company Secretarial Paperwork Filing (Included)
Maintaining and Updating Company Registers (Included)
Drafting Minutes for Board Meetings (AGM Included) (Included)
Ongoing Company Secretarial Advice (Annual Limit) (Up to 300 minutes)