Side hustles begin quietly. You take on a freelance project after work, tutor a few clients at weekends, sell a service online, do photography jobs, create paid content or earn commission from a platform. Your main salary is already taxed through PAYE, so it is easy to assume the extra income will somehow be dealt with in the same way.
It usually will not.
Your employer only operates PAYE on the pay it gives you. Extra income earned outside that employment still has to be declared, and the way you declare it depends on how much non-PAYE income you have and what kind of activity produced it.
For many PAYE workers, the dividing line is not simply whether the side hustle made money. Revenue uses two important thresholds:
€5,000 of taxable non-PAYE income;
€30,000 of gross non-PAYE income.
Those figures decide whether a PAYE taxpayer can generally report smaller amounts through myAccount or needs to enter the self-assessment system and file Form 11.
Another point: A person who is self-employed should register for Income Tax self-assessment. So the €5,000 and €30,000 limits should not be read as a blanket exemption for every person who has started a genuine trade or business.
Start With Revenue’s Two Non PAYE Income Thresholds
Taxable non-PAYE income is the amount that remains taxable after the deductions that Revenue allows for the relevant source of income. For a self-employed activity, that will usually involve calculating business income and deducting allowable business expenses before arriving at taxable profit.
A PAYE employee who earns €4,000 of taxable non-PAYE income, with gross non-PAYE income no higher than €30,000, may generally declare that income through a Form 12 in myAccount rather than becoming a chargeable person for self-assessment solely because of that income.
Once taxable non-PAYE income goes above €5,000, Form 11 becomes relevant.
The key word is “exceeds”. Revenue’s published threshold is more than €5,000, not €5,000 or more, for this particular self-assessment test.
Gross non PAYE income
The second threshold can catch people whose taxable profit looks small.
If your gross non-PAYE income exceeds €30,000, you may have to file Form 11 even where the taxable amount is below €5,000. Revenue treats the gross test separately from the taxable-income test, so you should not look at net profit alone when deciding how to file.
This is particularly relevant for side hustles with substantial costs, such as event work, reselling, production services or activities where you pay subcontractors or buy materials.
The €30,000 figure also should not automatically be treated as identical to simple bank lodgements or invoice totals. The calculation depends on the source and the tax rules that apply to that source. If your figures are close to the threshold, work from the accounts rather than estimating from cash received.
When Form 12 Is Usually Enough
A PAYE worker with modest additional income can often stay within the PAYE system for reporting purposes.
Non-PAYE income that does not exceed the €5,000 taxable and €30,000 gross limits can be declared through an online Form 12 using myAccount. Revenue can then collect the tax due by adjusting your tax credits and standard rate cut-off point. This process is often called coding the income.
That can be far simpler than registering for self-assessment where the activity is genuinely small and the Form 12 route applies.
Suppose you work full-time and make €2,800 in taxable profit from occasional freelance design work during 2026. Your gross non-PAYE income is also well below €30,000. Based on those figures alone, you are below both mandatory thresholds.
You still declare the income. The lower figure changes how it is reported, not whether it is taxable.
A small side income is still taxable income
One common misunderstanding is that earning less than €5,000 means no tax is due.
The €5,000 figure is a self-assessment filing threshold for certain PAYE taxpayers. It is not a general tax-free allowance for side hustles.
Your extra taxable income is added into your wider tax position. The actual Income Tax depends on your rate band, tax credits and personal circumstances. USC can also apply. If the activity is self-employment, PRSI may become relevant once the separate PRSIconditions are met.
So a €3,500 side profit can create a tax bill even though it may be reported through Form 12 rather than Form 11.
When You Need To Register for Self Assessment
The clearest mandatory triggers for a PAYE worker with non-PAYE income are:
taxable non-PAYE income above €5,000
gross non-PAYE income above €30,000.
Once one of those tests is met, Revenue requires self-assessment registration and a Form 11 Income Tax Return.
Revenue also lists self-employed people among those who should register for Income Tax self-assessment. That wording matters for people who have moved beyond occasional extra income and are actively carrying on a trade, profession or business.
A person can be a PAYE employee and self-employed at the same time. Your employment income continues through your employer’s payroll. Your self-employed income is dealt with separately through your own tax registration and return.
Your PAYE salary does not remove the filing obligation
Having tax deducted every month by your employer does not cancel the rules for your side business.
Form 11 brings the different parts of your income together. Revenue’s online return includes PAYE income already reported by your employer as well as sections for trading, rental, foreign and other income. The calculation then takes account of tax already paid through PAYE.
You are not being taxed twice on your salary. The return uses your full tax position to calculate what is still payable.
What Counts as Side Hustle Profit
For a typical self-employed side business, tax is based on taxable profit rather than every euro of sales.
You need records that show what you earned and what the business spent. Revenue allows deductions for expenses that meet the rules for the trade. Deductible expenses must relate to the running of the business, and mixed private and business costs must be apportioned.
That distinction can materially change the figure you report.
A freelance photographer may receive €12,000 from clients during the year and incur qualifying business costs for software subscriptions, insurance, website hosting, certain travel, professional services and equipment-related tax allowances. The taxable figure will not necessarily be €12,000.
Equally, a personal purchase does not become deductible because you also use it occasionally for the side hustle.
Expenses with both business and private use
Phone bills, motor costs and some home-related costs may have a mixed purpose. Revenue allows the business portion where the expenditure qualifies, rather than the entire cost.
If 40% of a phone plan genuinely relates to business use, you work with the supportable business share. Claiming 100% because you sometimes answer client messages on the phone would overstate the deduction.
Keep invoices, receipts, statements and a reasonable basis for any apportionment.
Capital purchases need separate treatment. Capital expenditure is not deducted in the same way as normal day-to-day business expenses, although capital allowances may be available on qualifying assets.
Your PAYE Salary Affects the Rate on Your Side Income
Your side-hustle profit is not taxed in isolation.
Ireland’s 2026 Income Tax system applies a 20% standard rate up to your available standard rate band and 40% above it. For a single person without qualifying children, the 2026 standard rate band is €44,000. Other bands apply depending on marital status and circumstances.
If your PAYE salary has already used your full 20% band, additional taxable profit may fall into the 40% Income Tax rate before credits and other adjustments.
Take a single PAYE employee earning €50,000 in 2026. Their salary already exceeds the €44,000 standard-rate band. If they then make €6,000 of taxable profit from freelance work, the extra profit is entering a tax position where the standard band has already been used.
That is why saving only 20% of side-hustle profit can leave some higher-paid PAYE workers short when the return is filed.
Your exact USC treatment depends on the type and amount of income and any exemptions or special rates that apply. A side hustle can push more income into a higher USC band even when PAYE has already been deducted correctly from your salary.
PRSI has its own rules
Self-employed income can also bring Class S PRSI into the calculation.
The Department of Social Protection states that self-employed people with sufficient reckonable income generally pay Class S. For 2026, the Class S rate is 4.20% up to 30 September and 4.35% from 1 October. For people returning PRSI through the self-assessment system, the Department gives a blended 2026 rate of 4.2375%, subject to the applicable minimum contribution rules.
PRSI is generally due for a self-employed person with minimum annual income of €5,000, subject to age and exemption rules.
These thresholds and rates are separate from the €5,000 taxable non-PAYE threshold used to decide whether Form 11 is mandatory. Similar numbers appear in different rules, so use the rule that applies to the question you are answering.
Preliminary Tax Can Catch New Side Businesses Off Guard
Moving into self-assessment changes the timing of your tax payments.
Under Revenue’s Pay and File system, 31 October is the standard deadline for filing the previous year’s return, paying the balance for that previous year and paying preliminary tax for the current year.
This year, a person filing through ROS can qualify for the extended deadline of 18 November 2026 where both the 2025 Form 11 return and the appropriate payment are completed through ROS.
Preliminary tax is an advance payment towards the current year’s Income Tax, PRSI and USC liability.
Revenue allows preliminary tax to be based on at least the lowest of:
90% of the tax due for the current year
100% of the tax due for the immediately previous year
105% of the tax due for the pre-preceding year where the direct-debit conditions apply.
The first year can work differently. Revenue says a first-year self-assessed taxpayer may choose 100% of the previous year’s liability. Where the previous year’s self-assessment liability was nil, this can mean no preliminary tax payment is required under that option in year one.
That does not make the first year’s profit tax-free. It can shift the cash pressure into the next Pay and File date, when the previous year’s balance and the new preliminary tax can arrive together.
For a growing side business, setting money aside as you earn it is usually less painful than finding the full amount later.
Three Examples That Show Where the Line Falls
PAYE employee with €3,000 of taxable freelance income
You earn a normal PAYE salary and make €3,000 taxable profit from occasional freelance work. Your gross non-PAYE income is comfortably below €30,000.
On those figures, you are below the two mandatory Form 11 thresholds. You can generally declare the additional income through Form 12 in myAccount, subject to the nature of the activity and Revenue’s registration rules.
Tax can still be due on the €3,000.
PAYE employee with €7,500 of taxable side profit
Your salary is taxed through PAYE and your separate consulting work produces €7,500 of taxable profit.
The taxable non-PAYE income is above €5,000. You must register for self-assessment and file Form 11.
The fact that consulting is done only in evenings or on occasional weekends does not reduce the amount for tax purposes. Revenue looks at the income and the nature of the activity, not the label “side hustle”.
PAYE employee with income close to the gross threshold
Your taxable profit remains below €5,000, but the gross non-PAYE figure is approaching €30,000.
Do not decide the filing method from profit alone. The gross test can independently trigger self-assessment. This is a point worth checking before year-end because registration, record keeping and preliminary-tax planning become easier when they are dealt with before the filing deadline.
Online Side Hustles Still Count
Income from online platforms is still income.
That includes activities such as paid short-term accommodation, freelance marketplace work, online sales carried on as a trade and other platform-based services. The tax treatment depends on what you are doing, how regularly you do it and whether you are trading or simply disposing of personal belongings.
Revenue receives information about certain sellers and service providers under DAC7 and related digital-platform reporting rules. Platform reporting does not create a new tax, and a platform reporting threshold is not the same thing as an Income Tax threshold.
It does make record keeping more important.
Match platform statements to your own records. Keep evidence of fees deducted by the platform, refunds, business costs and amounts actually received.
Income Tax Registration Is Not the Same as VAT Registration
A side business can have more than one tax threshold to monitor.
The Income Tax self-assessment limits discussed above determine how certain non-PAYE income is reported. VAT has separate registration thresholds.
Revenue’s current principal VAT thresholds include €42,500 for persons supplying services only and €85,000 for persons supplying goods. Different thresholds and rules apply to certain mixed supplies, EU acquisitions, cross-border distance sales and other situations.
So someone can need Form 11 without being VAT registered. Another business may need to examine VAT because of its turnover even though the owner is also a PAYE employee.
Do not use the €5,000 self-assessment figure as a VAT test.
Keep the PAYE Job and Side Business Records Separate
A second bank account is not always a legal requirement for a sole trader, but separating business transactions makes the accounts much easier to reconstruct.
At minimum, keep:
sales invoices and platform statements
receipts and supplier invoices
payment records
records of refunds
details supporting mixed-use expense percentages
equipment purchase documents
mileage or travel records where relevant
copies of tax filings and Revenue correspondence.
Your PAYE data is largely reported through payroll. The side business needs its own support.
This becomes especially important where customers pay through several channels. A person might receive Stripe payments, bank transfers and cash during the same year. Looking at one bank account in October and treating that as annual income can miss part of the picture.
6 Common Mistakes PAYE Workers Make With Side Income
1. Treating the €5,000 threshold as a tax-free amount
It is not. The threshold helps determine whether certain PAYE taxpayers must enter self-assessment. Income below it can still produce tax.
2. Waiting until Form 11 is due to work out profit
By then, receipts may be missing and mixed expenses become harder to justify. Updating the figures during the year also gives you a better estimate of the eventual tax bill.
3. Looking only at net profit
The €30,000 gross non-PAYE test exists separately. Both tests need attention.
4. Assuming PAYE has already covered everything
Your employer deducts tax on employment pay. It does not know the final profit from your freelance work, online shop or weekend business.
5. Claiming every personal cost as a business expense
Revenue requires a business connection and limits deductions for mixed-use and private costs. Keep the calculation supportable.
6. Forgetting about VAT as turnover grows
Income Tax and VAT use different rules. A business can cross one threshold long before another.
A Simple Filing Check for a PAYE Employee
Use this as a starting point for reviewing your specific activity.
Your position
Likely route
PAYE income and taxable non-PAYE income of €5,000 or less, with gross non-PAYE income of €30,000 or less
Declare through Form 12 in myAccount where the Form 12 route applies
Taxable non-PAYE income above €5,000
Register for self-assessment and file Form 11
Gross non-PAYE income above €30,000
Register for self-assessment and file Form 11
You have started carrying on a genuine self-employed trade or business
Review self-assessment registration because Revenue lists self-employed persons among those who should register
Side-business turnover is growing
Check VAT separately using the VAT rules and thresholds
Note the fourth line in particular. Income thresholds are useful, but they do not replace the question of what the activity actually is.
What To Do When Your Side Hustle Starts Making Real Money
First, work out the numbers properly. Separate gross non-PAYE income from taxable income, and keep a running record of deductible costs.
Then decide whether the activity is occasional extra income or has become a self-employed trade. Check the €5,000 and €30,000 self-assessment tests and register before filing if Form 11 is required.
After that, estimate the tax rather than waiting for Revenue’s calculation to surprise you. Your PAYE salary may already use much of your 20% rate band, so the marginal tax on extra profit can be higher than expected.
Finally, monitor turnover for VAT separately.
A side hustle can stay small for years, or it can turn into a meaningful second income within a few months. The tax administration should change when the numbers and the activity change. The useful point is knowing where that change happens.
FAQs:
Do I need to register for self-assessment if I earn money from a side hustle?
Not necessarily. If your taxable non-PAYE income is no more than €5,000 and your gross non-PAYE income is no more than €30,000, you may generally report it through Form 12 in myAccount where that route applies.
Is the €5,000 side-income threshold tax-free?
No. The €5,000 figure is a filing threshold for certain PAYE taxpayers, not a tax-free allowance. Side-hustle income can still create an Income Tax liability even when it is reported through Form 12.
When do I need to file Form 11?
You generally need to register for self-assessment and file Form 11 when taxable non-PAYE income exceeds €5,000 or gross non-PAYE income exceeds €30,000.
Does my PAYE salary affect the tax I pay on my side hustle?
Yes. Your side-hustle profit is considered alongside your PAYE income. If your salary has already used your available standard-rate band, additional taxable profit may be taxed at the higher Income Tax rate.
Do I need to consider VAT if my side business grows?
Yes. VAT has separate registration rules and thresholds from Income Tax self-assessment. You should monitor your business turnover separately as the side business grows.
Salary, Dividends, Expenses and Director Loans Explained
A limited company can have plenty of cash in its bank account and still leave you with a basic question: how do you actually take money out for yourself? Well, it depends on what the payment represents. A salary is pay for your work. A dividend is a distribution to you as a shareholder. An expense repayment gives you back money you spent for the business. A director loan is money owed in one direction or the other. Those are not interchangeable. Moving €2,000 from the company account to your personal account and deciding what it was at year-end can create tax and accounting problems, particularly once a director loan account becomes overdrawn. The right approach is to decide how each withdrawal should be treated before the payment is made, then record it correctly. If you use our limited company accounting support, your payroll, bookkeeping and year-end accounts will be aligned.
Quick answer Most owner-directors use a combination rather than one method. Salary usually provides regular personal income through payroll. Dividends may be paid from distributable profits to shareholders. Genuine business expenses can be reimbursed separately when the conditions are met. Director loans need tighter control because company-to-shareholder loans can trigger both company tax and benefit-in-kind issues.
Start With Salary for Regular Personal Income
Salary is the cleanest route when you need a predictable amount each month. The company pays you through payroll, deducts the taxes required by your Revenue Payroll Notification and reports the payment to Revenue on or before the pay date. Revenue applies PAYE to both proprietary and non-proprietary directors in the same way it applies PAYE to other employees. A company must register as an employer where it pays a director, even when the director is its only worker. Income Tax, USC and PRSI can then apply to the salary. For an owner-manager, the important point is that PAYE reporting still applies even though you control the company.
What the 2026 Income Tax Figures Mean
For 2026, a single person has a €44,000 standard rate band, with income within that band generally taxed at 20% and the balance at 40%. The single person tax credit is €2,000. Personal circumstances can change the band and available credits, so a married director, jointly assessed couple or single parent may have a different result. Revenue publishes the 2026 tax bands and credits here. There is an easy credit trap for owner-directors. A proprietary director who controls more than 15% of the ordinary share capital cannot claim the Employee Tax Credit against income from that directorship. Instead, proprietary director pay can qualify for the Earned Income Credit. In 2026 that credit is the lower of €2,000 or 20% of qualifying earned income. Revenue sets out the Earned Income Credit rules for proprietary directors.
PRSI Uses a Different Ownership Test
Do not use the 15% tax-credit threshold to decide PRSI. A proprietary director who owns or controls 50% or more of a company is classified as self-employed for PRSI and pays Class S. Directors below 50% are assessed according to their circumstances. The Department of Social Protection guidance treats the 50% test separately from Revenue’s proprietary-director test for tax credits. Class S is 4.20% up to 30 September 2026 and rises to 4.35% from 1 October 2026. The minimum annual Class S contribution is €650. If your shareholding is close to the relevant threshold or the ownership structure is more complicated than a single shareholder company, confirm the PRSI class rather than copying the setup of another director. Salary also has a company-side effect. Genuine remuneration for work carried out in the trade is normally recorded as a staff or director cost, subject to the usual tax rules on deductibility and timing. That is different from a dividend, which Revenue expressly states is not deductible when calculating trading profits. Irish trading income is generally subject to Corporation Tax at 12.5%. The number of directors using payroll is substantial. Revenue’s 2025 PAYE analysis recorded 85,607 proprietary directors with €4.888 billion of gross pay, alongside 9,239 non-proprietary directors. Salary through payroll is therefore not an unusual workaround for company owners. It is a standard part of operating an Irish company.
Use Dividends Only When the Company Has Profits Available
A dividend is paid because you own shares. It is not a substitute label for money already withdrawn from the bank. Irish company law restricts distributions to profits available for that purpose. Under section 117 of the Companies Act 2014, those profits are broadly accumulated realised profits that have not already been distributed or capitalised, less accumulated realised losses that have not been written off. A healthy bank balance does not prove that the company has distributable reserves. That distinction is particularly important for a young company. You may have collected annual subscriptions in advance, received a large customer deposit or simply have cash reserved for VAT and Corporation Tax. None of those facts, on their own, establish the amount legally available for dividend.
What Happens When an Irish Company Pays a Dividend
An Irish resident company generally deducts Dividend Withholding Tax at 25% when it makes a dividend or other relevant distribution. If the company declares a gross dividend of €4,000 to you, the normal starting position is €1,000 DWT and €3,000 cash paid to you. The company files and pays the DWT through ROS by the 14th day of the following month. Revenue’s DWT filing guidance also requires a return for a month in which a relevant distribution is made, including cases where no DWT was deducted because an exemption applied.
The 25% deduction is a withholding payment, not necessarily your final tax rate. You declare the gross dividend on your personal tax return. Dividend income is added to your other income and can be liable to Income Tax at 20% or 40%, USC and PRSI, depending on your circumstances. DWT already deducted is credited against the final Income Tax liability.
There is also no Corporation Tax deduction for paying a dividend. Revenue states that dividends and other distributions are not deductible when the company calculates trading profits. This is one reason a salary-versus-dividend comparison needs to look at both the company and the shareholder rather than comparing the cash amounts alone.
A Dividend Should Be Documented as a Dividend
Before payment, confirm the company has enough distributable profits and follow the company’s process for approving the dividend. Keep the supporting accounts, board documentation and dividend voucher or shareholder statement with the company records. If there are several shareholders, share rights and the company constitution also matter. For a one-person company, these formalities can feel excessive because the shareholder and director are the same individual. The company remains a separate legal entity. That separation is exactly what makes the limited company structure useful, so the records should reflect it.
Reimburse Genuine Business Expenses Separately
Expense reimbursement is often the least controversial money you take from the company because, when the conditions are met, it is simply repayment of a cost you incurred while doing your job.
Revenue permits tax-free reimbursement of employee and director expenses where the expense was incurred wholly, exclusively and necessarily in performing the duties and the repayment is supported by vouched receipts. Travel and subsistence can also be repaid under the relevant rules, including approved Civil Service rates in qualifying cases.
A director who pays €180 personally for a qualifying business trip should normally record the €180 as a company expense and receive reimbursement against the supporting record. It should not be added to a later dividend simply because both payments eventually reach the same bank account.
Some Common Payments Are Still Taxable
Home-to-work travel is generally private travel. If the company repays it, the repayment normally has to be treated as pay. Round-sum allowances are also taxable where the company simply pays a fixed amount such as €300 per month for travel or living costs without satisfying the expense reimbursement conditions. Revenue treats those payments as pay through payroll.
And how are the records?
Revenue requires employers to retain information supporting travel and subsistence claims, including the director or employee, date, business reason, journey details, kilometres and the reimbursement basis. Receipts are required where actual costs are reimbursed, and the records must generally be kept for six years. Since 1 January 2024, certain untaxed benefits and expense payments are also subject to Revenue employer reporting rules known as ERR. A clean expense process is simple: pay business costs from the company account where sensible, upload receipts promptly, record personally funded costs separately and reimburse the exact qualifying amount. This also makes the bookkeeping easier when your accountant reviews the director loan account.
Treat Director Loans as Balance Sheet Transactions
A director loan account records money moving between you and the company that is not salary, dividend or an expense reimbursement. The direction of the balance changes the tax risk.
When You Lend Money to the Company
Founders often pay incorporation costs, software, deposits or early supplier bills personally before the business bank account is fully funded. If those amounts are properly company costs, the company may owe you money. You may also lend cash directly to the company.
Repayment of the original amount the company owes you is normally a balance-sheet repayment rather than salary or a dividend. Interest is separate. A close company can face distribution rules where interest above the specified limit is paid to a director or associate with a material interest. Revenue currently identifies 13% per annum as the specified rate for that close-company rule.
When the Company Lends Money to You
This is the side that needs more care. Most Irish owner-managed companies are close companies. Where a close company makes a loan or advance to a participator or an associate, Revenue requires the company to account for Income Tax on the grossed-up loan. The tax is included on the company’s Corporation Tax return and is not deductible for Corporation Tax.
Take a €10,000 loan from a company to an owner-shareholder. With a 20% standard Income Tax rate, €10,000 is treated as the after-tax amount. Grossing it up gives €12,500, producing €2,500 of company Income Tax under the close-company loan rule. If the loan is later repaid, the company can claim repayment of the corresponding tax, subject to the statutory time limits.
There is a €19,050 exclusion for certain full-time employees or directors who do not have a material interest in the company. Material interest is broadly more than 5% ownership or control for this rule. That exclusion therefore does little for many founder-directors who own a meaningful share of their company.
A Low-Interest Loan Can Also Create Benefit in Kind
The close-company loan charge is not the only issue. An interest-free or low-interest employer loan can create a taxable benefit in kind. Revenue’s current specified rate is 4% for a qualifying home loan and 13.5% for other loans. The taxable benefit is the difference between the interest actually paid and the interest calculated using the specified rate, and the company operates Income Tax, PRSI and USC on that benefit through PAYE.
Writing the loan off later is not a clean escape. Revenue treats a written-off amount as taxable income to the borrower, with separate consequences under the close-company rules.
How the Four Payment Routes Compare
Method
What it represents
Main tax route
Company requirement
Best fit
Salary
Pay for your work as director or employeee
PAYE, Income Tax, USC and PRSI
Payroll registration, RPN and reporting on or before pay date
Regular personal income
Dividend
Return to you as shareholder
25% DWT upfront, then personal Income Tax, USC and PRSI as applicable
Distributable profits, approval records and DWT filing
Profitable company with available reserves
Expense reimbursement
Repayment of qualifying business costs you funded
Can be tax-free where Revenue conditions are me
Receipts, business purpose and ERR reporting where applicable
Genuine work costs
Director loan
Temporary amount owed by you or to you
Depends on direction; company-to-owner loans may trigger close-company tax and BIK
Accurate director loan ledger, repayment terms and tax review
Short-term balance sheet funding, not routine drawings
A Salary and Dividend Mix Can Work Better Than a Single Route
There is no universal salary number that every Irish company director should use. A director with no other income, a director whose spouse earns a separate salary, and a director who already has PAYE income elsewhere can have very different tax outcomes from the same company payment.
Keep tabs on cashflow. A company that is profitable on paper may still need money for VAT, payroll, suppliers and preliminary Corporation Tax. Paying the maximum possible dividend simply because reserves exist can leave the business short several weeks later.
For many established owner-managed companies, the workable pattern is a regular salary that meets the director’s household needs, separate reimbursement of genuine expenses and dividends at selected points after reviewing the company’s accounts and cash position. Contractors using a personal limited company often use this type of planning, which is why Forti’s contractor accounting service includes payroll, salary and dividend planning alongside Corporation Tax and director reimbursements.
Do Not Decide From the Company Bank Balance Alone
Before moving money to yourself, your bookkeeping should tell you at least four things:
how much profit has actually been earned;
what tax liabilities are building up;
whether the company has distributable reserves, and;
whether your director loan account is already overdrawn.
A €60,000 bank balance can shrink quickly once VAT, payroll taxes, suppliers and Corporation Tax are allowed for. Irish trading profits are generally taxed at 12.5%, while non-trading income is generally taxed at 25%. Keeping a tax reserve in the company account makes withdrawal decisions much easier.
This is also where regular bookkeeping earns its keep. Forti’s Irish startup accounting checklist covers payroll and director loan accounts early in the company lifecycle, before small informal withdrawals become a year-end clean-up exercise.
Questions to Answer Before Your Next Withdrawal
Am I being paid for work, receiving a shareholder distribution, reclaiming a business cost or borrowing money?
Has the company processed salary through payroll before or on the payment date?
If this is a dividend, do the accounts show enough realised distributable profits after accumulated losses?
Has 25% DWT been dealt with and is the DWT return diary date recorded?
If this is an expense, do I have the receipt and a clear business reason?
What is the current balance on my director loan account?
Could a company-to-director loan trigger the close-company gross-up charge or preferential-loan BIK?
How much cash must stay in the company for VAT, payroll, suppliers and Corporation Tax?
Build the Payment Method Around Your Actual Numbers
For an owner-director, “salary or dividend?” is usually too narrow a question. Your personal tax position, shareholding, PRSI class, company profit, cash requirements and existing director loan balance all influence the answer.
Set a regular salary deliberately. Reimburse qualifying business expenses as they arise. Review dividends against current management accounts rather than the bank balance. Keep director loans exceptional and visible in the books.
Done that way, taking money from your company becomes part of normal financial management rather than something that has to be reconstructed after year-end.
Frequently Asked Questions
1. How can a company director take money out of a company in Ireland?
A: A company director can generally take money as salary, dividends, reimbursement of genuine business expenses, or through a director loan. Each method has different tax, accounting and reporting requirements.
2. Are dividends taxable for company directors in Ireland?
A: Yes. Irish companies generally deduct 25% Dividend Withholding Tax (DWT) when paying a dividend. The gross dividend must also be declared on the director’s personal tax return and may be subject to Income Tax, USC and PRSI
3. Can a company reimburse a director for business expenses?
A: Yes. Genuine business expenses can generally be reimbursed where they meet Revenue’s conditions and are supported by appropriate records, such as receipts and details of the business purpose.
4. Can a director borrow money from their company in Ireland?
A:A director can receive a loan from their company, but company-to-director loans can trigger close-company tax rules and potentially a taxable benefit in kind. The loan should therefore be properly recorded and reviewed before payment.
5. Should a company director take a salary or dividends?
A: There is no single option that suits every director. The appropriate mix depends on personal income, shareholding, PRSI status, company profits, distributable reserves, cash flow and existing tax liabilities.
Eight essential topics every Irish employer needs to understand — from PAYE Modernisation and PRSI classes to My Future Fund pension auto-enrolment and Revenue audit risk. Accurate as of May 2026.
Payroll is one of the most legally sensitive and operationally complex obligations any Irish employer carries. Get it right and it’s invisible — a process that just happens every month. Get it wrong and you’re dealing with Revenue interest charges, penalties, back-PRSI demands, and stressed staff who’ve been taxed incorrectly for months.
This guide covers the eight areas that matter most for Irish SMEs in 2026. It’s written by the payroll team at Forti.ie and reflects current Irish law, Revenue guidance, and the significant changes introduced by Budget 2026 — including the launch of My Future Fund pension auto-enrolment in January 2026, updated PRSI rates from October 2025, and the expanded Enhanced Reporting Requirements now well into their second year.
Whether you’re a seasoned operator doing a compliance sense-check, a startup taking on your first employee, or an owner-manager wondering whether running payroll yourself is still the right call — there’s something here for you.
Are You Paying Your Staff Correctly? What Irish SMEs Get Wrong About Payroll
Since 1 January 2019, Ireland operates a real-time PAYE reporting system. Every time you pay an employee, you must submit a Payroll Submission Request (PSR) to Revenue on or before the date of payment. Gone are the old year-end P35 returns. The obligation is now continuous, automated, and closely monitored.
Most businesses have adapted to this shift — but adaptation isn’t the same as compliance. Below are the most common mistakes Irish SMEs are still making in 2026, and what they typically cost.
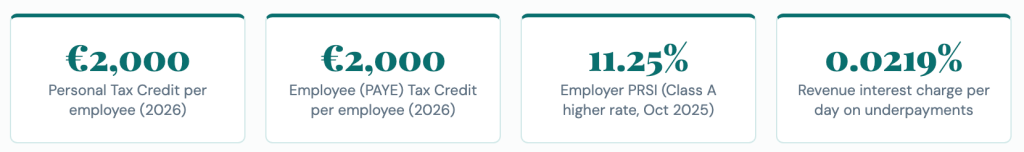
€2,000 Personal Tax Credit per employee (2026) €2,000 Employee (PAYE) Tax Credit per employee (2026) 11.25% Employer PRSI (Class A higher rate, Oct 2025) 0.0219% Revenue interest charge per day on underpayments
Mistake 1 — Submitting Payroll Reports Late
Under PAYE Modernisation, the PSR must be filed on or before the payment date — not the day after, not whenever it suits. Revenue’s systems are automated, and even a single day’s delay registers as a late filing. Repeat offences trigger compliance risk flags and can prompt a Revenue enquiry.
The Fix
Set a locked payroll processing date at least one business day before payment date. If your payroll software supports automated PSR submission, use it — and confirm the submission receipt before funds leave your account.
Revenue issues updated RPNs throughout the year — when a new employee joins, when tax credits change, when someone starts a second job, or when Revenue adjusts a liability from a previous year. Many employers pull the RPN once at the start of the year and never again. The result: employees paying the wrong amount of tax, often too much, and a reconciliation headache later.
With both the Personal Tax Credit and Employee Tax Credit standing at €2,000 each in 2026 — providing a combined annual credit of €4,000 for most employees — even small mismatches compound over 12 months.
The Fix
Pull fresh RPNs from Revenue’s systems before every payroll run — not just in January. This is automated in any compliant payroll software platform. If you’re running payroll manually, make it a non-negotiable pre-run step.
Mistake 3 — Applying Wrong PRSI Classes
PRSI classification errors are amongst the most expensive payroll mistakes, because incorrect PRSI means underpayments to the Social Insurance Fund — and Revenue will recover those underpayments with interest. The most problematic areas are proprietary directors (often coded as Class A when they should be Class S) and part-time employees who should be on Class J. See Section 3 for a full PRSI class breakdown.
Mistake 4 — Not Reporting Benefits in Kind (BIK) Through Payroll
Private health insurance, company vehicles, gym memberships, subsidised loans, and employer-provided accommodation are all examples of Benefits in Kind — taxable benefits that must be processed through payroll. Many SMEs either don’t know what qualifies as BIK, or assume small amounts won’t matter.
One notable positive change from 1 October 2025: meals provided by an employer to all employees on the employer’s own premises, eaten on site, are no longer treated as a taxable BIK. Working lunches provided on site for genuine business reasons are also excluded. However, this exemption is specifically for employer-premises, all-staff arrangements — selective or off-site dining still attracts BIK treatment.
The Fix
Maintain a live log of all non-cash benefits provided to employees. Review Revenue’s BIK guidelines annually — rates and exemptions do change. The annual small benefit exemption (e.g. gift vouchers) remains capped at €1,500 per employee per year in 2026, with a maximum of five qualifying benefits.
Mistake 5 — Missing My Future Fund Obligations
This is 2026’s biggest new payroll obligation. Since 1 January 2026, Ireland’s pension auto-enrolment scheme — My Future Fund — is live. Employees aged 23–60 earning over €20,000 per year who are not already contributing to a workplace pension through payroll must be automatically enrolled. Employer contributions are 1.5% of gross salary, matched by the employee, with the State adding €1 for every €3 saved. Contributions are capped on gross earnings up to €80,000. See Section 5 and the FAQ for full details.
Important — PRSI Rate Changes
From 1 October 2025, employer PRSI (Class A) is 11.25% for employees earning above €552 per week, and 9% below that threshold. Employee PRSI is 4.2%. A further increase — employer to 11.40%, employee to 4.35% — takes effect 1 October 2026, as part of Ireland’s multi-year Social Insurance Fund roadmap. Make sure your software is updated ahead of each change.
The Hidden Cost of Running Payroll In-House for Irish Businesses
Plenty of Irish business owners run payroll themselves and assume they’re saving money. On the surface, it looks simple — enter the hours, apply the tax credits, press send. In reality, the true cost of in-house payroll is almost always higher than the invoice from a professional payroll provider.
Here’s what most owner-managers aren’t counting when they do the sums.
The Time Cost
Processing payroll for even five employees — pulling RPNs, running calculations, checking PRSI classes, handling ERR submissions, managing BIK valuations, keeping up with legislative changes — easily takes three to five hours per month for someone who isn’t a specialist. For ten or more employees, you’re into a full day or more.
At an owner-manager’s effective hourly rate, that time has a cost. And unlike a payroll provider’s invoice, that cost never appears on a budget sheet, never gets reviewed, and never gets questioned.
Running It Yourself
3–8 hours of your time per month
Software subscription (often underused)
Keeping up with legislative changes yourself
Error risk falls entirely on you
Revenue compliance is your responsibility
No specialist cover if something goes wrong
Time away from revenue-generating activity
Outsourcing to Forti.ie
Fixed monthly cost — fully visible on your P&L
RPN management included
ERR submissions handled
PRSI and BIK compliance checked
My Future Fund / NAERSA submissions
Legislative updates applied automatically
Expert support if Revenue queries arise
RUNNING IT YOURSELF
3–8 hours of your time per month
Software subscription (often underused)
Keeping up with legislative changes yourself
Error risk falls entirely on you
Revenue compliance is your responsibility
No specialist cover if something goes wrong
Time away from revenue-generating activity
OUTSOURCING TO FORTI.IE
Fixed monthly cost — fully visible on your P&L
RPM management included
ERR submissions handled
PRSI and BIK compliance checked
My Future Fund / NEARSA submissions
Legislative updates applied automatically
Expert support if Revenue queries arise
The Error Cost
Revenue charges interest at 0.0219% per day on underpaid tax — approximately 8% per year. That’s before penalties, which can reach 100% of the underpaid amount in cases Revenue determines to be careless or deliberate. Payroll errors rarely affect one month. They tend to compound — the same incorrect PRSI class running for 12, 24, or even 36 months before being caught.
A single misfiled PRSI class on a director’s salary of €80,000 — Class A instead of Class S — can create a liability running to several thousand euro, plus interest, by the time it surfaces.
The Compliance Cost
Irish payroll law changes frequently. The 2024–2026 period alone has brought PRSI rate increases, the launch of My Future Fund, new ERR requirements, updated BIK rules for employer-provided meals, changes to the small benefit exemption, statutory sick pay obligations, and increases to the National Minimum Wage (now €14.15 per hour from January 2026). Keeping pace with all of this while running a business is a genuine challenge.
When something is missed, the cost typically isn’t the payroll error itself — it’s the Revenue intervention that follows, and the professional fees required to manage it.
The Statutory Sick Pay (SSP) Consideration
Ireland’s Statutory Sick Pay scheme introduced a new employer obligation: as of 2024, employers must pay employees a minimum of 5 days of statutory sick pay per year at 70% of their normal daily wage (capped at €110 per day). The scheme was designed to increase to 10 days by 2025, subject to Government review. These payments must be correctly processed through payroll. Many in-house operators are either unaware of this obligation or unsure how to apply it correctly alongside their existing sick pay arrangements.
The Bottom Line
Before deciding to keep payroll in-house, do a genuine cost-benefit analysis that includes your own time, the realistic risk of errors, and the cost of staying current with Irish payroll law. For most SMEs with five or more employees, outsourcing to a specialist is both cheaper and lower-risk than the alternative.
PRSI Classes Explained — Are You Categorising Your Employees Correctly?
Pay Related Social Insurance (PRSI) is one of the most commonly misunderstood elements of Irish payroll. The class assigned to each worker determines how much they — and their employer — contribute to the Social Insurance Fund, and it determines their entitlement to state benefits including the State Pension, Jobseeker’s Benefit, Maternity Benefit, and the new pay-related Jobseeker’s Benefit scheme.
There are 11 PRSI classes. Most private sector employees fall into Class A. But the exceptions matter enormously, and getting them wrong creates a liability that can run for years before anyone notices.
Class
Who It Applies To
Employee Rate (2026)
Employer Rate (2026)
Key Benefits Covered
A Most Common
Employees in private sector earning €352/week
4.2%
11.25% / 9%
Full range incl. State Pension (Contributory)
J
Employees earning ≤€352/week; employees aged 66+;
some occupational categories
Officeholders (e.g. non-exec directors, MEPs);
certain unearned income
4.2%
0%
No benefits
M
Employees/self-employed with no PRSI liability
(nil contribution)
0%
0%
No benefits
B, C, D
Most public servants recruited before 6 April 1995
(civil servants, Gardaí, Army)
Lower modified rates
Lower modified rates
State Pension (Non-Contributory) route;
no Jobseeker’s Benefit
H
Permanent Defence Forces officers recruited
after 6 April
Full rate
Full rate
Full range
*9% applies where weekly earnings are ≤€552; 11.25% applies above that threshold. From 1 October 2026, rates increase to 4.35% (employee) and 11.40% / 9.15% (employer).
The Proprietary Director Problem
This is the single most common and expensive PRSI classification error in Irish SMEs. A proprietary director is defined as a director who, alone or with a spouse and/or minor children, owns or controls more than 15% of the ordinary share capital of a company.
Proprietary directors must be on Class S — not Class A — for the income they receive from that company. Class S means the director pays PRSI at 4.2% on their own account but there is no employer PRSI contribution. This is frequently mishandled in two ways:
Coding a proprietary director as Class A: The employer incorrectly pays 11.25% PRSI on the director’s salary. This results in overpayments to the Social Insurance Fund — and creates complexity when the error is eventually identified and needs to be unwound.
Treating a salaried director who is not a proprietary director as Class S: They should actually be Class A. This leads to underpayments and the director losing entitlement to Class A benefits like Illness Benefit and Jobseeker’s Benefit.
High Risk Area
Revenue and the Department of Social Protection cross-reference payroll data and PRSI records. Incorrect director PRSI classification is frequently identified during compliance checks. Back contributions plus interest can run to significant sums, particularly for companies that have been trading for several years.
The Class J Threshold — Critical for Part-Time and Seasonal Workers
Employees earning €352 or less per week should be on Class J, not Class A. This applies regardless of whether they are full-time or part-time, temporary or permanent. However — and this is important — if an employee works in a week where their earnings exceed €352, they revert to Class A for that week. Payroll must handle this dynamically, week by week.
A sliding scale PRSI credit applies for weekly earnings between €352 and €424 — up to €12 per week. This credit reduces the PRSI liability for lower-paid workers and must be correctly applied.
PRSI and My Future Fund: What’s Connected?
My Future Fund (auto-enrolment) eligibility is based on income and age — not PRSI class. However, both PRSI classification and My Future Fund enrolment are employer obligations that must be correctly maintained through payroll. An employee on Class J who earns over €20,000 annually and meets the age criteria may still be eligible for My Future Fund even though they’re not on Class A PRSI.
Action Point
Review every worker on your payroll — employees, directors, and part-timers. Confirm each person’s PRSI class against their actual employment status and shareholding. If any directors are approaching or above the 15% shareholding threshold, take professional advice before the next payroll run. The cost of getting this right now is a fraction of the cost of unwinding it after a Revenue compliance check.
What Every Irish Employer Needs to Know About the Enhanced Reporting Requirements (ERR)
The Enhanced Reporting Requirements (ERR) came into force on 1 January 2024 and represent one of the most significant expansions of employer reporting obligations since PAYE Modernisation itself. Despite being well into their second year, many Irish employers — particularly smaller SMEs — are still not fully compliant.
ERR requires employers to report certain non-taxable payments to employees to Revenue in real time — on or before the date the payment is made. The key word is non-taxable. Many employers assume that because a payment isn’t subject to PAYE, USC, or PRSI, Revenue doesn’t need to know about it. Under ERR, they do.
What Payments Must Be Reported Under ERR?
The three categories currently covered by ERR are:
Category
What’s Covered
Current Limit / Rate
Notes
Travel & Subsistence
Civil service mileage rates paid for business travel;
subsistence payments for overnight stays and day trips
Revenue civil service rates
(updated periodically)
Payments must not exceed Revenue-approved rates
to remain non-taxable
Remote Working Daily Allowance
Tax-free payments made to employees
working from home
€3.20 per remote working day
Employee must be working from home —
no hybrid or in-office on that day
Small Benefit Exemption
Non-cash benefits such as gift vouchers,
retail vouchers, experience days
Up to €1,500 per employee per year;
maximum 5 qualifying benefits
Must be non-cash; benefit cannot be a cash payment
or cash equivalent directly redeemable for cash
How Do You Submit an ERR Report?
ERR reports are submitted through the same channel as your standard Payroll Submission Request — via your payroll software or Revenue Online Service (ROS). Unlike the PSR, which captures taxable payroll data, ERR is submitted as a separate return specifically for the non-taxable payments listed above. The deadline mirrors the PSR: on or before the date of payment.
Not all payroll software platforms support ERR natively. If yours doesn’t, or if you’re running payroll manually, you’ll need to file ERR separately through ROS. This is one of the more practical arguments for using a managed payroll service — ERR compliance is included as standard.
What Happens If You Don’t Comply?
Revenue initially adopted an educational stance when ERR launched, signalling a transitional period. That period is now over. Revenue is actively monitoring ERR compliance and has the power to treat failure to report as a PAYE compliance risk. In practice, non-compliance is increasingly flagging businesses for closer scrutiny of their overall payroll compliance — not just the ERR payments themselves.
Common ERR Errors to Avoid
Reporting expenses after payment: ERR is real-time. If you pay travel and subsistence on the 15th, the ERR must be filed by the 15th — not at the end of the month with payroll.
Confusing taxable and non-taxable travel payments: ERR is real-time. If you pay travel and subsistence on the 15th, the ERR must be filed by the 15th — not at the end of the month with payroll.
Treating cash payments as small benefit exemptions: The small benefit exemption covers non-cash benefits only. Gift vouchers are fine. A cash bonus is not, regardless of the amount.
The Fix
Conduct an immediate audit of all non-cash employee payments made in 2026. Confirm whether your payroll software supports ERR submission. If it doesn’t — or if ERR is an afterthought in your payroll process rather than an integrated step — consider a managed payroll solution that handles ERR compliance as part of the standard monthly service.
Employing Your First Member of Staff in Ireland? Here’s What You Need to Sort
Taking on your first employee is one of the most significant milestones for any Irish business. It’s also one of the most common points at which payroll compliance breaks down — not through negligence, but because there’s simply a lot to set up, and the sequence matters. Get the foundations right from day one and payroll runs smoothly. Miss a step and you’re unravelling it later under pressure.
Here is everything you need to have in place before paying your first employee in Ireland in 2026.
1. Register as an Employer with Revenue
Before you pay anyone, register as an employer using Revenue’s Online Service (ROS) or myAccount. You’ll receive an Employer Registration Number (ERN). Without this, you cannot process PAYE, PRSI, or USC, and you cannot receive RPNs for your employees. Registration is free and can typically be done in 24–48 hours, though it’s wise to allow a week.
2. Obtain Your Employee’s PPSN and RPN
Ask your employee for their Personal Public Service Number (PPSN). Once they’ve registered the employment with Revenue (via myAccount), Revenue will generate a Revenue Payroll Notification (RPN) which tells you their tax credits, cut-off points, and USC bands. Without a valid RPN, you must apply emergency tax — which means your employee pays significantly more tax until the RPN is received.
3. Issue a Written Contract of Employment
Under the Terms of Employment (Information) Acts, you must provide a written statement of core employment terms within five days of starting employment. A full written contract — covering pay, hours, leave entitlements, notice periods, and sick pay arrangements — is strongly recommended and must be provided within one month. Failure to do so creates an unfair dismissal and employment claims risk, separate from payroll compliance.
4. Set Up Payroll Software or a Managed Service
You are legally required to maintain detailed payroll records and submit PSRs and ERR reports to Revenue in real time. Manual spreadsheets are not compliant with this obligation. You need either Revenue-approved payroll software or a managed payroll provider. Payroll software must be capable of RPN retrieval, PSR submission, ERR filing, and — for eligible employees — My Future Fund NAERSA submissions.
5. Pay at Least the National Minimum Wage
The National Minimum Wage in Ireland from 1 January 2026 is €14.15 per hour for employees aged 20 and over. Sub-minimum rates apply for employees under 20, though these have been converging with the full rate as part of Government policy. Paying below the minimum wage exposes you to a claim before the Workplace Relations Commission (WRC) and can result in significant awards.
6. Understand PAYE, USC, and PRSI Deductions
Three deductions apply to most employees: Income Tax (PAYE) at 20% on the standard rate band and 40% above it; the Universal Social Charge (USC) applied in bands (0.5%, 2%, 3%, 8%); and PRSI at 4.2% (Class A employees in 2026). As an employer, you also pay Class A employer PRSI at 11.25% (above €552/week) or 9% (at or below €552/week) — this is your cost, on top of gross salary.
7. Assess My Future Fund (Pension Auto-Enrolment) Eligibility
If your new employee is aged 23–60, earns over €20,000 per year, and is not already contributing to a workplace pension through payroll, they must be enrolled in My Future Fund from 1 January 2026. You are required to register on the NAERSA employer portal, set up a payment method, and process contributions through payroll. In 2026, both you and the employee contribute 1.5% of gross salary, with the State adding €1 per €3 saved. Contributions apply to gross earnings up to €80,000.
8. Issue Payslips
Under the Payment of Wages Act, you must provide a written or electronic payslip for every pay period. The payslip must show gross pay, all deductions (PAYE, USC, PRSI, pension contributions), and net pay. Failure to provide compliant payslips is an offence and can result in WRC complaints.
9. Know Your Statutory Leave Obligations
From day one of employment, employees accrue statutory annual leave entitlements, public holiday entitlements, statutory sick pay rights (5 days per year at 70% of normal daily wage, capped at €110/day), and parental leave rights. These must be factored into payroll planning from the start — and any leave pay must be correctly calculated and reported.
First Employee Checklist Summary
Register as employer with Revenue → Get employee PPSN → Pull RPN → Issue contract → Set up payroll system → Confirm NMW compliance → Assess My Future Fund eligibility → Register on NAERSA → Provide payslips from day one → Record statutory leave entitlements.
Payroll Compliance in Ireland — What a Revenue Audit Could Uncover
Nobody wants a Revenue knock on the door. But understanding what a payroll audit looks like — how it’s triggered, what auditors look for, and what the consequences are — is one of the most valuable things an employer can know. Because the businesses who come through audits cleanly aren’t the ones who got lucky. They’re the ones who treated payroll as a compliance function, not an afterthought.
How Revenue Identifies Payroll Compliance Issues
Revenue’s PAYE Modernisation system generates real-time data on every employer’s payroll submissions. This gives Revenue unparalleled visibility into patterns, anomalies, and inconsistencies — far more than the old annual P35 return ever provided. The following patterns are known to trigger closer scrutiny:
Repeated late PSR submissions
Significant differences between reported payroll and a business’s VAT turnover (suggesting undisclosed cash wages)
PRSI class patterns that don’t match industry norms (e.g. a construction company with many employees on Class S)
No BIK reported on benefits typically associated with the business type (e.g. a car dealer with no company vehicle BIK)
Missing or incomplete ERR submissions
Employer PRSI contribution amounts that seem inconsistent with reported headcount
Significant changes in payroll without corresponding changes in the business’s turnover or VAT profile
Area Examined
Common Issues Found
PRSI classifications
Proprietary directors on Class A;
part-timers on wrong class
Benefits in Kind
Undeclared company cars, health insurance,
preferential loans
Contractor payments
Bogus self-employment; contractors who should
be employees
Dividends used to avoid PRSI;
benefits not processed through payroll
My Future Fund
Non-enrolment of eligible employees;
incorrect contribution processing
Payslip compliance
Failure to provide compliant payslips
to all employees
Employment records
Incomplete records; cash payments
without PAYE processing
Interest and Penalties — The Real Numbers
Revenue charges interest on underpaid tax and PRSI at a rate of 0.0219% per day — equivalent to approximately 8% per year. This interest runs from the date the payment was due, not the date it was discovered. A PRSI underpayment running for three years accrues roughly 24% in interest alone, before any penalties are applied.
Penalties on top of the underpayment and interest can reach:
Up to 3% of the tax/PRSI underpaid — for minor, non-deliberate errors
Up to 20% — for carelessness
Up to 40% — for deliberate non-compliance
Up to 100% — for serious deliberate non-compliance (with publication on Revenue’s list of tax defaulters)
These penalties are negotiable — but only within the qualifying disclosure framework, and only before Revenue makes contact.
The Qualifying Disclosure: Your Best Protection
A qualifying disclosure is a voluntary declaration to Revenue of a tax or PRSI underpayment, made before Revenue contacts the taxpayer about that specific issue. Making an unprompted qualifying disclosure:
Reduces penalties to 3% (minor errors) or 10–20% (more serious) instead of up to 100%
Avoids publication on Revenue’s defaulters list
Demonstrates good faith, which materially affects how Revenue handles the overall case
Gives you control over the timeline and resolution of the issue
Revenue can look back four years for innocent errors, and further for fraud or neglect. If you identify a payroll error today — even one that goes back several years — making a qualifying disclosure before Revenue contacts you is almost always the right course of action.
What to Do If You Suspect a Payroll Error
Don’t ignore it and hope for the best. Conduct an internal review, quantify the underpayment, and take professional advice before making any contact with Revenue. A qualified payroll professional or tax advisor can help you structure a qualifying disclosure correctly, minimise penalties, and manage the resolution process. The sooner you act, the lower the cost.
The Difference Between an Employee and a Contractor in Ireland — And Why It Matters for Payroll
The distinction between an employee and a self-employed contractor is one of the most consequential — and most frequently misapplied — in Irish employment and tax law. Getting it wrong doesn’t just create a payroll problem. It creates a PRSI liability, a PAYE liability, and potentially an employment rights liability, all at once.
Revenue has made bogus self-employment a compliance priority in recent years, and for good reason. The misclassification of employees as independent contractors denies the state PRSI contributions, denies employees social welfare entitlements they haven’t been contributing to, and typically reduces the cost base for the engaging business in ways that undercut competitors who properly employ their staff.
The Code of Practice on Determining Employment Status
The legal framework for employment status in Ireland is the Code of Practice on Determining Employment or Self-Employment Status of Individuals, produced jointly by Revenue, the Department of Social Protection, and the WRC. The Code is built around a series of indicators — no single factor is decisive, but together they determine whether a working relationship is one of employment or self-employment.
Factor
Points to Employment
Points to Self-Employment
Control
Employer controls when, where, and how work is done
Worker controls their own methods and schedule
Substitution
Must personally perform the work
Can send a substitute to do the work
Equipment
Employer provides tools, equipment, workspace
Worker provides their own tools and equipment
Financial risk
Paid regardless of outcome; no risk of loss
Bears risk of profit and loss from the work
Integration
Integrated into business — attends meetings,
has email, business card
Provides a service to the business from the outside
Exclusivity
Works exclusively or almost exclusively
for one client
Works for multiple clients simultaneously
Duration
Open-ended, ongoing engagement
Defined project with clear end date
Benefits
Receives holiday pay, sick pay, pension
No employment benefits received
What Are the Consequences of Misclassification?
If Revenue or the WRC determines that someone you treated as a contractor was actually an employee, the consequences can be severe:
Back PAYE and USC on all payments made to the “contractor” — often going back four years
Back employer and employee PRSI contributions — at Class A rates, calculated on all payments
Interest on all of the above at 0.0219% per day from the date each payment was due
Penalties of up to 100% of the tax underpaid
Employment rights claims from the individual — unfair dismissal, annual leave, redundancy
Potential publication on Revenue’s defaulters list for serious cases
The “Personal Service Company” Complexity
Some contractors operate through their own limited company — a common arrangement in Irish IT, finance, and construction. This doesn’t automatically resolve the employment status question. If the substance of the arrangement is that the individual performs work exclusively for one client, under the client’s direction, the Code of Practice may still conclude that the individual is effectively an employee of the client. Revenue has actively pursued this area, particularly in sectors where contractor structures are prevalent.
How to Protect Your Business
Risk Mitigation Steps
1. Apply the Code of Practice before engagement: Before engaging any individual as a contractor, work through the Code of Practice indicators. If the majority point toward employment, treat them as an employee.
2. Review existing contractor arrangements: If you have contractors who have been working exclusively for you for more than six months, under your direction, using your equipment, they likely fail the self-employment test. Restructure the arrangement now rather than waiting for Revenue to find it.
3. Document the basis for self-employment status: Keep a written record of why each contractor was determined to be self-employed. This is useful evidence in the event of a dispute.
4. Take professional advice on grey areas: Many contractor arrangements are genuinely ambiguous. A payroll or tax specialist can help you assess the risk and, where necessary, restructure the engagement correctly.
Year-End Payroll Checklist for Irish Employers
Year-end payroll is a critical compliance event for every Irish employer — and since the introduction of PAYE Modernisation, it looks very different from the old days of a single P35 return. The good news is that if you’ve been running a clean, compliant payroll throughout the year, the year-end process is largely a reconciliation rather than a discovery exercise. The bad news is that for many SMEs, year-end is when the chickens come home to roost.
Use this checklist to work through the key year-end obligations and ensure your business enters the new year in full compliance.
1. Finalise and Reconcile Payroll for the Tax Year
Reconcile your total payroll spend — gross pay, PAYE, USC, employee PRSI, and employer PRSI — against your payroll software records and bank payments for the year. Any discrepancies between what was deducted, what was submitted to Revenue via PSR, and what was actually paid over through P30 monthly remittances need to be identified and resolved before the year closes.
Submit a final PSR (marked as final for the tax year) for your last payroll run of the year. This signals to Revenue that the payroll year is complete for your business.
2. Issue Employment Detail Summaries (the P60 Equivalent)
Since the end of P60s in 2019, employees can access their own income and tax details for the year via Revenue’s myAccount portal — this is known as the Employment Detail Summary (EDS). As an employer, you don’t issue a physical document, but you should ensure all your PSR submissions for the year are accurate, because the EDS is generated directly from your payroll data. Any errors in your submissions will create incorrect EDS figures for your employees — and they will come back to you.
Communicate to your employees at year-end that they can access their EDS (and make a request for a PAYE reconciliation if they believe they’ve overpaid tax) via myAccount. This is a simple but appreciated act of good employee communication.
3. Declarations and Valuations for Benefits in Kind
December is the time to finalise your Benefits in Kind position for the year. This includes:
Company vehicles: Calculate the annual BIK value based on the original market value (OMV) and business use percentage. The BIK rate applied depends on the vehicle’s CO₂ emissions band and, for electric vehicles, its range. BIK on company vehicles must be reported through payroll.
Private health insurance: The employer’s cost of private health insurance for an employee (and their family, if covered) is a BIK. Ensure the annual premium has been correctly included in the employee’s gross income for the year.
Employer-provided accommodation: Where an employer provides rent-free or subsidised accommodation, the taxable value must be calculated and processed through payroll.
Preferential loans: Loans provided to employees at below Revenue’s specified interest rate create a BIK equal to the notional interest saving.
Small benefit exemption review: Confirm that all gift vouchers and non-cash benefits provided during the year stay within the annual €1,500 cap and the 5-benefit maximum. Any excess over the limit becomes taxable and must be processed through payroll.
4. Holiday Pay Reconciliation
Employees are entitled to a minimum of 4 weeks’ annual leave per year (or 8% of hours worked, whichever is less, for part-time workers). At year-end, reconcile leave taken against leave accrued for each employee. Any accrued but untaken annual leave that is carried over — or paid out, where your employment contracts provide for this — must be handled correctly in payroll.
Importantly, under the Organisation of Working Time Act, the method for calculating annual leave pay must reflect the employee’s normal weekly earnings — including regular overtime, shift premium, and similar recurring payments. Annual leave calculated on basic pay alone, where the employee regularly earns more, will be incorrect and may give rise to a WRC complaint.
5. Review and Verify My Future Fund Contributions
For the 2026 year-end, you should reconcile all My Future Fund contributions processed through payroll during the year. Confirm that:
All eligible employees (aged 23–60, earning >€20,000, not in an existing pension via payroll) were enrolled from their eligibility date
Employee contributions of 1.5% and employer contributions of 1.5% were correctly deducted and remitted to NAERSA each pay period
Any employees who opted out during their opt-out window (months 6–8) were correctly processed
New employees who became eligible during the year were enrolled at the correct point
Contribution records match the NAERSA portal statements
6. ERR Annual Review
Review all ERR submissions made during the year. Confirm that travel and subsistence payments, remote working allowances, and small benefit exemptions were all reported correctly and on time. If any payments were made but not reported under ERR, consider whether a voluntary correction is appropriate before Revenue identifies the gap.
7. Prepare for the January PRSI Rate Update (October 2026)
While not a year-end task in the traditional sense, budget preparation for 2027 must account for the PRSI rate increase on 1 October 2026: employer PRSI rises to 11.40% (higher band) and 9.15% (lower band); employee PRSI rises to 4.35%. Model the cost impact on your total payroll bill before setting headcount and salary budgets for the year ahead.
Payroll Checklist
✓
Final PSR submitted and marked as year-end
✓
PSR data reconciled to bank payments and P30 remittances
✓
All employee EDS figures checked for accuracy
✓
BIK valuations finalised and processed through payroll
✓
Annual leave accrual and outstanding balances reconciled
✓
My Future Fund contributions reconciled with NAERSA records
✓
ERR submissions reviewed and any gaps remedied
✓
Statutory sick pay records reconciled for the year
✓
All contractor payments reviewed for employment status risk
✓
Director PRSI classifications confirmed for the coming year
✓
October 2026 PRSI rate increases budgeted for
✓
Payroll records retained (minimum 6 years)
Record Retention
Irish employers are required to retain payroll records for a minimum of 6 years following the end of the tax year to which they relate. This includes payslips, PSR submissions, RPN records, ERR filings, BIK workings, expense claims, employment contracts, and My Future Fund contribution records. Revenue can request these during a compliance check or audit. Digital records are acceptable provided they are accurately maintained and accessible.
Frequently Asked Questions About Irish Payroll 2026
Q1. What are the current tax credits for employees in Ireland in 2026?
In 2026, both the Personal Tax Credit and the Employee (PAYE) Tax Credit are €2,000 each, giving most employees a combined credit of €4,000 per year. These credits reduced tax liability by €4,000 per year, effectively meaning the first €20,000 of income (at the 20% rate) is tax-free for a standard PAYE employee. There were no changes to income tax rates, bands, or the main tax credits in Budget 2026.
Q2. What is the employer PRSI rate in Ireland in 2026?
From 1 October 2025, the Class A employer PRSI rates are: 11.25% for employees earning more than €552 per week, and 9% for employees earning €552 or less per week. Employee PRSI (Class A) is 4.2%. From 1 October 2026, these increase to 11.40% / 9.15% (employer) and 4.35% (employee) as part of a multi-year increase schedule legislated to fund the Social Insurance Fund.
Q3. What is My Future Fund and who does it apply to?
My Future Fund is Ireland’s mandatory pension auto-enrolment scheme, which launched on 1 January 2026. It applies to employees aged 23–60 who earn more than €20,000 per year and are not already contributing to a workplace pension through payroll. In 2026, employees and employers each contribute 1.5% of gross salary, and the State adds €1 for every €3 saved. Contributions apply to gross earnings up to €80,000. Employers must register on the NAERSA portal and process contributions through payroll. Employees can opt out between months 6 and 8 but will be automatically re-enrolled every two years if they remain eligible.
Q4. What is the Enhanced Reporting Requirement (ERR)?
ERR, in force since 1 January 2024, requires employers to report certain non-taxable payments to Revenue in real time, on or before the date of payment. The three categories covered are: travel and subsistence payments (within Revenue’s civil service rates), the remote working daily allowance (€3.20 per day), and the small benefit exemption (non-cash benefits up to €1,500 per employee per year, maximum 5 benefits). ERR is filed separately from the PSR, through payroll software or ROS.
Q5. What PRSI class should a proprietary director be on?
A proprietary director — one who owns or controls more than 15% of the company’s share capital (alone or combined with a spouse/civil partner and minor children) — must be on Class S PRSI for income received from that company. Class S: employee contribution is 4.2%; employer contribution is 0%. This is one of the most common and costly payroll errors in Irish SMEs. Class S provides limited social welfare coverage compared to Class A — it does not cover Jobseeker’s Benefit or Illness Benefit, for example.
Q6. What is the National Minimum Wage in Ireland in 2026?
From 1 January 2026, the National Minimum Wage for employees aged 20 and over is €14.15 per hour. This applies to most employees, including full-time, part-time, temporary, casual, and seasonal workers. Employers in sectors with a Joint Labour Committee (JLC) registered employment agreement may be subject to higher sectoral minimum rates. Sub-minimum rates apply for employees under 20, though the gap has been narrowing.
Q7. How far back can Revenue audit payroll records?
Revenue can go back 4 years for innocent errors in payroll records. Where fraud or neglect is involved, there is no fixed time limit. Payroll records must be retained for a minimum of 6 years following the relevant tax year. Making an unprompted qualifying disclosure before Revenue contacts you significantly reduces penalties — from up to 100% of the underpayment down to 3–20%, depending on the nature of the error.
Q8. What is the difference between an employee and a self-employed contractor in Ireland?
Employment status in Ireland is determined using the Code of Practice on Determining Employment or Self-Employment Status of Individuals. Key factors include: who controls when, where, and how the work is done; whether the person can send a substitute; whether they supply their own equipment; whether they bear financial risk; and whether they work for multiple clients. No single factor is conclusive. If Revenue determines a contractor relationship is actually employment, the employer faces back PAYE, back PRSI, interest, and penalties — in addition to potential employment rights claims.
Q9. Do I need to report meals I provide to staff through payroll in 2026?
From 1 October 2025, meals provided by an employer to all employees on the employer’s premises, eaten on site, are no longer treated as a taxable Benefit in Kind. Working lunches or dinners on site provided for genuine business reasons are also excluded. This is a welcome simplification for many employers. However, selective arrangements (e.g. meals only for certain employees), off-site meals, or vouchers/allowances for food are likely to remain taxable BIK and must be processed through payroll accordingly.
PAYE Modernisation, My Future Fund, ERR, PRSI classifications, BIK reporting — managed payroll from Forti.ie covers every obligation, every month, so you can focus on your business.
This article is intended for general educational purposes only and does not constitute professional tax, legal, or accounting advice. Figures and rates are accurate as of May 2026 based on publicly available Revenue guidance, Budget 2026 measures, and current Irish legislation. Tax law and Revenue guidance change regularly — readers should always verify current rates with Revenue.ie or consult a qualified Irish accountant, tax advisor, or payroll professional for advice specific to their circumstances. Forti.ie accepts no liability for decisions made solely on the basis of this article.
Structural Changes
If your company structure changes, we handle all required CRO filings and statutory updates. Includes:
Director appointments or resignations
Share transfers or allotments
Company name changes
We ensure your company records remain accurate and legally compliant.
Strike
If you decide to close your company, we manage the full voluntary strike-off process, including compliance review, documentation, and filing with the Companies Registration Office (CRO), ensuring the company is properly and safely dissolved.
Additional CRO Filings
Director changes, share transfers, share allotments, company name changes or other statutory updates.
RBO Filing / Ownership Updates
Required whenever shareholders or beneficial ownership changes (25%+). We prepare and submit the update to the Central Register to keep your company compliant
Registered Office Address
Secure and reliable registered office solution to improve your business reputation. This add-on service provides an official business address for company registration and ensures important business correspondence is handled professionally. Includes:
Official registered business address
Use for company registration
Handling of business correspondence
Professional business presence
Reliable address for official records
Full Company Secretary Service
Our full company secretary service ensures your company adheres to corporate governance standards. This includes maintaining statutory registers, filing annual returns, handling board resolutions, and advising on legal compliance. By outsourcing this service, you can reduce administrative workload and ensure your company avoids compliance-related risks.
Register of Beneficial Owners (RBO) Filing / Update
Every Irish company must file and maintain accurate beneficial ownership details with the Central Register of Beneficial Owners (RBO). Our service includes:
Preparation and electronic filing with the Central RBO
Review of 25%+ ownership or control thresholds
Confirmation of submission for your records
Required within 5 months of incorporation and whenever shareholding changes. Failure to file can result in significant penalties — we ensure your company remains fully compliant.
Strike Off
If you need to close your company — whether within the first year or later — we manage the entire voluntary strike-off process professionally and compliantly. Our team handles:
Director resolutions and required documentation
Pre-strike-off compliance review
Preparation and filing with the Companies Registration Office (CRO)
We ensure your company is properly wound down to avoid delays, penalties, or future compliance issues.
Please note: CRO filing fee and required newspaper advertisement costs are separate.
Digital Marketing Services (Free Consultation)
Reaching your audience effectively is key to growth. This free consultation introduces startups and small businesses to digital marketing strategies, including social media management, search engine optimisation (SEO), and online advertising, tailored to your industry and goals.
Introduction to Website Development Company (Free)
Building a strong online presence is vital for any business. This free service connects you with experienced website development companies, offering startups and small businesses tailored consultations to help establish or upgrade their online platforms.
Modern businesses thrive on effective communication. This service provides VoIP phone solutions and professional call answering with calendar management and call forwarding. It ensures no business opportunities are missed while projecting a professional image to clients and partners.
6-Month Annual Return Filing
Filing the first Annual Return (B1) is an important requirement to keep your company compliant and in good standing. This service includes the preparation, filing, and management of all required documents for the year, such as financial statements, shareholder reports, and any necessary changes to the company structure. It allows you to focus on growing your business while ensuring your obligations are met. Includes:
Preparation and electronic filing
Deadline monitoring
Audit exemption protection
This filing is required even if no financial statements are due.
Annual Return Filing per Year
Annual returns are essential for keeping your company information up-to-date with the Companies Registration Office (CRO). This service ensures that all required information, such as directors, shareholders, and company financials, is filed accurately and on time, avoiding late penalties and maintaining good standing.
Annual Compliance Support
Annual compliance is critical for avoiding fines and maintaining good standing with regulatory authorities. This service includes the preparation, filing, and management of all required documents for the year, such as financial statements, shareholder reports, and any necessary changes to the company structure. It allows you to focus on growing your business while ensuring your obligations are met. Includes:
Annual Return (B1) filing
Statutory register maintenance
Deadline tracking
Audit exemption monitoring
Compliance advisory support
Ideal for directors who want ongoing professional oversight.
Annual Return (B1) Filing
Preparation and filing of yearly CRO Annual Return (after year one).
Helps maintain good standing and avoid late filing penalties.
Full Company Secretary Service
Our full company secretary service ensures your company adheres to corporate governance standards. This includes maintaining statutory registers, filing annual returns, handling board resolutions, and advising on legal compliance. By outsourcing this service, you can reduce administrative workload and ensure your company avoids compliance-related risks.
Historical filing and bookkeeping services are for businesses that have gaps in their financial year filings. We will require this information for compliance and reporting purposes, regardless of the gap duration.
Manage Annual Returns Deadline (Included)
File Annual Return in CORE (Included)
File PDF Financial Statements in CORE File Manager (Included)
Signing Annual Return and Bank Application Documents (Included (Limited)**)
Company Secretarial Paperwork Filing (Included)
Maintaining and Updating Company Registers (Included)
Drafting Minutes for Board Meetings (AGM Included) (Included)
Ongoing Company Secretarial Advice (Annual Limit) (Up to 300 minutes)
Countersignatures for Company Bank Applications/Reports (Not Included)
Traditional phone systems are transformed by VoIP (vocal over Internet Protocol) technology, which facilitates vocal communication over the internet. This technology is extensively employed in cloud-based phone services. The latest technology provides businesses with substantial advantages, such as seamless integration with a variety of digital tools and increased flexibility. Our call answering services ensure that you never miss an important call. We ensure that your business’s communication is both efficient and effective by managing your diary, receiving inquiries, and forwarding them to you.
Our Business Address Service will improve your company’s corporate image by providing a prestigious address for your correspondence. We will forward your business correspondence to an alternative address of your choosing via post for a nominal fee of €55 per month. This service is renewable annually, with an additional fee for forwarding general business correspondence.
If you need cloud based phone services, enquire now.
Company Formation
Includes CRO Filing Fee for Private Limited Company or DAC.
Manage Annual Returns Deadline (Included)
File Annual Return in CORE (Included)
File PDF Financial Statements in CORE File Manager (Included)
Signing Annual Return and Bank Application Documents (Included (Limited)**)
Company Secretarial Paperwork Filing (Included)
Maintaining and Updating Company Registers (Included)
Drafting Minutes for Board Meetings (AGM Included) (Included)
Ongoing Company Secretarial Advice (Annual Limit) (Up to 300 minutes)