Tag Archives: accounting

Self Assessment for PAYE Employees

When a Side Hustle Triggers Self Assessment for PAYE Employees

Side hustles begin quietly. You take on a freelance project after work, tutor a few clients at weekends, sell a service online, do photography jobs, create paid content or earn commission from a platform. Your main salary is already taxed through PAYE, so it is easy to assume the extra income will somehow be dealt with in the same way.

It usually will not.

Your employer only operates PAYE on the pay it gives you. Extra income earned outside that employment still has to be declared, and the way you declare it depends on how much non-PAYE income you have and what kind of activity produced it.

For many PAYE workers, the dividing line is not simply whether the side hustle made money. Revenue uses two important thresholds:

  • €5,000 of taxable non-PAYE income;
  • €30,000 of gross non-PAYE income.

Those figures decide whether a PAYE taxpayer can generally report smaller amounts through myAccount or needs to enter the self-assessment system and file Form 11.

Another point: A person who is self-employed should register for Income Tax self-assessment. So the €5,000 and €30,000 limits should not be read as a blanket exemption for every person who has started a genuine trade or business.

Start With Revenue’s Two Non PAYE Income Thresholds

You MUST register for Income Tax self-assessment where your taxable non-PAYE income exceeds the two thresholds.

Taxable non PAYE income

Taxable non-PAYE income is the amount that remains taxable after the deductions that Revenue allows for the relevant source of income. For a self-employed activity, that will usually involve calculating business income and deducting allowable business expenses before arriving at taxable profit.

A PAYE employee who earns €4,000 of taxable non-PAYE income, with gross non-PAYE income no higher than €30,000, may generally declare that income through a Form 12 in myAccount rather than becoming a chargeable person for self-assessment solely because of that income.

Once taxable non-PAYE income goes above €5,000, Form 11 becomes relevant.

The key word is “exceeds”. Revenue’s published threshold is more than €5,000, not €5,000 or more, for this particular self-assessment test.

Gross non PAYE income

The second threshold can catch people whose taxable profit looks small.

If your gross non-PAYE income exceeds €30,000, you may have to file Form 11 even where the taxable amount is below €5,000. Revenue treats the gross test separately from the taxable-income test, so you should not look at net profit alone when deciding how to file.

This is particularly relevant for side hustles with substantial costs, such as event work, reselling, production services or activities where you pay subcontractors or buy materials.

The €30,000 figure also should not automatically be treated as identical to simple bank lodgements or invoice totals. The calculation depends on the source and the tax rules that apply to that source. If your figures are close to the threshold, work from the accounts rather than estimating from cash received.

When Form 12 Is Usually Enough

A PAYE worker with modest additional income can often stay within the PAYE system for reporting purposes.

Non-PAYE income that does not exceed the €5,000 taxable and €30,000 gross limits can be declared through an online Form 12 using myAccount. Revenue can then collect the tax due by adjusting your tax credits and standard rate cut-off point. This process is often called coding the income.

That can be far simpler than registering for self-assessment where the activity is genuinely small and the Form 12 route applies.

Suppose you work full-time and make €2,800 in taxable profit from occasional freelance design work during 2026. Your gross non-PAYE income is also well below €30,000. Based on those figures alone, you are below both mandatory thresholds.

You still declare the income. The lower figure changes how it is reported, not whether it is taxable.

A small side income is still taxable income

One common misunderstanding is that earning less than €5,000 means no tax is due.

The €5,000 figure is a self-assessment filing threshold for certain PAYE taxpayers. It is not a general tax-free allowance for side hustles.

Your extra taxable income is added into your wider tax position. The actual Income Tax depends on your rate band, tax credits and personal circumstances. USC can also apply. If the activity is self-employment, PRSI may become relevant once the separate PRSI conditions are met.

So a €3,500 side profit can create a tax bill even though it may be reported through Form 12 rather than Form 11.

When You Need To Register for Self Assessment

The clearest mandatory triggers for a PAYE worker with non-PAYE income are:

  • taxable non-PAYE income above €5,000
  • gross non-PAYE income above €30,000.

Once one of those tests is met, Revenue requires self-assessment registration and a Form 11 Income Tax Return.

Revenue also lists self-employed people among those who should register for Income Tax self-assessment. That wording matters for people who have moved beyond occasional extra income and are actively carrying on a trade, profession or business.

A person can be a PAYE employee and self-employed at the same time. Your employment income continues through your employer’s payroll. Your self-employed income is dealt with separately through your own tax registration and return.

Your PAYE salary does not remove the filing obligation

Having tax deducted every month by your employer does not cancel the rules for your side business.

Form 11 brings the different parts of your income together. Revenue’s online return includes PAYE income already reported by your employer as well as sections for trading, rental, foreign and other income. The calculation then takes account of tax already paid through PAYE.

You are not being taxed twice on your salary. The return uses your full tax position to calculate what is still payable.

What Counts as Side Hustle Profit

For a typical self-employed side business, tax is based on taxable profit rather than every euro of sales.

You need records that show what you earned and what the business spent. Revenue allows deductions for expenses that meet the rules for the trade. Deductible expenses must relate to the running of the business, and mixed private and business costs must be apportioned.

That distinction can materially change the figure you report.

A freelance photographer may receive €12,000 from clients during the year and incur qualifying business costs for software subscriptions, insurance, website hosting, certain travel, professional services and equipment-related tax allowances. The taxable figure will not necessarily be €12,000.

Equally, a personal purchase does not become deductible because you also use it occasionally for the side hustle.

Expenses with both business and private use

Phone bills, motor costs and some home-related costs may have a mixed purpose. Revenue allows the business portion where the expenditure qualifies, rather than the entire cost.

If 40% of a phone plan genuinely relates to business use, you work with the supportable business share. Claiming 100% because you sometimes answer client messages on the phone would overstate the deduction.

Keep invoices, receipts, statements and a reasonable basis for any apportionment.

Capital purchases need separate treatment. Capital expenditure is not deducted in the same way as normal day-to-day business expenses, although capital allowances may be available on qualifying assets.

Your PAYE Salary Affects the Rate on Your Side Income

Your side-hustle profit is not taxed in isolation.

Ireland’s 2026 Income Tax system applies a 20% standard rate up to your available standard rate band and 40% above it. For a single person without qualifying children, the 2026 standard rate band is €44,000. Other bands apply depending on marital status and circumstances.

If your PAYE salary has already used your full 20% band, additional taxable profit may fall into the 40% Income Tax rate before credits and other adjustments.

Take a single PAYE employee earning €50,000 in 2026. Their salary already exceeds the €44,000 standard-rate band. If they then make €6,000 of taxable profit from freelance work, the extra profit is entering a tax position where the standard band has already been used.

That is why saving only 20% of side-hustle profit can leave some higher-paid PAYE workers short when the return is filed.

USC also looks at your wider income

For 2026, Revenue’s standard USC bands are:

  • 0.5% on the first €12,012
  • 2% on the next €16,688
  • 3% on the next €41,344
  • 8% on the balance.

Your exact USC treatment depends on the type and amount of income and any exemptions or special rates that apply. A side hustle can push more income into a higher USC band even when PAYE has already been deducted correctly from your salary.

PRSI has its own rules

Self-employed income can also bring Class S PRSI into the calculation.

The Department of Social Protection states that self-employed people with sufficient reckonable income generally pay Class S. For 2026, the Class S rate is 4.20% up to 30 September and 4.35% from 1 October. For people returning PRSI through the self-assessment system, the Department gives a blended 2026 rate of 4.2375%, subject to the applicable minimum contribution rules.

PRSI is generally due for a self-employed person with minimum annual income of €5,000, subject to age and exemption rules.

These thresholds and rates are separate from the €5,000 taxable non-PAYE threshold used to decide whether Form 11 is mandatory. Similar numbers appear in different rules, so use the rule that applies to the question you are answering.

Preliminary Tax Can Catch New Side Businesses Off Guard

Moving into self-assessment changes the timing of your tax payments.

Under Revenue’s Pay and File system, 31 October is the standard deadline for filing the previous year’s return, paying the balance for that previous year and paying preliminary tax for the current year.

This year, a person filing through ROS can qualify for the extended deadline of 18 November 2026 where both the 2025 Form 11 return and the appropriate payment are completed through ROS.

Preliminary tax is an advance payment towards the current year’s Income Tax, PRSI and USC liability.

Revenue allows preliminary tax to be based on at least the lowest of:

  • 90% of the tax due for the current year
  • 100% of the tax due for the immediately previous year
  • 105% of the tax due for the pre-preceding year where the direct-debit conditions apply.

The first year can work differently. Revenue says a first-year self-assessed taxpayer may choose 100% of the previous year’s liability. Where the previous year’s self-assessment liability was nil, this can mean no preliminary tax payment is required under that option in year one.

That does not make the first year’s profit tax-free. It can shift the cash pressure into the next Pay and File date, when the previous year’s balance and the new preliminary tax can arrive together.

For a growing side business, setting money aside as you earn it is usually less painful than finding the full amount later.

Three Examples That Show Where the Line Falls

PAYE employee with €3,000 of taxable freelance income

You earn a normal PAYE salary and make €3,000 taxable profit from occasional freelance work. Your gross non-PAYE income is comfortably below €30,000.

On those figures, you are below the two mandatory Form 11 thresholds. You can generally declare the additional income through Form 12 in myAccount, subject to the nature of the activity and Revenue’s registration rules.

Tax can still be due on the €3,000.

PAYE employee with €7,500 of taxable side profit

Your salary is taxed through PAYE and your separate consulting work produces €7,500 of taxable profit.

The taxable non-PAYE income is above €5,000. You must register for self-assessment and file Form 11.

The fact that consulting is done only in evenings or on occasional weekends does not reduce the amount for tax purposes. Revenue looks at the income and the nature of the activity, not the label “side hustle”.

PAYE employee with income close to the gross threshold

Your taxable profit remains below €5,000, but the gross non-PAYE figure is approaching €30,000.

Do not decide the filing method from profit alone. The gross test can independently trigger self-assessment. This is a point worth checking before year-end because registration, record keeping and preliminary-tax planning become easier when they are dealt with before the filing deadline.

Online Side Hustles Still Count

Income from online platforms is still income.

That includes activities such as paid short-term accommodation, freelance marketplace work, online sales carried on as a trade and other platform-based services. The tax treatment depends on what you are doing, how regularly you do it and whether you are trading or simply disposing of personal belongings.

Revenue receives information about certain sellers and service providers under DAC7 and related digital-platform reporting rules. Platform reporting does not create a new tax, and a platform reporting threshold is not the same thing as an Income Tax threshold.

It does make record keeping more important.

Match platform statements to your own records. Keep evidence of fees deducted by the platform, refunds, business costs and amounts actually received.

Income Tax Registration Is Not the Same as VAT Registration

A side business can have more than one tax threshold to monitor.

The Income Tax self-assessment limits discussed above determine how certain non-PAYE income is reported. VAT has separate registration thresholds.

Revenue’s current principal VAT thresholds include €42,500 for persons supplying services only and €85,000 for persons supplying goods. Different thresholds and rules apply to certain mixed supplies, EU acquisitions, cross-border distance sales and other situations.

So someone can need Form 11 without being VAT registered. Another business may need to examine VAT because of its turnover even though the owner is also a PAYE employee.

Do not use the €5,000 self-assessment figure as a VAT test.

Keep the PAYE Job and Side Business Records Separate

A second bank account is not always a legal requirement for a sole trader, but separating business transactions makes the accounts much easier to reconstruct.

At minimum, keep:

  • sales invoices and platform statements
  • receipts and supplier invoices
  • payment records
  • records of refunds
  • details supporting mixed-use expense percentages
  • equipment purchase documents
  • mileage or travel records where relevant
  • copies of tax filings and Revenue correspondence.

Your PAYE data is largely reported through payroll. The side business needs its own support.

This becomes especially important where customers pay through several channels. A person might receive Stripe payments, bank transfers and cash during the same year. Looking at one bank account in October and treating that as annual income can miss part of the picture.

6 Common Mistakes PAYE Workers Make With Side Income

1. Treating the €5,000 threshold as a tax-free amount

It is not. The threshold helps determine whether certain PAYE taxpayers must enter self-assessment. Income below it can still produce tax.

2. Waiting until Form 11 is due to work out profit

By then, receipts may be missing and mixed expenses become harder to justify. Updating the figures during the year also gives you a better estimate of the eventual tax bill.

3. Looking only at net profit

The €30,000 gross non-PAYE test exists separately. Both tests need attention.

4. Assuming PAYE has already covered everything

Your employer deducts tax on employment pay. It does not know the final profit from your freelance work, online shop or weekend business.

5. Claiming every personal cost as a business expense

Revenue requires a business connection and limits deductions for mixed-use and private costs. Keep the calculation supportable.

6. Forgetting about VAT as turnover grows

Income Tax and VAT use different rules. A business can cross one threshold long before another.

A Simple Filing Check for a PAYE Employee

Use this as a starting point for reviewing your specific activity.

Your position Likely route
PAYE income and taxable non-PAYE income of €5,000 or less, with gross non-PAYE income of €30,000 or less Declare through Form 12 in myAccount where the Form 12 route applies
Taxable non-PAYE income above €5,000 Register for self-assessment and file Form 11
Gross non-PAYE income above €30,000 Register for self-assessment and file Form 11
You have started carrying on a genuine self-employed trade or business Review self-assessment registration because Revenue lists self-employed persons among those who should register
Side-business turnover is growing Check VAT separately using the VAT rules and thresholds

Note the fourth line in particular. Income thresholds are useful, but they do not replace the question of what the activity actually is.

What To Do When Your Side Hustle Starts Making Real Money

First, work out the numbers properly. Separate gross non-PAYE income from taxable income, and keep a running record of deductible costs.

Then decide whether the activity is occasional extra income or has become a self-employed trade. Check the €5,000 and €30,000 self-assessment tests and register before filing if Form 11 is required.

After that, estimate the tax rather than waiting for Revenue’s calculation to surprise you. Your PAYE salary may already use much of your 20% rate band, so the marginal tax on extra profit can be higher than expected.

Finally, monitor turnover for VAT separately.

A side hustle can stay small for years, or it can turn into a meaningful second income within a few months. The tax administration should change when the numbers and the activity change. The useful point is knowing where that change happens.

FAQs:

Do I need to register for self-assessment if I earn money from a side hustle?

Not necessarily. If your taxable non-PAYE income is no more than €5,000 and your gross non-PAYE income is no more than €30,000, you may generally report it through Form 12 in myAccount where that route applies.

Is the €5,000 side-income threshold tax-free?

No. The €5,000 figure is a filing threshold for certain PAYE taxpayers, not a tax-free allowance. Side-hustle income can still create an Income Tax liability even when it is reported through Form 12.

When do I need to file Form 11?

You generally need to register for self-assessment and file Form 11 when taxable non-PAYE income exceeds €5,000 or gross non-PAYE income exceeds €30,000.

Does my PAYE salary affect the tax I pay on my side hustle?

Yes. Your side-hustle profit is considered alongside your PAYE income. If your salary has already used your available standard-rate band, additional taxable profit may be taxed at the higher Income Tax rate.

Do I need to consider VAT if my side business grows?

Yes. VAT has separate registration rules and thresholds from Income Tax self-assessment. You should monitor your business turnover separately as the side business grows.
VAT Registration Made Simple

VAT Registration After Crossing the Threshold

What to Do Before Your Next Invoice

Your sales have been climbing and the latest turnover figure has pushed you over the VAT threshold. That is a good sign for the business, but it creates a tax job that should not be left until the next VAT deadline.

For many Irish businesses, VAT registration becomes obligatory once annual turnover exceeds the relevant threshold. Revenue’s current VAT registration thresholds are:

  • €42,500 for businesses supplying services only;
  • €85,000 for businesses supplying goods.

There are other thresholds and exceptions, so the figure that applies to you depends on what you sell and where your customers and suppliers are based.

The first few days after crossing the threshold matter. You need to establish the correct registration position, work out the effective date, identify the VAT rate for what you sell, update your invoicing and bookkeeping, and keep enough cash aside for the first return. Sending an invoice with the wrong VAT treatment can create extra work for you and your customer later.

First Work Out Whether You Have Actually Crossed the Threshold

Turnover for VAT purposes is not the same as the amount that happened to arrive in your bank account this month. Revenue calculates annual turnover using the value of relevant supplies, excluding VAT, in a calendar year. The calculation can include taxable goods and services, supplies of immovable goods, certain financial transactions, and insurance or reinsurance services.

Some items are left out. Take the occasional disposal of a business asset such as a building, vehicle or machine. If a trader sells €70,000 of goods and also sells a delivery van for €20,000 as a once-off disposal, the van sale is disregarded for the SME threshold calculation and the relevant turnover remains €70,000.

Main Irish VAT thresholds in 2026

VAT Registration Thresholds
TYPE OF ACTIVITY THRESHOLD
Services Only €42,500
Goods €85,000
Mixed Goods And Services Where
90% Or More Of Turnover Is From
Qualifying Goods
€85,000
Certain Goods Manufactured Or
Produced From Zero-Rated Materials
€42,500
Intra-Community Acquisitions In
Relevant Cases
€10,000
Certain Cross-Border Distance Sales
Of Goods And B2B Services
€10,000

A mixed business deserves a closer look. The €85,000 threshold can apply where at least 90% of turnover comes from qualifying supplies of goods. A café, consultant who also sells equipment, trades business, online retailer or manufacturer may not fit neatly into the first category that comes to mind.

Register With Revenue As Soon As the Obligation Arises

Once you have established that registration is required, deal with the application promptly. Irish-established businesses can register through Revenue Online Service, and a tax agent can do this on your behalf. TR1 applies to individuals, sole traders, trusts and partnerships, while TR2 applies to limited companies.

The date on the registration matters more than many new VAT traders expect. Revenue states that VAT registration will generally take effect from the date shown on the registration form. Backdating can be agreed in certain circumstances. If you voluntarily elect to register while still below the threshold, the effective date cannot be earlier than the start of the taxable period in which you apply.

That is the reason not to guess which invoice should suddenly include VAT. A sale made close to the point at which your registration becomes effective may need different treatment from an earlier sale. If you crossed the threshold some time ago and only spotted it during bookkeeping, ask your accountant or Revenue to establish the correct effective date before changing historic invoices or charging customers retrospectively.

Do Not Automatically Add 23 Percent to the Next Invoice

Ireland’s standard VAT rate is 23%, but it is not the rate for every sale. From 1 January 2026, the main rates have been 23% standard, 13.5% reduced, 9% second reduced and 4.8% for livestock, alongside zero-rated supplies in qualifying categories. Check the current VAT rates and the rate that applies to the exact product or service you provide.

Suppose you provide a service that is correctly charged at 23% and your net fee is €1,000. The VAT is €230, bringing the invoice total to €1,230. If you had promised a consumer a fixed final price of €1,000 and that price now has to be treated as VAT-inclusive at 23%, the economics are very different. The net amount is about €813.01 and the VAT element is about €186.99. Your customer still pays €1,000, so the VAT comes out of the price you had expected to keep.

That pricing issue is especially important for businesses selling to private consumers, charities, exempt organisations or other customers who cannot recover all of the VAT. A VAT-registered business customer may be able to reclaim VAT on a qualifying purchase, so a net-price quote can be easier to adjust commercially. Consumer pricing often leaves much less room.

Check Your Existing Quotes and Contracts Before Rebilling

Read the wording you have already given customers. Does the quote say €2,000 before VAT, €2,000 including VAT, or simply €2,000? A contract may also specify how taxes are treated if the supplier becomes VAT registered during the engagement. The wording can determine whether VAT is added to the customer’s total or absorbed within the amount already agreed.

For recurring work, review subscriptions, retainers, standing orders and direct-debit amounts before the next billing run. If your accounting software creates invoices automatically, change the tax settings before the automation sends another batch.

Your VAT Invoice Needs More Information Than Your Old Invoice

A proper VAT invoice is not simply your previous invoice with a VAT line typed underneath.

It should include details such as the date of issue, a unique sequential invoice number, your full name and address, your VAT registration number, the customer’s name and address, a description of the goods or services, the VAT-exclusive price, the applicable rate and the total VAT payable.

The VAT invoice must generally be issued within 15 days of the end of the month in which the goods or services were supplied. The timing is particuarly key where work is completed near the month-end or where customers pay in advance.

For invoices of no more than €100, simplified invoicing may be available in qualifying circumstances. A simplified invoice still needs core information, including the issue date, supplier details and registration number, a description of the supply and the tax payable or price exclusive of tax. It cannot be used for intra-Community supplies.

Be Careful When Correcting an Invoice

Mistakes happen, especially during the first few weeks after registration. Correct them properly rather than deleting the old invoice and pretending it never existed. Where an invoice shows too much VAT, the supplier remains liable for the VAT shown until the error is corrected using the required credit-note and revised-invoice process. Where too little VAT is shown, a full credit note and revised invoice may be required.

See Revenue’s guidance on amending VAT invoices before changing an invoice that has already gone to a customer.

Set Up Your Bookkeeping Before the First VAT Return

Once VAT appears on your sales invoices, part of the money you collect is tax that may be payable to Revenue. Treating the full bank receipt as available trading cash is an easy way to create a shortfall at filing time.

Your bookkeeping system should record sales net of VAT, output VAT charged to customers, purchases, and deductible input VAT supported by valid invoices. Revenue allows VAT-registered traders to reclaim VAT on goods and services used for taxable supplies, subject to the normal restrictions.

The time limit for a VAT repayment claim is generally four years. There are costs on which VAT cannot normally be reclaimed, including entertainment and many passenger motor vehicle costs.

This is a good point to clean up receipt capture, bank feeds and invoice coding. If the business has grown quickly enough to cross the VAT threshold, bookkeeping that worked when there were ten transactions a month may become unreliable at fifty or a hundred. Our online bookkeeping information explains how cloud bookkeeping can connect sales, expenses, receipts and bank transactions in one system.

Know When Your First VAT Return and Payment Will Be Due

The standard VAT taxable period in Ireland is two months, beginning on the first day of January, March, May, July, September and November. Revenue says VAT must normally be filed and paid by the 19th day of the month after the taxable period ends. ROS filers receive an extension to the 23rd day.

Revenue may authorise four-monthly returns where annual VAT liability is between €3,001 and €14,400, and six-monthly returns where annual liability is between €1 and €3,000. Monthly returns are generally associated with traders who are regularly in a VAT repayment position. An annual Return of Trading Details is also required, breaking purchases and sales down by VAT rate.

Late payment has a measurable cost. Revenue currently charges interest on overdue VAT at 0.0274% per day, or part of a day, from the due date until the outstanding VAT is paid. Penalties can also arise for late or non-filing. The Revenue interest guidance applies even where the original error began as an administrative oversight.

Cash Flow Can Change Once VAT Registration Starts

The normal invoice basis can require you to account for VAT when you make the supply or issue the invoice, even if the customer has not yet paid you. For businesses with long payment terms, that timing can put pressure on cash.

Some VAT-registered businesses may apply to use the moneys received basis, often called the cash receipts basis. This can be available where turnover does not exceed or is not likely to exceed €2 million in a continuous 12-month period, or where at least 90% of supplies are made to customers who are not entitled to a full VAT deduction or are not VAT registered. The moneys received basis rules contain exclusions, so eligibility should be checked before changing the way you account for VAT.

Even if you stay on the normal basis, start forecasting VAT separately from corporation tax, income tax, payroll and day-to-day costs. A healthy bank balance shortly after a busy invoicing month can include a sizeable VAT amount that is already committed.

What If You Crossed the Threshold Earlier Than You Realised?

This situation is actually common. A business may grow through several small clients, marketplace sales, card transactions or a single unusually strong quarter. By the time the annual accounts are prepared, the threshold was crossed months earlier.

Do not pick an arbitrary date and start rewriting every invoice. Reconstruct your turnover by date, identify the point at which the threshold rules became relevant, and speak to your accountant or Revenue about the correct registration date and any backdating required. Revenue expressly allows VAT registration to be backdated in certain circumstances by agreement with the Revenue Office.

You may then need to correct affected invoices, calculate output VAT, review VAT that may be reclaimable on qualifying business purchases, submit outstanding returns and deal with interest where payment should have been made earlier. If customer prices were fixed as VAT-inclusive, the business may have to fund some of that historic VAT itself. That can turn a bookkeeping delay into a real margin problem.

The Domestic Threshold Is Not the Only VAT Registration Trigger

A turnover figure below €42,500 or €85,000 does not always keep a business outside the VAT system. Revenue lists separate situations involving goods and services acquired from abroad. Certain businesses that receive taxable services from abroad may have to register and account for Irish VAT irrespective of the value of those services. Relevant intra-Community acquisitions of goods have a €41,000 threshold.

Cross-border selling can add another layer. The EU VAT SME Scheme has applied since 1 January 2025. Eligible Irish businesses may use thresholds in participating Member States where they make qualifying supplies, provided the scheme conditions are met. One of the central conditions is a Union annual turnover of no more than €100,000 in the current and previous calendar year. Revenue’s EU VAT SME Scheme overview explains the separate registration and quarterly reporting requirements for businesses using the cross-border scheme.

If you sell digital services, distance-sell goods, buy services from overseas suppliers or trade with businesses elsewhere in the EU, do not rely on the domestic turnover threshold alone.

Keep the Records Behind Every VAT Figure

VAT compliance rests on records. Revenue expects full and true records of VAT-related transactions, including invoices, credit notes, receipts, accounts, bank statements and other supporting documentation. Records relevant to claims, appeals and Revenue inquiries generally need to be retained for six years, with longer retention where a matter has not been finalised.

Good records also make your first VAT return much less painful. A VAT figure that can be traced back to invoices and receipts is easier to review than a spreadsheet total assembled after the deadline is already close.

Checklist Before Your Next Invoice

  • Recalculate your calendar-year turnover and confirm the threshold that applies to your activity.
  • Separate genuine trading turnover from items that Revenue excludes from the threshold calculation, such as qualifying occasional disposals of business assets.
  • Submit the VAT registration application promptly and establish the correct effective date.
  • Confirm the VAT rate for each product or service you sell. Do not default to 23% without checking.
  • Review open quotes, contracts, retainers and consumer prices to see whether amounts are VAT-exclusive or VAT-inclusive.
  • Add your VAT registration number and the other required information to your invoice template.
  • Update accounting software, payment links, recurring invoices and e-commerce tax settings before the next billing cycle.
  • Create separate VAT bookkeeping codes for sales and purchases so input and output VAT can be reconciled.
  • Set aside VAT cash as invoices are paid rather than treating the whole receipt as operating money.
  • Put the first VAT3 deadline in the calendar and allow time to review the figures before filing.
  • If the threshold was crossed earlier, reconstruct the timeline before correcting historic invoices.
  • Review cross-border purchases and sales because they can create VAT obligations outside the normal domestic threshold rules.

If you run a limited company and your VAT registration is arriving alongside higher transaction volumes, payroll or more complex reporting, it may also be time to review the wider accounting setup. Our limited company accounting service covers VAT tracking and returns alongside bookkeeping, annual accounts and corporation tax compliance.

Get the First VAT Invoice Right

Crossing the VAT threshold is a compliance change, but it is also a pricing and cash-flow change. The work begins before the next invoice leaves your system. Establish the registration date, check the VAT rate, update the invoice properly and know how much of each customer payment belongs to Revenue.

If your turnover crossed the threshold weeks or months ago, the job is different. Rebuild the timeline first. The cost of correcting the position is usually easier to control when you know exactly which supplies, invoices and VAT periods are affected.

Irish Startup Accounting Checklist

The Irish Startup Accounting Checklist: What You Need to Get Right From Day One

Starting a Business in Ireland? Here Is What No One Tells You About Compliance

You have the idea. You have the drive. You might even have your first customer lined up.

But between registering your company and issuing your first invoice, there is a maze of compliance obligations that catches many Irish founders off guard — Revenue registrations, CRO deadlines, VAT thresholds, payroll requirements, and beneficial ownership filings. Miss one, and you are looking at penalties, surcharges, and the kind of paperwork headache that eats into time you should be spending on your business.

This guide is a plain-English walkthrough of every accounting and compliance step a new Irish limited company needs to take, in the right order, so you can focus on building rather than firefighting.

Sole trader or limited company? Almost everything below applies to Irish Private Limited Companies (LTDs). If you are trading as a sole trader, your obligations differ — particularly around income tax (Form 11 vs PAYE), legal liability and accounting requirements. If you are deciding between the two structures, speak to an accountant before you start trading. The right structure depends on your turnover, risk profile and growth plans.

Step 1: Register Your Company With the CRO

Before anything else, your business needs a legal structure. Most Irish startups incorporate as a Private Limited Company (LTD) — it gives you limited liability, a professional profile, and the ability to access business banking and contracts.

Company registration is handled by the Companies Registration Office (CRO) at cro.ie. You will need:

  • A company name — checked against the CRO register; duplicates are rejected
  • At least one director — who must be EEA-resident, or the company must hold a Section 137 bond
  • A registered office address in Ireland
  • A company secretary — note that if the company has only one director, that director cannot also act as company secretary

Annual return dates — what founders regularly miss

Your company’s first Annual Return Date (ARD) falls six months after the date of incorporation. Importantly, no financial statements are required with this first B1 return — only the form itself must be filed. Subsequent B1 returns fall annually from that ARD and must include financial statements.

Under the rules applicable since 16 July 2025, a single late annual return no longer automatically causes loss of audit exemption. A company now generally loses audit exemption for the following two years where it files late more than once within a five-year period. This is a meaningful change from the previous position, but filing on time remains strongly advisable — late filing fees apply regardless, and the consequences of repeated lateness remain serious.

Step 2: Register Your Beneficial Ownership (RBO)

This step is missed by a significant number of newly incorporated companies, and the consequences can include fines.

Within five months of incorporation, your company must register its beneficial ownership information on the Register of Beneficial Ownership (RBO) at rbo.gov.ie. A beneficial owner is generally any individual who ultimately owns or controls more than 25% of the shares or voting rights, or who otherwise exercises control over the company.

What you will need for each beneficial owner:

  • Full name, date of birth and nationality
  • Residential address
  • Nature and extent of interest held
  • PPS Number — or, where the individual does not have a PPS Number, a verified identity via the VIF (Verification of Identity Form) process

The RBO must also be updated whenever there is a relevant change in beneficial ownership. Failure to file within the deadline is an offence under the European Union (Anti-Money Laundering: Beneficial Ownership of Corporate Entities) Regulations.

Step 3: Register With Revenue

Incorporation at the CRO does not automatically register your company with Revenue. You need to register separately — via ROS (Revenue Online Service) — for each tax head that applies to your business:

  • Corporation Tax (CT) — mandatory for all Irish limited companies from the date of incorporation
  • Employer PAYE/PRSI — required as soon as you take on staff or pay a salary to a director
  • VAT — see Step 4

Revenue registration is a separate process and can take time. Delays here can hold up your VAT registration and your ability to reclaim Irish input tax, so it is worth starting early.

Step 4: Understand Your VAT Position

VAT registration is mandatory in Ireland once your turnover exceeds:

  • €85,000 for the supply of goods
  • €42,500 for the supply of services

These thresholds took effect from 1 January 2025 (increased from €80,000 and €40,000 respectively) and remain in force as of the date of this guide. You can also register voluntarily below these thresholds — which many startups do, particularly if they are selling to other VAT-registered businesses and wish to reclaim input VAT on their costs.

Cross-border and EU VAT considerations

If your company makes intra-Community distance sales of goods or supplies certain cross-border telecommunications, broadcasting or electronic (TBE) services to consumers in other EU Member States, the €10,000 annual threshold for cross-border B2C supplies is relevant. Once exceeded, VAT must be accounted for in each customer’s Member State — unless you register for the OSS (One Stop Shop) scheme in Ireland, which allows you to file all EU VAT centrally via Revenue.

EU VAT SME Scheme (from 1 January 2025): Qualifying small Irish businesses with EU-wide turnover not exceeding €100,000 may be able to use VAT exemptions in participating EU Member States, subject to national thresholds and conditions. This can offer meaningful administrative simplification for startups selling across the EU in small volumes.

Reverse charge VAT: Nearly every startup purchases services from abroad — Google, Meta, Microsoft, Shopify and other SaaS providers. Where you receive services from a non-Irish supplier and you are VAT-registered, the reverse charge mechanism typically applies: you account for the VAT yourself on your VAT3 return. This is commonly overlooked in early-stage bookkeeping.

Step 5: Set Up Your Bookkeeping System From the Start

Irish company law requires that every company keep proper books of account that correctly record and explain its transactions. This is a legal requirement — books must be retained for at least six years. Good bookkeeping also makes VAT returns, payroll submissions and annual accounts significantly faster and cheaper to prepare.

At Forti, we work with Xero, QuickBooks and Zoho Books. Cloud-based platforms give real-time visibility and allow us to collaborate on your records without emailing spreadsheets back and forth.

What your bookkeeping needs to capture from day one:

  • All sales invoices issued
  • All purchase invoices and receipts received and stored
  • Bank transactions reconciled to your records
  • Director expenses — with receipts; undocumented expenses are not allowable
  • Payroll journals once payroll is running
  • Director’s loan account movements
Director’s loan account: When a founder puts money into the company or takes money out outside of payroll or a declared dividend, this is typically recorded as a director’s loan. The tax treatment depends on the nature and timing of the transaction. Overdrawn director’s loan accounts can have PAYE implications — worth understanding early.

Pre-trading expenses: Certain costs incurred in the three years before trading commenced — wholly and exclusively for the purposes of the trade — may be allowable as deductions in the first trading period. Keep receipts from the very beginning.

Step 6: Payroll — Even If It Is Just You

Many founder-directors pay themselves a salary through the company’s payroll. This is normal and common, but it carries compliance obligations.

How payroll reporting works in 2026

Payroll in Ireland is reported under PAYE Modernisation, in place since January 2019. There are no P30 or P35 forms. Instead:

  • Before or on the date employees (including directors) are paid, a payroll submission is made to Revenue reporting each individual’s pay, tax, PRSI and USC
  • Revenue issues a monthly statement based on those submissions, which becomes the employer’s return
  • PAYE, PRSI and USC are paid to Revenue on a monthly or quarterly basis depending on the employer’s arrangement
  • Payslips must be issued to each employee for every pay period
  • Revenue Payroll Notifications (RPNs) must be retrieved and applied before each payroll run — these replace the old tax credit certificates

My Future Fund auto-enrolment (from 1 January 2026)

Ireland’s new workplace pension scheme is now mandatory for eligible employees. An employee is generally automatically enrolled where they:

  • Are aged between 23 and 60
  • Earn more than €20,000 per year
  • Are not already contributing to a qualifying pension arrangement through payroll

During Phase 1 (2026–2028), contributions are: Employee 1.5% | Employer 1.5% | State 0.5% — all based on gross earnings. Eligibility depends on each individual’s employment and pension circumstances. Not every company director automatically falls within the scheme.

BIK (Benefit in Kind) — company vehicles, health insurance and other benefits provided to directors or employees must be valued and reported through payroll. BIK is subject to PAYE, PRSI and USC.

Step 7: Know Your Corporation Tax Position

Irish companies pay Corporation Tax at 12.5% on trading profits — one of the most competitive rates in the EU. Non-trading income (such as investment or rental income) is generally taxed at 25%.

Section 486C Start-Up Relief

Qualifying new companies may be entitled to a reduction or elimination of their Corporation Tax liability under Section 486C TCA 1997. The relief is available for the first five years of a qualifying trade that commences on or before 31 December 2026. It is calculated by reference to qualifying employer PRSI paid:

  • Up to €5,000 per qualifying employee (including directors paying Class A PRSI)
  • Since 1 January 2025, a director’s own Class S PRSI also qualifies, up to €1,000 per individual
  • Aggregate PRSI relief cap: €40,000 per year

Full relief applies where the CT liability does not exceed the PRSI cap. Marginal relief applies where the CT liability falls between the PRSI amount and €40,000 above it. This is a genuine Revenue-sanctioned relief that many startups do not claim simply because they are not aware of it.

Preliminary Corporation Tax — important startup exemption

New companies do not have to pay Preliminary Corporation Tax in their first accounting period where the CT liability for that period is below €200,000. The full CT liability is instead paid when the CT1 return is filed. This is a meaningful cash-flow benefit that many early-stage founders are not aware of.

Your CT1 is due nine months after your accounting year-end (no later than the 23rd of that month for ROS filers). A company with a 31 December year-end must file by 23 September the following year.

Step 8: Annual Compliance — The Recurring Calendar

Once you are set up and trading, your compliance calendar looks like this:

Obligation Frequency Filed With
VAT3 Return Generally bi-monthly (other periods may apply) Revenue
Payroll Submission On or before each pay date Revenue
PAYE/PRSI/USC Payment Monthly or quarterly Revenue
CRO Annual Return (B1) Annual — first ARD 6 months after incorporation CRO
Corporation Tax Return (CT1) Annual — 9 months after year-end Revenue
Statutory Financial Statements Annual CRO / Revenue
RBO Update As and when beneficial ownership changes RBO
Form 11 (proprietary director) Annual — where director is a chargeable person Revenue
 
Form 11 note: A proprietary director — broadly, a director who owns more than 15% of the company’s shares — is a chargeable person and must file a Form 11 income tax return annually via ROS. A non-proprietary director whose income is dealt with entirely through PAYE does not necessarily have the same obligation, but the position depends on individual circumstances.

Common Mistakes Irish Startups Make (and How to Avoid Them)

1. Not separating company and personal finances

A limited company is a separate legal entity. It should operate through a dedicated company bank account, with company and personal spending kept clearly separate from day one.

2. Missing the RBO five-month deadline

The Register of Beneficial Ownership obligation is not well-publicised. Many founders are unaware of it until year-end — by which point they are already in breach.

3. Not registering for VAT on time

Many startups realise they have exceeded the threshold only when preparing annual accounts — months after the obligation arose. Retrospective registration and back-payment of VAT is painful and costly.

4. Misunderstanding the first CRO annual return

The first B1 is due six months after incorporation — earlier than most expect. No financial statements are needed with that first return, but the return itself must still be filed on time.

5. Treating director withdrawals as salary without a payroll structure

Taking money from the company without a proper payroll, dividend or director loan structure creates PAYE and Revenue risk.

6. Ignoring reverse charge VAT on overseas services

Buying Google Ads, Shopify subscriptions or any other service from a non-Irish supplier while VAT-registered creates a reverse charge obligation. It is very commonly missed in early-stage bookkeeping.

7. Not understanding My Future Fund eligibility

Auto-enrolment is now live. Failing to assess employee eligibility and make contributions on time will result in compliance breaches.

Ready to Get Your Compliance Right From the Start?

Whether you are incorporating next week or already trading and trying to get on top of your obligations, Forti can help. Book a free 30-minute consultation with our team. We will review your current position, identify any gaps, and give you a clear plan — with no obligation and no jargon.

▣  01 906 5862 | ▣  info@forti.ie | ▣  www.forti.ie
⌖ Office 106, Nesta Business Centre, Burton Hall Road, Sandyford, Dublin 18

Frequently Asked Questions

Do I need an accountant to set up a company in Ireland?

You do not legally need an accountant to incorporate, but professional support saves time, avoids early structural mistakes, and ensures the company is set up tax-efficiently from day one.

What is the Corporation Tax rate for Irish startups?

The standard trading rate is 12.5%. Qualifying new companies may also be entitled to Section 486C Start-Up Relief, which can reduce or eliminate Corporation Tax in the first five years of trading.

When do I need to register for VAT in Ireland?

VAT registration is mandatory once annual turnover exceeds €85,000 for goods or €42,500 for services (thresholds in effect since 1 January 2025). Voluntary registration below these thresholds is also possible and often advisable.

What is the first CRO annual return deadline?

Your first Annual Return Date falls six months after incorporation. No financial statements are required with that first B1 — but the return itself must be filed on time.

What is My Future Fund?

My Future Fund is Ireland’s mandatory workplace pension auto-enrolment scheme, effective 1 January 2026. Eligible employees aged 23–60 earning over €20,000 are automatically enrolled. Phase 1 contributions: 1.5% employee, 1.5% employer, 0.5% State.

What replaced P30 and P35 forms?

P30 and P35 were abolished in January 2019. Employers now submit payroll data to Revenue on or before each pay date. Revenue issues a monthly statement which serves as the employer return.

What is the RBO and when do I need to file?

The Register of Beneficial Ownership requires companies to register details of individuals who ultimately own or control more than 25% of the company. The initial filing must be made within five months of incorporation.

Irish Company Setup Guide for EU Sales

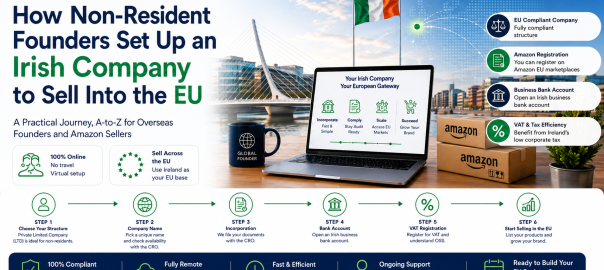
How Non-Resident Founders Set Up an Irish Company to Sell Into the Eu

QUICK ANSWER
Non-resident e-commerce founders can set up an Irish company without living in Ireland or the EEA — but the journey has two separate compliance tracks running in parallel: getting the company itself legally formed (Section 137 Bond, identity verification, AML/KYC), and getting it ready to actually trade across the EU (VAT registration, OSS/IOSS, and — if using Amazon FBA — a VAT footprint that can expand fast). Missing either track causes real delays; missing both at once is how most non-resident e-commerce setups go wrong.

At a Glance

Track One: Legal Formation Track Two: Trading & Tax Readiness
1. Identity verification (VIF/IPN) — often the real starting point 1. Irish VAT registration (+ EORI if importing stock)
2. Section 137 Bond arrangement 2. OSS/IOSS setup for cross-border sales
3. CRO incorporation & RBO filing 3. Marketplace settlement reconciliation (A2X/Link My Books)
4. Fintech or corporate banking setup 4. Local VAT registration in each country if using Pan-EU FBA

If you’re running an e-commerce business from the US, UK, UAE, or anywhere else outside the EEA and looking at Ireland as your EU entry point, you’re not alone — Ireland is a common choice for exactly this reason: English-speaking, EU/eurozone membership, and a well-understood company law framework. But non-resident founders setting up specifically to sell online run into two distinct sets of requirements that rarely get covered together: the rules around forming a company without an EEA-resident director, and the e-commerce-specific VAT obligations that kick in the moment you start trading. This guide walks through both, in the order you’ll actually hit them.

Why Overseas E-commerce Sellers Choose an Irish Company for EU Market Access

An Irish limited company gives a non-resident e-commerce founder a genuine EU legal entity — which matters for more than just optics. It means access to the EU’s VAT simplification schemes (OSS/IOSS) as an EU-established business rather than a non-EU one, straightforward eligibility for Amazon’s European marketplaces and fulfilment programmes, and a recognised EU corporate structure that EU-based suppliers, payment processors, and logistics partners are set up to work with by default.

None of that requires you to live in Ireland, or anywhere in the EEA. It does require getting two things right at the outset: how the company itself satisfies Irish director-residency law, and how it registers for VAT before its first sale.

Track One: Getting the Company Legally Formed

Identity Verification Usually Comes First

Almost no non-resident founder holds an Irish PPSN, which CRO filings require by default. The workaround is a Verification of Identity Form (VIF), which gets you an Identified Person Number (IPN) usable on all future CRO and RBO filings. This is worth starting immediately, not treating as a formality alongside everything else — for many non-resident founders, IPN approval is now the actual gating step on the whole incorporation timeline, since CRO processing depends on it being in place first. One detail that catches founders out: as of 30 April 2026, this form must be witnessed with the declarant and witness physically in the same room — a fully remote, video-witnessed process is no longer accepted, so this needs to be booked and planned for early rather than assumed to be a same-day online task.

This applies to beneficial owners too, not just directors. Anyone owning more than 25% of the company who lacks a PPSN also needs their own VIF-based IPN for the Register of Beneficial Owners (RBO) filing. The RBO filing deadline is five months from incorporation, but there’s no reason to wait — get the beneficial owner’s identity verification done in the same window as the director’s, using the same process, rather than treating it as a separate task to pick up later.

The EEA-Resident Director Requirement

Under Section 137 of the Companies Act 2014, every Irish company needs at least one director resident in the EEA (EU plus Iceland, Norway, and Liechtenstein) — residency, not nationality. If none of your founding team lives there, which is the normal situation for an overseas e-commerce founder, the standard route is a Section 137 Bond: a surety bond covering the company for €25,000, arranged at incorporation and renewed every two years. It’s the fastest option available to a brand-new company — the alternative (a Section 140 “real and continuous link” certificate) isn’t available until a company has an established Irish trading history, which obviously doesn’t exist yet at formation.

AML/KYC

Standard anti-money-laundering due diligence applies to all incoming officers and shareholders, non-resident or not — proof of identity, proof of address, and source-of-funds documentation, gathered as part of formation rather than as a separate step afterwards.

For the full breakdown of the bond, the identity verification process, common mistakes, and pricing, see “Setting Up an Irish Company Without an EEA-Resident Director.”

The Part Founders Don’t Expect: Opening a Bank Account

This is the step that surprises most non-resident founders. Traditional Irish banks can open corporate accounts for non-resident-owned companies, but a fully remote process is genuinely difficult — most traditional banks still expect some form of in-person or video verification and a clear business rationale for banking in Ireland specifically. In practice, many non-resident e-commerce founders start with an EU-facing fintech business account (providers like Wise Business or Revolut Business are commonly used for this) to get trading immediately, and either keep that as their primary account or move to a traditional bank later once the business has an established trading history. Either path is workable — the mistake is not planning for this step at all and assuming a bank account will be ready the moment the company is incorporated.

Track Two: Getting Ready to Actually Trade

Company formation and VAT registration are separate processes, and treating them as sequential rather than parallel is one of the most common causes of delay we see.

VAT Registration From Day One

Once incorporated, an Irish company selling to Irish or EU customers needs Irish VAT registration once it crosses €85,000 (goods) or €42,500 (services) — or can register voluntarily below that, useful if there are significant VAT-bearing setup costs to reclaim early. For sales into other EU countries, the One Stop Shop (OSS) scheme lets you report that cross-border VAT through a single Irish return once combined EU sales pass €10,000, rather than registering separately in every country you sell into.

Importing inventory into Ireland? If you’re shipping physical stock from outside the EU — Great Britain, the US, or China — into an Irish hub, you’ll also need an EORI number linked to your VAT profile. It’s worth setting up Postponed VAT Accounting (PVA) alongside your VAT registration at the same time: this lets you declare import VAT on your bi-monthly VAT3 return instead of paying it in cash at the border, which matters for cash flow if you’re importing stock regularly.

The Amazon-Specific Trap

If you’re planning to use Amazon’s Pan-European FBA programme, be aware before you opt in: the moment Amazon physically stores your stock in a country, you need a local VAT registration in that country — OSS does not cover this. As of January 2026, Amazon requires a minimum of five EU VAT registrations just to remain eligible for Pan-EU FBA. This is very commonly misunderstood by founders who assume OSS is a complete solution, and it’s worth deciding your fulfilment approach (Pan-EU FBA vs. the single-country European Fulfilment Network) before your VAT registrations are in place, not after stock has already started moving.

Planning to use Amazon Pan-EU FBA?
Don’t let inventory transfers freeze mid-launch because a VAT registration wasn’t in place before stock landed. Request a free e-commerce & non-resident formation review and Forti will map your required VAT footprint before you opt in.

For the full detail on OSS vs IOSS vs local VAT registration, the Pan-EU FBA VAT trap, the 2026 customs duty changes, and Extended Producer Responsibility (EPR/Repak) obligations for sellers of packaged goods, see “The Complete Guide to E-commerce Accounting for Shopify and Amazon FBA Sellers in Ireland.”

Ongoing Compliance

Once trading, a non-resident-owned Irish e-commerce company carries the same ongoing obligations as any Irish company — CRO annual returns, Corporation Tax (CT1), VAT3 filings, and Register of Beneficial Owners (RBO) filings, required within five months of incorporation and whenever ownership changes — on top of the e-commerce-specific bookkeeping challenge of reconciling Amazon and Shopify settlement reports (typically via A2X or Link My Books) across currencies and jurisdictions.

Choosing a Partner Who Understands Both Sides

This is the practical reason most non-resident e-commerce founders end up frustrated with their first advisor: a generalist formation agent understands the Section 137 Bond but not OSS/IOSS or the Pan-EU FBA VAT trap. An e-commerce-focused accountant understands VAT and marketplace reconciliation but may not have handled a non-resident director bond or VIF/IPN identity verification before. Getting both tracks right — the formation side and the trading side — usually means working with one partner who handles both, rather than coordinating a formation agent and a separate accountant who’ve never had to think about how the two interact.

Two Founders, Two Different Starting Points

These are composite, illustrative scenarios based on patterns we see across non-resident e-commerce clients — not specific named businesses.

The FBA seller who assumed OSS was enough

A US-based founder incorporated an Irish company, registered for Irish VAT and OSS, and started selling on Amazon — all correctly. Six months later, they opted into Pan-EU FBA to speed up EU delivery, assuming their existing OSS registration already covered it. It didn’t. Amazon began distributing stock into Germany, France, and Poland, and inventory transfers stalled while five local VAT registrations were arranged retroactively — during what should have been their busiest sales period.

The founder who left identity verification too late

A Dubai-based founder lined up their Section 137 Bond and company name in advance, expecting incorporation within days. They hadn’t accounted for the VIF process — booking an in-person notary appointment abroad took over two weeks, during which the CRO filing sat waiting on the IPN. The bond was never the bottleneck; the identity verification step was.

Both are avoidable with the same fix: treat both tracks as running from day one, not one after the other.

Frequently Asked Questions

Can a non-resident register a company in Ireland to sell on Amazon or Shopify?

Yes. There’s no requirement to live in Ireland or the EEA to form or own an Irish company. You do need to satisfy the EEA-resident director requirement, typically via a Section 137 Bond, and complete identity verification if you don’t hold an Irish PPSN.

Do I need to be VAT registered before I start selling?

You need Irish VAT registration once you exceed €85,000 (goods) or €42,500 (services) in turnover, though many non-resident founders register voluntarily from the outset. If you’re selling cross-border into the EU from day one, registering for OSS alongside your Irish VAT number is standard practice.

Can I open an Irish business bank account remotely as a non-resident?

It’s difficult with traditional banks, which usually expect some in-person or video verification. Most non-resident founders start with an EU-facing fintech business account to begin trading, then reassess once the company has an established history.

Does forming the company and registering for VAT happen at the same time?

They’re separate processes that can run in parallel, but they aren’t automatic — VAT registration has to be actively applied for once you know your trading plans, and it’s worth starting this alongside incorporation rather than waiting until the company is fully formed.

Do beneficial owners need identity verification too, or just directors?

Both. Anyone who owns more than 25% of the company and lacks an Irish PPSN needs their own VIF-based IPN for the RBO filing, separate from any director’s IPN. It’s worth doing both at the same time rather than leaving the beneficial owner’s verification until closer to the five-month RBO deadline.

Do I need an EORI number if I’m not importing anything myself?

No — an EORI number is only required if you’re importing physical stock into Ireland from outside the EU. If you’re sourcing entirely from EU suppliers or drop-shipping, it doesn’t apply.

What’s the biggest mistake non-resident e-commerce founders make?

Assuming OSS covers all their EU VAT obligations. It doesn’t cover local VAT registration triggered by holding stock in a country — which is exactly what happens under Amazon’s Pan-EU FBA programme.

Get Your Non-Resident E-commerce Setup Right From Day One

Forming the company and getting it ready to trade are two different jobs — Forti handles both together, so your identity verification, Section 137 Bond, VAT/OSS registration, and ongoing bookkeeping are managed as one process rather than passed between separate providers.

Talk to Forti about setting up your Irish e-commerce company → forti.ie


E-com Accounting

The Complete Guide to E-commerce Accounting for Shopify and Amazon FBA Sellers in Ireland

QUICK ANSWER
E-commerce accounting differs from standard Irish SME accounting because several distinct compliance regimes apply from the first sale, with no minimum threshold. The biggest blind spots are: VAT registration is required in every country where Amazon physically stores your stock (OSS does not cover this); the EU’s low-value customs duty exemption ended 1 July 2026; and packaging, electronics, or battery sellers may owe Extended Producer Responsibility (EPR) registration in Ireland regardless of where the business is based.

Running an e-commerce business looks deceptively simple from the outside: list a product, make a sale, ship it out. In reality, the moment a business starts selling across borders — which almost every Shopify or Amazon seller does within their first year — it inherits a compliance footprint that looks nothing like a typical Irish SME’s. A standard bookkeeping model built around one VAT number, one set of accounts, and domestic sales simply doesn’t hold up.

This guide walks through what actually makes e-commerce accounting different, covering the areas that most catch sellers out: VAT and OSS/IOSS, the specific VAT trap hidden inside Amazon’s Pan-European FBA programme, the customs duty change that took effect in July 2026, an environmental compliance obligation most sellers have never heard of, and how to actually reconcile the mess of data a marketplace generates every month.

The Irish E-commerce Market at a Glance

E-commerce isn’t a side channel in Ireland any more — it’s mainstream. Retail e-commerce in Ireland reached an estimated €8.8 billion in 2025, up around 6% year-on-year, and roughly 37.5% of Irish businesses now report having e-commerce sales. Amazon remains the single largest online retailer serving the Irish market by a wide margin. Growth of this scale is exactly why compliance gaps that were once minor — a missed VAT registration, an overlooked packaging obligation — now carry real financial exposure for sellers who are scaling faster than their back-office setup can keep up with.

Why E-commerce Accounting Doesn’t Fit a Standard Bookkeeping Model

A typical Irish limited company sells to Irish customers, charges Irish VAT, and files one VAT3 return covering one jurisdiction. An e-commerce business rarely works that way for long. Within months of scaling past a modest turnover, a Shopify or Amazon seller is likely to be:

  • Selling to customers in multiple EU countries, each with its own VAT rate
  • Holding stock in fulfilment centres outside Ireland, which changes where VAT is actually owed
  • Generating hundreds or thousands of small transactions a month, each bundled with marketplace fees, refunds, and currency conversions
  • Subject to environmental and product compliance obligations that have nothing to do with tax at all

None of this is optional or something that can be addressed “later, once the business is bigger.” Several of these obligations apply from the very first sale, with no minimum threshold. Getting the structure right early avoids a much more expensive clean-up exercise down the line.

VAT and OSS/IOSS Registration for Cross-Border Sellers

The starting point for any Irish e-commerce business is Irish VAT registration. As of May 2026, the Irish VAT registration thresholds are €85,000 for goods and €42,500 for services. Below these thresholds, registration is optional; above them, it’s mandatory.

But for a business selling into other EU countries, Irish registration is only the beginning. The One Stop Shop (OSS) scheme lets a business report VAT on cross-border B2C sales to other EU countries through a single return filed in Ireland, rather than registering separately in every country it sells into. The OSS threshold remains €10,000 — combined across all cross-border EU sales, not per country — above which OSS (or individual country registration) becomes necessary.

For non-EU sellers shipping low-value goods directly to EU consumers, the Import One Stop Shop (IOSS) serves a similar purpose for import VAT, allowing VAT to be collected at the point of sale rather than at the border.

A caution on registering below the threshold: sellers below the €85,000/€42,500 thresholds can register for VAT voluntarily, which is often worthwhile if there are significant VAT-bearing costs to reclaim. But Revenue does scrutinise voluntary applications from pre-trading or pre-revenue businesses more closely than standard registrations. Be ready to show concrete evidence of an intention to trade — supplier contracts, a live Shopify store, or inventory invoices — as applications lacking this can be queried or rejected outright.

Importing Stock Into Ireland? Don’t Overlook PVA and Your EORI Number

Many Irish e-commerce sellers import stock from Great Britain (now treated as a non-EU import post-Brexit) or from Asia before listing it on Shopify or Amazon. Two additional pieces of the compliance picture come into play the moment goods are imported from outside the EU:

  • An EORI number (Economic Operators Registration and Identification) is required to clear customs, and needs to be linked to the business’s Revenue VAT registration.
  • Postponed VAT Accounting (PVA) lets a VAT-registered, Customs & Excise-registered importer account for import VAT directly on their VAT3 return — declaring and reclaiming it in the same return — rather than paying it in cash at the point of entry. This is a genuine cash-flow advantage for any business importing stock regularly, and Revenue’s own guidance confirms it removes the need to pay VAT at the point of importation, subject to the usual deductibility rules.

Businesses that were both VAT- and Customs & Excise-registered before PVA’s introduction received automatic entitlement to use it; anyone registering for VAT and Customs & Excise since then should confirm their postponed accounting position is properly set up — including the correct PA1 entries on the VAT3 — before their first import lands.

Comparing OSS, IOSS, and Local VAT Registration

These three mechanisms are frequently confused, and mixing them up is the single most common VAT mistake among growing e-commerce sellers.

OSS IOSS Local VAT Registration
What it covers Cross-border B2C sales to other EU countries, from stock held in one EU country Import VAT on low-value goods (≤€150) shipped directly to EU consumers from outside the EU VAT on sales and stock held physically within that specific country
Threshold €10,000 combined cross-border EU sales No threshold — per consignment≤€150 No threshold — triggered by holding stock in-country≤€150
Common mistake Assuming it covers Pan-EU FBA stock-holding — it doesn’t Assuming it still means duty-free after 1 July 2026 — it doesn’t Assuming Amazon handles this automatically — it doesn’t

The crucial limitation to understand: OSS only covers where VAT is owed on the sale, not where a business is required to hold a full local VAT registration. That distinction becomes critical the moment stock is physically stored outside Ireland — which is exactly what happens with Amazon’s Pan-European FBA programme.

Pan-EU FBA: The VAT Obligation Most Sellers Don’t See Coming

This is the single most common compliance gap among growing Amazon sellers, and it catches out businesses that are otherwise fully VAT compliant in Ireland.

Amazon’s Pan-European FBA programme distributes a seller’s inventory automatically across its European fulfilment network to speed up delivery and reduce shipping costs. It’s a genuinely useful feature — but it comes with a rule that has nothing to do with sales thresholds: the moment inventory is physically held in a country, VAT registration is required in that country, from the very first unit stored. OSS does not cover this. There is no minimum threshold and no grace period.

In practice, this means a seller enrolled in Pan-EU FBA can find their stock automatically moved into Germany, France, Italy, Spain, Poland, and the Czech Republic — sometimes more — without VAT registration in any of them. Amazon has tightened this further: as of January 2026, sellers must hold VAT registrations in a minimum of five EU countries just to remain eligible for the Pan-EU programme at all. Fall short, and Amazon can restrict or block inventory transfers, which quietly removes the delivery-speed and fee advantages the programme exists to provide in the first place.

Sellers who want to avoid this exposure without giving up FBA altogether typically use the European Fulfilment Network (EFN) instead — storing stock in a single country and shipping cross-border from there — which limits the VAT footprint to that one country plus OSS for cross-border sales, at the cost of slightly slower delivery in some markets.

Illustrative Example: How a Growing Seller’s VAT Footprint Changes

This is a composite scenario based on patterns we see repeatedly across e-commerce clients — not a specific named business.

A Shopify and Amazon seller starts out shipping only from Ireland. In year one, all stock sits in a single Irish warehouse , one VAT registration, one VAT3 return, straightforward. As EU sales grow past €10,000, the seller registers for OSS, which now handles the cross-border VAT on those sales through a single Irish filing ; still manageable.

In year two, the seller opts into Amazon’s Pan-EU FBA programme to speed up delivery across Europe. Overnight, Amazon begins distributing stock into Germany, France, Italy, Spain, and Poland. OSS does not cover any of this stock-holding — the seller now needs five separate local VAT registrations, five sets of local filing obligations, and (per Amazon’s current rules) must have all five in place simply to stay eligible for the programme. A seller who enrolled without anticipating this can find inventory transfers frozen mid-flow while registrations are sorted out — often the first sign something has gone wrong, and a costly one during a peak sales period.

The practical takeaway: before opting into Pan-EU FBA, know exactly which countries your stock will land in and have VAT registrations in place before it arrives, not after. Amazon’s Inventory Event Detail Report is the standard way to track where stock is actually being held.

Unsure where your stock is currently being stored?

Amazon FBA inventory transfers happen automatically behind the scenes, which is exactly how sellers end up with an unregistered VAT obligation without realising it.
Request a free e-commerce VAT & EPR review → forti.ie

The 2026 Customs Duty Change: What It Means for Low-Value Consignments

Until recently, the EU allowed goods valued at €150 or less to enter the bloc free of customs duty. That exemption ended on 1 July 2026. In its place, a temporary flat customs duty of approximately €3 per HS-code line item now applies to consignments of €150 or less, regardless of whether the Import One Stop Shop is used. This interim measure is expected to run until 1 July 2028, ahead of a broader EU customs reform.

The detail that trips people up: IOSS still simplifies how VAT is collected at checkout, but it no longer means duty-free. These are two separate things that used to align neatly and no longer do. A seller who assumes their IOSS registration still covers “no extra charges at the border” for small parcels is working from an outdated assumption that changed only recently — worth flagging explicitly to customers and factoring into landed-cost pricing for low-value items shipped directly from outside the EU.

A Compliance Obligation Most Sellers Have Never Heard Of: Extended Producer Responsibility (EPR)

This is the area most e-commerce guides skip entirely, and it’s a genuine blind spot for sellers focused only on VAT.

Extended Producer Responsibility is an environmental compliance regime that makes anyone placing packaged goods, electrical equipment, or batteries on the Irish market financially responsible for that product’s end-of-life collection and recycling. In Ireland, packaging EPR is administered through Repak, the country’s approved compliance body, with separate schemes covering WEEE (waste electrical and electronic equipment) and batteries.

The important point for e-commerce sellers: this obligation applies to distance sellers, not just Irish-based manufacturers. A business based outside Ireland — including a non-resident seller — that supplies packaged goods directly to Irish consumers is treated as a “producer” under Irish packaging regulations and carries the same registration and reporting obligation as a local manufacturer would. The same logic applies to anyone selling electronics or battery-powered products to Irish buyers via Amazon.ie or a Shopify store shipping into Ireland.

  • Businesses placing packaging on the Irish market above certain thresholds (broadly, larger volumes and turnover) are classed as “major producers” and must join Repak, reporting packaging weights and paying a fee based on volume
  • Smaller producers typically have a simplified registration route with a fixed annual fee rather than the full major-producer reporting burden
  • Sellers of electrical or battery-powered goods have a parallel obligation through the National WEEE Register

This is easy to overlook because it isn’t a tax and doesn’t show up on a VAT return — but it’s a genuine legal obligation with financial penalties for non-compliance, and it’s one that grows more relevant every year as EU packaging waste rules tighten. Any e-commerce business shipping packaged goods into Ireland at meaningful volume should have this checked, not assumed away.

Reconciling Amazon and Shopify Settlements With A2X or Link My Books

Beyond registration and compliance, the day-to-day bookkeeping challenge for e-commerce sellers is different in kind from a typical business. A single Amazon settlement report can bundle together gross sales, referral fees, FBA fees, storage fees, refunds, promotional discounts, and VAT — all in different currencies if selling across multiple marketplaces — and dumping that raw data into a general ledger produces a mess that no accountant can make sense of, let alone use for accurate VAT filings.

This is where reconciliation tools like A2X and Link My Books earn their keep. Both integrate directly with Amazon, Shopify, and other marketplaces, breaking down each settlement into its individual components and posting a clean, correctly categorised summary into Xero or QuickBooks — with VAT correctly split by jurisdiction, which matters enormously once a seller has multiple VAT registrations in play. Attempting to reconcile marketplace settlements manually, without one of these tools, is one of the most common causes of inaccurate VAT filings among growing e-commerce sellers.

Corporation Tax and Multi-Marketplace Bookkeeping Considerations

Once the VAT and reconciliation side is under control, standard Irish company obligations still apply on top: Corporation Tax (CT1) on annual profits, CRO annual returns, and — where turnover and other thresholds are exceeded — statutory audit requirements. The complexity multiplies with the number of marketplaces and currencies involved: a seller running Shopify, Amazon, and perhaps eBay simultaneously needs bookkeeping that consolidates all three cleanly into one set of management accounts, ideally on a monthly cycle rather than being reconstructed at year-end.

What to Look for in an E-commerce Accountant

Given everything above, a generalist accountant without e-commerce experience will typically miss at least one of these areas — most often the Pan-EU FBA VAT trap or the EPR obligation, since neither shows up unless someone is specifically looking for it. When choosing who handles your accounts, look for:

  • Direct, practical experience with Amazon and Shopify settlement reconciliation, not just general bookkeeping
  • Familiarity with OSS/IOSS registration and the distinction between cross-border sales VAT and local stock-holding VAT
  • Awareness of EPR/Repak obligations for physical goods sellers — not every accountant will think to raise this
  • Comfort working with tools like A2X or Link My Books as standard practice, not an unfamiliar add-on

Frequently Asked Questions

Do I need to register for VAT in every country where Amazon stores my stock?

Yes. The moment Amazon physically holds your inventory in a country under Pan-EU FBA, you need a local VAT registration there — there’s no threshold and no grace period. OSS does not cover this; it only applies to cross-border sales, not stock-holding.

What’s the difference between OSS and IOSS?

OSS covers cross-border B2C sales of goods and services to other EU countries where you hold stock in one EU country. IOSS covers import VAT on low-value consignments (€150 or less) shipped directly to EU consumers from outside the EU. They serve different situations and aren’t interchangeable.

Does OSS cover Pan-EU FBA VAT registration?

No. This is the most common misunderstanding among growing sellers. OSS handles VAT on the sale itself; it does not replace the local VAT registration required wherever your stock is physically held.

Is IOSS still duty-free for orders under €150?

No, not since 1 July 2026. The EU’s duty-free exemption for consignments of €150 or less ended on that date. A flat customs duty of roughly €3 per HS-code line item now applies regardless of whether IOSS is used, as an interim measure expected to run until 1 July 2028.

Do I need to register for EPR/Repak if I only sell through Amazon FBA?

Potentially, yes. If you supply packaged goods, electronics, or batteries directly to Irish consumers — including via Amazon.ie — you may be classed as a “producer” under Irish packaging regulations regardless of where your business is based, and carry a Repak (or WEEE Register) registration obligation.

How many EU VAT registrations do I need for Amazon Pan-EU FBA in 2026?

As of January 2026, Amazon requires a minimum of five EU VAT registrations to remain eligible for the Pan-EU FBA programme. The exact countries depend on where your stock is distributed — commonly Germany, France, Italy, Spain, and Poland.

What tools help reconcile Amazon and Shopify settlements for VAT?

A2X and Link My Books are the two most widely used tools. Both break marketplace settlement reports into their individual components (sales, fees, refunds, VAT) and post a clean summary into Xero or QuickBooks, split correctly by jurisdiction.

How does Postponed VAT Accounting (PVA) help Irish e-commerce importers?

PVA lets a VAT-registered, Customs & Excise-registered business account for import VAT on its VAT3 return instead of paying it in cash at the point of import. It preserves working capital on imported stock, but requires an active EORI number and correct PA1 reporting on the VAT3.

E-commerce accounting isn’t harder than standard SME accounting because the numbers are more complicated — it’s harder because there are simply more distinct compliance regimes running in parallel, several of which apply from the first sale with no threshold to build up to. Getting the structure right from the outset is considerably cheaper than untangling it after a few years of growth.

Get Your E-commerce VAT and Compliance Position Reviewed

If you’re selling on Shopify or Amazon — or planning to opt into Pan-EU FBA — it’s worth having your VAT registrations, OSS/IOSS setup, and EPR obligations checked by someone who works with e-commerce sellers day to day, before a gap like the ones above turns into a frozen inventory transfer or a backdated liability.

Forti works with Shopify and Amazon FBA sellers on VAT registration, OSS/IOSS compliance, and monthly bookkeeping using A2X and Link My Books — from €195/month.

Talk to Forti about your e-commerce accounts → forti.ie


COMPLIANCE & RISK INSIGHTS

Selling or Winding Down a Company With Unresolved Compliance Issues: What Buyers, Solicitors and Revenue Will Find

A missed annual return or an uncancelled VAT registration is one thing when nobody’s looking. It’s a different problem entirely when a buyer’s solicitor, an investor’s due diligence team, or Revenue’s own tax clearance system starts looking — which is exactly what happens the moment you try to sell, merge, or formally close a company.

Why Compliance History Becomes Visible at Exactly the Wrong Moment

Throughout this series we’ve looked at what happens when a business owner simply stops trading and leaves the paperwork unresolved. Selling a company, bringing in an investor, or even just formally winding it down properly surfaces every one of those gaps at once — because each process relies on independent, third-party verification of exactly the things that tend to get left until later: CRO filing history, Revenue’s tax clearance system, and the Register of Beneficial Ownership.

None of this is hidden. A company’s late filing history is publicly searchable on the CRO register, RBO discrepancies are checked as standard AML due diligence, and Revenue’s tax clearance status is verified electronically in real time. A buyer’s solicitor will find what’s there — the only question is whether it’s found before or after you’ve agreed a price.

Share Sale vs Asset Sale: Why Compliance History Matters Differently

Share Sale

When shares in the company are sold, the buyer acquires the company itself — its history, its liabilities, and its compliance record, warts and all. Every unresolved CRO filing, every unpaid Revenue liability, and every RBO discrepancy transfers with it unless specifically carved out. This is why share sale agreements lean so heavily on warranties and indemnities: the buyer is pricing in exactly this risk, and will expect the seller to stand behind it contractually.

Asset Sale

When the buyer instead purchases specific assets — a customer list, equipment, a brand, a lease — out of the company rather than the company itself, historic compliance issues are less likely to transfer directly. But the company itself still needs a clean compliance position to complete the sale in the first place: a Tax Clearance Certificate is often required to satisfy the buyer and their bank, and if the sale involves property, a CG50 clearance certificate is required under Section 980 of the Taxes Consolidation Act 1997 — without it, the purchaser is legally required to withhold part of the sale proceeds and remit them to Revenue.

What Due Diligence Actually Uncovers

  • Late CRO filing history — publicly visible on the register and an immediate flag for any buyer’s solicitor running standard checks.
  • Loss of audit exemption from a prior late filing — meaning historic accounts may need to be re-audited before a deal can close cleanly.
  • An expired or refused Tax Clearance Certificate — Revenue’s electronic system checks compliance in real time and will not issue clearance while returns or liabilities remain outstanding.
  • RBO mismatches — beneficial ownership details that don’t match the actual shareholding, a standard check under anti-money-laundering due diligence.
  • Unresolved VAT, OSS, or foreign VAT registrations — particularly relevant for ecommerce or multi-country sellers, as covered in Part 3 of this series.
  • A CG50 requirement the seller wasn’t aware applied — relevant wherever property or certain high-value assets form part of what’s being sold.

Preparing a Company for Sale or Formal Closure

  1. Bring every CRO annual return up to date well before entering negotiations — a clean filing history removes one of the most visible red flags in due diligence.
  2. Apply for a Tax Clearance Certificate early. The electronic system checks compliance automatically, and any gap will surface immediately rather than at the point you actually need it.
  3. Confirm the Register of Beneficial Ownership entry matches the current shareholding exactly, updating within 14 days of any change.
  4. Resolve any dormant, ceased-trading, or multi-country VAT ambiguity — as set out in Parts 1 through 3 of this series — so the buyer’s due diligence team isn’t the one working out what category the company actually falls into.
  5. If property or qualifying assets are involved, apply for CG50 clearance as soon as contracts are signed rather than waiting until closing, since Revenue can take up to several weeks to process it.
  6. Where the company won’t be sold at all but simply needs to close, follow the voluntary strike-off process from Part 2 rather than leaving it to lapse mid-negotiation.

What Happens If You Sell Anyway, Issues Unresolved

Deals don’t usually collapse outright over compliance gaps — they get renegotiated. A buyer who discovers late filings, a lapsed audit exemption, or an unresolved VAT position will typically respond in one of a few predictable ways: a reduction in price to reflect the cost of fixing it, a specific indemnity requiring the seller to cover any resulting liability after completion, or a delay to closing while the seller resolves the position. In each case, the seller ends up paying for the same fix they could have made earlier — just later, under time pressure, and with less negotiating leverage.

Case Studies

Case Study 1 — A Share Sale Delayed by an Expired Audit Exemption

A services company preparing to sell discovered during due diligence that a prior year’s late annual return had cost it audit exemption for two years — years for which the accounts had never actually been audited. Completion was delayed by several weeks while a retrospective audit was arranged, and the buyer negotiated a price reduction to reflect the delay and the risk.

Case Study 2 — A Missed CG50 Almost Cost the Seller Cash at Closing

A business owner selling a company that held a small commercial property assumed the sale would proceed like any other share transaction. Their solicitor identified that a CG50 clearance certificate was required under Section 980 given the property involved, and without it, the purchaser would have been legally required to withhold part of the proceeds. Applying as soon as contracts were signed avoided a hold-back at closing that would otherwise have tied up a meaningful portion of the sale price.

Case Study 3 — An RBO Mismatch That Slowed Down Investor Due Diligence

A founder seeking investment for an otherwise healthy business found the round delayed when the investor’s AML checks flagged a discrepancy between the Register of Beneficial Ownership and the company’s actual shareholding, following an earlier share transfer that had never been updated on the register. The correction itself was straightforward, but it added weeks to a process the founder had expected to close quickly.

(These case studies are illustrative composites reflecting patterns we see regularly among Irish business owners, not individual clients.)

Technical Appendix: Statutory Thresholds & Legal Mechanics

1. Capital Gains Tax Clearance (Section 980 & Form CG50A)

When an asset sale or a share sale involves specific Irish assets (such as land, buildings, goodwill, or unquoted shares deriving their value from Irish land), strict statutory thresholds apply under Section 980 of the Taxes Consolidation Act 1997:

  • The Triggers: A Form CG50A clearance certificate is legally required if the disposal consideration exceeds:
    • €500,000 for commercial property, land, business goodwill, or qualifying unquoted shares.
    • €1,000,000 for residential property.
  • The Withholding Penalty: If the seller fails to produce a valid CG50A certificate to the buyer prior to or at closing, the purchaser is legally mandated to withhold exactly 15% of the gross purchase price and remit it directly to Revenue within 30 days.
  • Processing Timelines: Applications must be submitted electronically via the eCG50 facility on ROS (Revenue Online Service). Revenue standard processing times typically range from 3 to 4 weeks, meaning applications should ideally be initiated as soon as contracts are exchanged.

2. Companies Registration Office (CRO) & Audit Exemption Rules

Filing histories are scrutinized heavily during corporate transactions due to the severe downstream legal impacts of a missed deadline:

  • Automatic Loss of Exemption: Under the Companies Act 2014, if a company files its annual return late by even one day, it automatically forfeits its right to claim an audit exemption for the financial year in question and the subsequent financial year.
  • The Transaction Impact: If a company has traded through those years without an audit under the assumption it was exempt, it will be forced to commission a retrospective audit before a share sale can cleanly close. This frequently causes severe delays and triggers price chips from buyers.

3. Register of Beneficial Ownership (RBO) Compliance

  • The 14-Day Rule: To comply with statutory Anti-Money Laundering (AML) frameworks, any internal corporate restructuring, share transfer, or allotment must be updated on the central Register of Beneficial Ownership within 14 days of the change.
  • Due Diligence Friction: Discrepancies between the company’s internal stock transfer book and the public RBO register automatically flag during a buyer’s or investor’s standard AML checks, halting funds from being drawn down until rectified.

Key Action Checklist for Pre-Sale Due Diligence

Compliance Area Verification Action Timing Requirement
1.Tax Clearance Certificate (TCC) Check ROS electronic status across all tax heads (VAT, Relevant Contracts Tax, Corporation Tax, PAYE/PRSI). Run 6–8 weeks before negotiations to catch hidden flags.
2.CG50 Clearance File electronic application via eCG50 on ROS if transaction hits the €500k/€1m thresholds. File immediately upon exchange of contracts.
3.CRO History Verify that no annual returns are pending and check for past late filings that might have triggered an audit requirement Review before drafting the initial Heads of Terms.
4.RBO Alignment Cross-reference the central RBO register against the current register of members Remediate any discrepancies at least 3 weeks prior to closing.

Frequently Asked Questions

Do I need a Tax Clearance Certificate to sell my company?

It’s frequently required by buyers, their banks, or as part of standard due diligence, even where not strictly a legal precondition of the sale itself. Applying early, since Revenue’s electronic system checks compliance automatically, avoids delay at the point you actually need it.

What’s the difference between a Tax Clearance Certificate and a CG50?

A Tax Clearance Certificate confirms your overall tax affairs are in order. A CG50 is a separate clearance specifically relevant where property or certain qualifying assets are part of the sale, confirming Revenue doesn’t require the purchaser to withhold part of the proceeds.

Can late CRO filings actually stop a sale from completing?

They rarely stop a sale outright, but they routinely delay it and give the buyer leverage to negotiate a lower price or demand a specific indemnity covering the risk.

Does an asset sale avoid all these compliance issues?

Not entirely. While historic liabilities are less likely to transfer with specific assets rather than the company as a whole, the company itself typically still needs a Tax Clearance Certificate and, where property is involved, a CG50 to complete the transaction.

How long does it take to fix these issues once discovered mid-deal?

We prepare companies for sale or formal closure well before a buyer’s solicitor gets involved — bringing CRO filings current, securing tax clearance, correcting RBO entries, and resolving any dormant or ceased-trading ambiguity, so the compliance story is already clean by the time due diligence begins.

Preparing to Sell or Close? Talk to Forti Early

Monthly bookkeeping and management accounts from €195/month + VAT

Irish company formation, CRO fee included: €250

Tax clearance, RBO correction and pre-sale compliance clean-up available on request

If a sale, investment round, or formal closure is on the horizon, get in touch with the Forti team at forti.ie before a buyer’s due diligence team finds the gaps for you.

What Happens to Your VAT and OSS Registration

What Happens to Your VAT and OSS Registration When Your Ecommerce Business Stops Trading

Ecommerce sellers carry more moving parts than most business owners when they stop trading — an OSS registration, possibly a foreign VAT registration tied to stored stock, and a marketplace account that keeps running whether you’re paying attention to it or not. Here’s what needs to be closed down deliberately, and what happens if it isn’t.

Why Ecommerce Sellers Are a Special Case

Most of the compliance failures we’ve covered in this series apply to any Irish business. Ecommerce sellers carry extra exposure on top: a Union OSS registration reporting sales across every EU state you sell into, potentially a local VAT registration in any country where you’ve stored stock, and — if you sell through Amazon, eBay or Etsy — a marketplace account that continues taking orders, holding your inventory, and generating transactions long after you’ve mentally ‘stopped.’ None of these switch off on their own, and each has its own separate deregistration process.

Deregistering From OSS: The Steps That Actually Matter

1. Notify Revenue electronically, through the VAT OSS section in ROS, that you wish to deregister. This must be done at least 15 days before the end of the calendar quarter prior to the quarter in which you intend to stop using the scheme.

2. File your final OSS return covering the last quarter of use, and pay any VAT still due — deregistering doesn’t cancel liability for supplies already made under the scheme.

3. Keep OSS records for the full 10-year retention period required under EU rules, even after deregistration — Revenue and other member states can still request them.

4. If you’re stopping trading altogether rather than switching schemes, also cancel your underlying Irish VAT registration via TRCN1 once all final returns are filed.

Miss the 15-day notice window and simply stop filing instead, and you risk a different outcome entirely: exclusion from the scheme by Revenue for non-compliance, which triggers a quarantine period during which you cannot re-register for OSS even if you resume trading. A deliberate, on-time deregistration and an enforced exclusion are not the same thing on your compliance record.

The Stock Problem: What Happens to Inventory You Still Hold

If you’re deregistering with stock still on hand, Revenue treats the retention of that stock — for personal use, write-off, or simply because it wasn’t sold — as a deemed supply, meaning VAT still needs to be accounted for on it in your final return. This is one of the most commonly missed steps in a rushed closure: sellers cancel the registration and quietly dispose of remaining stock without accounting for the VAT position on it first.

The bigger risk sits with sellers using Amazon FBA or another pan-EU fulfilment model. OSS never covered the stock itself — only the sale to the end consumer. If stock is still sitting in a warehouse in Germany or Poland when you deregister from OSS and cancel your Irish VAT number, the local VAT registration in that country doesn’t disappear with it. It has to be separately closed, and any stock still physically there needs to be cleared, transferred, or accounted for under that country’s own rules first.

Marketplace Accounts Don’t Close Themselves Either

Closing an Amazon, eBay or Etsy seller account is a commercial step, not a tax one — but leaving it active after you’ve stopped trading creates exactly the kind of loose end that causes problems later. Outstanding orders, returns, and marketplace-collected VAT under the deemed supplier rules can continue generating activity on an account you’ve mentally already closed, and reconciling that activity months later, against tax registrations that have already been cancelled, is far harder than closing everything in the right order at the time.

A Sensible Closing Order

  • Stop taking new orders across every channel and let existing orders and returns run to completion.
  • Clear or transfer any stock held in foreign warehouses, and close the associated local VAT registration in that country.
  • Account for VAT on any stock you retain rather than sell, in your final return.
  • Submit your OSS deregistration at least 15 days before the end of the prior quarter, and file the final OSS return.
  • Cancel your underlying Irish VAT registration via TRCN1 once all final returns are filed and settled.
  • Close the marketplace seller accounts themselves once orders, returns and payouts have fully settled.
  • If the business traded through a limited company, follow the CRO closure steps covered in Part 2 of this series — dormancy, voluntary strike-off, or restoration, depending on where things stand.

Case Studies

Case Study 1 — A Clean OSS Deregistration

A Shopify-based homeware seller decided to close the business at the end of a calendar quarter. The deregistration notice was submitted to Revenue in good time, the final OSS return was filed and paid, and the underlying Irish VAT registration was cancelled once no further stock remained. No penalties, no quarantine period, and no loose ends.

Case Study 2 — Stranded Stock in a German Warehouse

An Amazon FBA seller cancelled their Irish VAT registration and OSS scheme without first arranging for stock still held in Amazon’s German fulfilment centre to be cleared. The German VAT registration tied to that stock remained technically open, and Amazon continued to report inventory movements against it. The position was only resolved once the stock was removed and the foreign registration formally closed — a step that should have preceded, not followed, the Irish deregistration.

Case Study 3 — Missing the Notice Window

A multi-channel seller simply stopped filing OSS returns after winding the business down informally, without submitting a deregistration notice. Revenue excluded the registration for non-compliance rather than processing a clean deregistration, which placed the business in a quarantine period before it could register for OSS again — relevant a year later when the same founder started a new ecommerce venture and found the scheme temporarily unavailable to them.

(These case studies are illustrative composites reflecting patterns we see regularly among Irish ecommerce clients, not individual businesses.)

Technical Appendix: Compliance Thresholds & Operational Mechanics

1. Capital Gains Tax Clearance

When an asset sale or a share sale involves specific Irish assets—such as land, buildings, business goodwill, or unquoted shares deriving their value from Irish land—specific financial thresholds apply:

  • The Triggers: A clearance certificate is required if the transaction value exceeds:
    • €500,000 for commercial property, land, business goodwill, or qualifying unquoted shares.
    • €1,000,000 for residential property.
  • The Withholding Penalty: If the seller fails to produce a valid clearance certificate to the buyer prior to or at closing, the purchaser is legally required to withhold exactly 15% of the gross purchase price and pay it directly to Revenue within 30 days.
  • Processing Timelines: Applications must be submitted electronically. Standard processing times typically range from 3 to 4 weeks, meaning applications should be initiated as soon as contracts are signed.

2. Company Registration History & Audit Exemption Rules

Filing histories are scrutinized heavily during corporate transactions due to the severe downstream impacts of a missed deadline:

  • Automatic Loss of Exemption: If a company files its annual return late by even a single day, it automatically loses its right to claim an audit exemption for that financial year and the subsequent financial year.
  • The Transaction Impact: If a company has traded through those years without an audit under the assumption it was exempt, it will be forced to commission a retrospective audit before a share sale can cleanly close. This causes severe transaction delays and often triggers price reductions from buyers.

3. Register of Beneficial Ownership (RBO) Compliance

  • The 14-Day Rule: Any internal corporate restructuring, share transfer, or new allotment must be updated on the central Register of Beneficial Ownership within 14 days of the change.
  • Due Diligence Friction: Discrepancies between the company’s internal share register and the public RBO register automatically flag during standard anti-money laundering checks, halting funds from being drawn down until corrected.

4. One Stop Shop (OSS) Timelines & Penalties

  • The Cut-off Logic: To stop using the Union OSS scheme, a business must notify Revenue by the 15th day of the final month of a calendar quarter (e.g., to exit from 1 October, notice must be submitted on or before 15 September). Missing this deadline locks the business into the scheme for the next full 3-month cycle.
  • The Quarantine Mechanic: A forced exclusion from the scheme due to persistent non-compliance (such as failing to file or pay for 3 consecutive quarters) results in an automatic 2-year suspension. During this time, the business cannot register for OSS in any EU Member State and must instead seek multiple local retail VAT registrations.
  • Data Retention Mandate: All records supporting OSS returns must be maintained digitally and made available upon request for exactly 10 years from the end of the year of the transaction.

5. Domestic VAT Cessation & Stock Asset Disposal

  • Deemed Supply Rule: Goods forming part of the assets of a business that ceases to trade are treated as sold by the business to itself.
  • Valuation: The VAT on unsold closing stock must be calculated based on the cost price (or purchase price) of the goods at the time of cessation, not the retail price.
  • Cancellation Mechanism: The domestic VAT cancellation is processed through an electronic registration facility once all final returns and liabilities hit zero.

6. Cross-Border Fulfillment & Marketplace Rules

  • Storage vs. Sale: Holding stock in a fulfillment center outside of Ireland immediately triggers a local VAT registration requirement in that host country. Canceling the Irish OSS scheme does not automatically close foreign VAT accounts.
  • Marketplace Rules: Digital platforms are responsible for collecting tax on certain transactions. However, if a merchant account is left active with automated returns or customer credits processing post-closure, the platform will continue to generate data entries that conflict with cancelled tax registrations.

Pre-Sale & Pre-Closure Sequence Checklist

Step Compliance Channel Metric / Deadline
1. Stock Liquidation Marketplace / Warehouse Clear, destroy, or legally transfer all foreign inventory out of non-Irish fulfillment hubs.
2. Foreign VAT Closure International Tax Authorities File final local returns and submit formal deregistration forms to every individual country where stock was stored.
3. Tax Clearance Certificate Electronic Revenue System Check status across all tax heads (VAT, Corporation Tax, PAYE/PRSI) 6–8 weeks before negotiations.
4. Deemed Supply Calculation Domestic VAT Return Value remaining Irish stock at cost price; include this figure on the final VAT return.
5. OSS Exit Notice Electronic OSS Portal Submit deregistration request 15 days or more before the quarter’s end.
6. Capital Gains Clearance Electronic Revenue System File clearance application if the transaction hits the €500k/€1m thresholds immediately upon exchange of contracts.
7. Domestic Cancellation Electronic Revenue System Submit formal cancellation for the underlying domestic VAT number once all liabilities are clear.
8. RBO Alignment Central Register Cross-reference the central RBO register against the current internal register of members at least 3 weeks prior to closing.

Frequently Asked Questions

1.Can I just stop filing OSS returns once I’ve stopped trading?

Ans: You can, but it’s the wrong way to close it. Simply stopping without notifying Revenue can result in exclusion from the scheme rather than a clean deregistration, which carries a quarantine period before you can register again.

2. Do I need to deregister OSS and Irish VAT at the same time?

Ans: Not necessarily at the same moment, but in the right order — OSS deregistration first (with its 15-day notice requirement), followed by cancellation of the underlying Irish VAT registration once all final returns are filed and settled.

3. What happens to VAT on stock I don’t sell before closing?

Ans: It’s treated as a deemed supply and needs to be accounted for in your final VAT return, whether you retain it, write it off, or dispose of it another way.

4. Does closing my Amazon or eBay seller account cancel my VAT obligations?

Ans: No. The marketplace account and your tax registrations are entirely separate. Closing one has no effect on the other, and outstanding marketplace activity can continue to affect a tax position you thought was already closed.

5. If stock is stored in another EU country, do I need to do anything before deregistering?

Ans: Yes. Clear or transfer the stock and close the local VAT registration in that country first — OSS and your Irish VAT registration never covered that separate obligation.

How Forti Helps

We handle the full sequence — OSS and VAT deregistration, foreign VAT closures tied to stored stock, and the underlying CRO position — so an ecommerce business closes cleanly across every channel, rather than leaving a registration open somewhere that resurfaces later.

Closing an Ecommerce Business? Talk to Forti First

Monthly bookkeeping and management accounts from €195/month + VAT

Irish company formation, CRO fee included: €250

OSS, VAT and multi-country deregistration support available for ecommerce sellers closing down

Already Stop Trading

Already Stopped Trading? Here’s How to Fix It — A Step-by-Step Guide to Restoring, Deregistering and Closing an Irish Company in 2026

In Part 1, we looked at why ‘stopped trading’ isn’t the same as ‘closed down,’ and what it costs when business owners leave that gap unresolved. This follow-up is the practical playbook: the exact steps to restore a struck-off company, deregister properly with Revenue, close a company the right way, or keep a dormant one compliant — with the current CRO fees and timelines for each route.

Step One: Work Out Which Situation You’re Actually In

Before picking a fix, confirm the starting point. The route — and the cost — depends entirely on which of these applies to you right now.

  • Your company is still on the CRO register, but annual returns are overdue — you’re at risk, but not yet struck off.
  • Your company has already been struck off and dissolved — you need restoration if you want it back.
  • Your company is trading-inactive but compliant so far — you want to formally mark it dormant or close it properly before anything lapses.
  • You stopped self-employment as a sole trader — your fix runs through Revenue and, if you registered a business name, the CRO’s RBN3 form.

Search the CRO’s public register (cro.ie) for your company name or number — it will show your last filed annual return and current status, which tells you immediately which path below applies.

Path A: Restoring a Struck-Off Company

If it’s been less than 12 months since dissolution — Administrative Restoration

1. File Form H1 through the CRO’s CORE portal. The filing fee is €300, payable by bank draft, CRO deposit account, or online payment — cheques are no longer accepted.

2. File every outstanding annual return, each with its financial statements. Late filing penalties apply per return (€100 plus €3/day, capped at €1,200), though on a restoration the cumulative late-filing exposure across the last three returns is capped at €3,600.

3. If the company was struck off for Revenue non-compliance rather than CRO non-filing, you’ll also need written confirmation from Revenue that all outstanding statements have been delivered before the CRO will process restoration.

4. Confirm the company still meets the Section 137 requirement for an EEA-resident director (or holds the relevant bond), and that director/secretary details are up to date.

5. Once the Registrar is satisfied, the company is restored and treated, for continuity purposes, as if it had never been dissolved — though the gap in filings and the strike-off itself remain on the public record permanently.

If it’s been more than 12 months — Court Order Restoration

After the 12-month administrative window closes, restoration can only happen through the High Court, under Section 738 of the Companies Act 2014, provided fewer than 20 years have passed since dissolution.

This route requires a solicitor, a letter of no objection from the CRO’s Enforcement Section, confirmation from Revenue that all liabilities are discharged, and a court hearing before the order is filed with the CRO (a further €15 fee). It is slower, adds legal costs on top of the same outstanding CRO penalties and Revenue confirmations, and can take several months from start to finish — which is exactly why administrative restoration, actioned promptly, is the route worth protecting.

Path B: Closing a Company Properly (Voluntary Strike-Off)

If the company is solvent, has no outstanding creditors, and you genuinely want to close it rather than restore or reactivate it, voluntary strike-off is the cheapest and cleanest route — a fraction of the cost of letting the CRO strike it off involuntarily and dealing with the fallout later.

1. Confirm the company meets the Section 733 conditions: it has ceased trading (or never traded), has no assets or liabilities, and is not the subject of any court proceedings.

2. Ensure all Revenue tax registrations are cancelled and any final returns filed — the CRO’s H15 process assumes no outstanding Revenue position.

3. File Form H15 through CORE. The filing fee is €15.

4. Place a newspaper advertisement (published within 30 days of your CRO submission) announcing the intention to strike off, and submit the full page of that newspaper alongside the H15.

5. The CRO publishes a notice in the CRO Gazette. Any party has 90 days to object using Form H16; if no valid objection is received, the company is struck off and dissolved in an orderly, planned way — not an enforcement action against you.

Path C: Deregistering Correctly With Revenue

Whether you’re closing a company, pausing it as dormant with no further tax activity, or winding up a sole trade, Revenue registrations don’t cancel themselves — you have to tell them.

1. Submit a Tax Registration Cancellation Notification (Form TRCN1), or cancel online through ROS/myAccount where the facility is available, for each registration that no longer applies: VAT, employer PAYE, Corporation Tax, or Income Tax.

2. File all outstanding returns up to the date of cessation first. Cancelling the registration stops future obligations — it does not remove liability for periods before the cessation date.

3. Account for VAT on any assets or stock retained at the point of deregistration; Revenue treats this as a deemed supply in your final VAT return.

4. If you employed staff, complete final payroll submissions and issue final pay and tax details before cancelling your employer PAYE registration.

5. Keep the cancellation confirmation Revenue issues — you’ll need it if you later apply to have a company restored to the CRO register, since the CRO requires written confirmation that all Revenue statements were delivered.

Path D: Keeping a Dormant Company Properly Compliant

If the plan is to keep the company on the register — perhaps to protect a name, hold an asset, or pause before restarting

dormancy is a valid, low-cost status, but it still comes with a fixed annual routine.

  • Hold a directors’ meeting before the financial year end to formally record the decision that the company is dormant and will claim the dormant company audit exemption, minuted in accordance with Section 365.
  • File the CRO annual return (Form B1) every year, on time, with a balance sheet carrying the required dormant company exemption statement.
  • Submit a nil Corporation Tax return (CT1) to Revenue within nine months of the financial year end, every year, without exception.
  • Leave VAT and employer PAYE registrations cancelled unless there’s a specific reason to keep them live — an unused live VAT number is one of the most common sources of unexpected penalties.
  • Diarise the Annual Return Date itself; missing it even for a genuinely dormant company triggers the same late fees and, after repeated lapses, the same loss of audit exemption as an active company.

A Quick Reference: Fees at Each Stage

CRO Fees Table 2026
Action CRO fee (2026)
Annual return (Form B1), filed online €20
Late filing penalty per return €100 + €3/day, capped €1,200
Voluntary strike-off (Form H15) €15
Administrative restoration (Form H1) €300
Court order restoration lodgement €15 (plus legal costs)
Business name cessation (Form RBN3) No fee

These are the direct CRO fees only. Revenue penalties, interest, and any professional fees for preparing outstanding accounts or liaising with Revenue sit on top, and are almost always the larger part of the final bill for anyone recovering from a lapse rather than acting proactively.

Case Studies: Three Business Owners Who Fixed It

Case Study 1 — Restored Within the 12-Month Window

A Dublin design consultancy discovered, eight months after the fact, that its company had been struck off for missing two annual returns. Because it was still inside the 12-month administrative window, the director filed Form H1, submitted both outstanding annual returns with accounts, paid the capped late filing penalties, and had the company restored within several weeks — materially cheaper and faster than the court route it would have needed a few months later.

Case Study 2 — A Clean Voluntary Strike-Off

A part-time online retailer decided to close permanently after two years of declining sales. Before applying to the CRO, the director cancelled the VAT registration, filed a final VAT return accounting for the small amount of remaining stock, and confirmed no creditors were outstanding. The Form H15 application, newspaper notice, and 90-day objection period ran smoothly, and the company was dissolved in an orderly way with no penalties and no restoration ever required.

Case Study 3 — Reactivating a Dormant Company Instead of Starting Fresh

A founder who had paused a company for eighteen months while exploring a new venture wanted to start trading through it again rather than incorporate a new entity. Because the company had continued filing its annual return and nil CT1 every year while dormant, reactivation simply meant registering for VAT and employer PAYE again and updating Revenue on the resumption of trading — no restoration, no penalties, and no gap in the company’s history.

(These case studies are illustrative composites reflecting patterns we see regularly among Irish business owners, not individual clients.)

Frequently Asked Questions

How quickly should I act once I realise a company has been struck off?

Immediately. Administrative restoration is only available within 12 months of dissolution — after that, the only route is a High Court application, which costs significantly more and takes considerably longer.

Can I do the administrative restoration myself, or do I need a solicitor?

Form H1 can be filed directly through CORE without a solicitor, provided you can gather the outstanding returns, accounts, and any required Revenue confirmation yourself. Court restoration, by contrast, generally requires a solicitor to prepare the court application.

What happens to contracts or a bank account if the company is later restored?

Restoration is treated, for continuity purposes, as though the company had never been dissolved, which is what makes it possible to pick up existing arrangements. In practice, banks and counterparties may still ask questions about the gap, so it’s worth having the restoration paperwork ready to show.

Do I need to cancel VAT before I can voluntarily strike off a company?

Yes, in practice. The voluntary strike-off process assumes no outstanding Revenue position, and a live VAT registration with returns still due will hold up or invalidate the application.

Is it cheaper to restore an old company or just incorporate a new one?

It depends on the value tied up in the old entity — its trading history, contracts, VAT registration, or name. If none of that matters, incorporating fresh is often simpler. If the company has an established track record, restoring it within the 12-month window is usually the better value.

What if I genuinely can’t afford the restoration or penalty costs right now?

Speak to Revenue and, where relevant, the CRO before the relevant deadlines pass. Revenue operates phased payment arrangements for tax debts, and addressing the position early — even in instalments — is materially better than letting a strike-off or court restoration become the only remaining option.

How Forti Helps

We handle the practical side of every path above — restoration filings, voluntary strike-off applications, Revenue deregistration, and ongoing dormant company compliance — so the paperwork gets done correctly the first time, rather than compounding into a bigger bill later.

Get Back on Track With Forti

Monthly bookkeeping and management accounts from €195/month + VAT

Irish company formation, CRO fee included: €250

Company restoration, voluntary strike-off and dormant company filing support available on reques

Whether you’re inside the 12-month restoration window, ready to close a company for good, or need a dormant company kept compliant, get in touch with the Forti team at forti.ie — the earlier you act, the fewer of these fees actually apply to you.


Stop Trading but Forgot to Close Properly

Stopped Trading but Forgot to Close Properly: The Real Cost of Walking Away From an Irish Company in 2026

Every year, Irish business owners quietly stop trading and assume that’s the end of it. It isn’t — and in 2026, with the CRO and Revenue both enforcing more actively than at any point in recent years, that assumption is proving very expensive.

The Misconception That Costs Thousands

Closing the laptop is not the same as closing the company. When a shop stops taking orders, a contractor stops invoicing, or a founder simply moves on to something else, the company or business name they used doesn’t disappear along with the activity. It stays on the register at the Companies Registration Office (CRO), and it stays live with Revenue, until someone formally deals with it.

Throughout 2026, both the CRO and Revenue have sharply increased enforcement. Following the Companies (Corporate Governance, Enforcement and Regulatory Provisions) Act 2024, the CRO has fully resumed involuntary strike-off action against non-filing companies, and Revenue continues to apply fixed penalties and daily interest on unresolved VAT and tax positions regardless of whether a business is actually trading. Directors who assume that silence equals closure are the ones most often caught out.

Five Ways a Business Can Be ‘Not Trading’ — and What Each One Requires

1. Dormant Company (Still Registered, No Activity)

Under Section 365 of the Companies Act 2014, a company is dormant if it has no significant accounting transactions during the financial year and its only assets or liabilities are permitted ones (such as amounts due to or from group companies). A dormant company can qualify for audit exemption regardless of its size — but it is not exempt from filing. It must still file an annual return (Form B1) with the CRO every year and submit a nil Corporation Tax return (CT1) to Revenue within nine months of its year end. The single most common mistake we see is a director assuming ‘dormant’ means ‘no filing needed.’ It doesn’t.

2. Ceased Trading, But the Company Is Still on the Register

This is the grey zone that catches most people out. The business has stopped operating, but the company was never formally struck off or dissolved. Every statutory obligation continues exactly as before: CRO annual returns, corporation tax returns, and — critically — VAT and payroll registrations, which don’t cancel themselves. If you were VAT registered and don’t tell Revenue you’ve stopped trading, Revenue’s systems will continue to expect returns and will issue estimated assessments and penalties when they don’t arrive.

3. Sole Trader Who Stopped Self-Employment

Sole traders have it slightly simpler but the obligations are just as real. You need to notify Revenue that you’ve ceased self-employment, cancel any VAT and employer PAYE registrations that no longer apply, and file a final Income Tax return covering the period up to cessation. If you traded under a registered business name, you’re also required to notify the CRO of the closure within three months.

4. Voluntary Strike-Off (Closing Down Properly)

This is the correct route for a solvent company with no outstanding creditors that genuinely wants to close. Directors apply to the CRO using Form H15, confirm the company has ceased trading and has no assets or liabilities, and place a newspaper advertisement confirming the intention to close. Done correctly, this results in an orderly, planned dissolution — the opposite of what happens when a company is simply abandoned.

5. Involuntary Strike-Off (What Happens When Nothing Is Done)

This is the default outcome of doing nothing. When annual returns go unfiled, the CRO issues a statutory notice, followed — if there’s no response — by a public notice in the CRO Gazette. If the company still doesn’t act, it is struck off and dissolved. From that date, the company ceases to exist as a legal entity, limited liability protection ends, and anyone continuing to trade through it is doing so in a personal capacity. The full process typically runs several months from the first missed deadline, but once the Gazette notice is published, the clock moves quickly.

The Revenue Side: Obligations That Don’t Switch Off on Their Own

Ceasing to trade doesn’t cancel your tax registrations — you have to do that deliberately. Revenue requires a formal cancellation request (Form TRCN1, or notification through ROS) for VAT, employer PAYE, and Corporation Tax registrations. Until that’s done, Revenue’s systems keep expecting returns.

  • VAT: a fixed penalty of €4,000 can apply for late or non-registration, non-submission of returns, or incomplete and incorrect returns — each treated as a separate default. Unpaid VAT accrues daily interest at approximately 0.0274% per day (roughly 10% annualised).
  • Income Tax, Corporation Tax and CGT: unpaid liabilities accrue daily interest at approximately 0.0219% per day.
  • Failure to pay or file outstanding returns after a registration is formally ceased can still result in penalties and interest for the periods up to the cessation date — cancelling the registration doesn’t erase what was already due.

These are not nominal late fees that fade away on their own. They compound the longer a business owner leaves the position unresolved, and Revenue’s enforcement has become considerably more systemised in the past year.

The CRO Side: The Filing Obligation That Survives Closure of the Business

Compliance Failure Table
Compliance failure Cost / consequence
Late annual return (Form B1) €100 + €3/day, capped at €1,200
Late filing (more than once in 5 years) Loss of audit exemption for 2 years
Forced statutory audit after losing exemption Approx. €2,000–€8,000 per year
Persistent non-filing Involuntary strike-off proceedings
Company struck off / dissolved Loss of limited liability protection

Beyond the direct fees, a strike-off record is permanent and public. It shows up in due diligence for future investment, financing, or directorships, and directors of dissolved companies can face disqualification proceedings brought by the Corporate Enforcement Authority in more serious cases. Restoring a struck-off company is possible — administrative restoration within twelve months of strike-off, or a High Court application after that — but both routes involve legal costs, accumulated penalties, and outstanding filings, all of which must be cleared before restoration is granted

Case Studies: Three Business Owners, Three Outcomes

Case Study 1 — The Ecommerce Founder Who Just Stopped

A Dublin-based Shopify seller closed their online shop after eighteen months, moved on to full-time employment, and assumed the company would ‘wind down on its own’ since there was no activity left. Two annual returns were missed. The CRO issued a statutory notice, then a Gazette notice, and the company was struck off and dissolved roughly five months later. The founder discovered this only when a supplier queried an old invoice — by then, restoring the company required a court application, accumulated late filing penalties, and legal fees that came to several times what a proper voluntary strike-off would have cost at the outset.

Case Study 2 — The Consultant Who Forgot to Deregister VAT

An IT contractor stopped trading through their limited company to take up a permanent role, but never submitted a VAT cancellation request. Revenue’s system continued to expect bi-monthly VAT returns. After several periods with no returns filed, fixed penalties and daily interest began accumulating on an account that had, in reality, no further business activity. The position was only resolved once the company engaged an accountant to formally cancel the VAT registration and negotiate the outstanding penalties — a process that took weeks and cost considerably more than the five-minute cancellation would have, had it been done at the time trading stopped.

Case Study 3 — The ‘Dormant’ Company That Wasn’t Filing

A holding company set up for a property investment sat dormant for three years while its director focused on other ventures, on the assumption that a dormant company had no filing obligations at all. In fact, the company had missed its CRO annual returns for two consecutive years. This triggered the loss of audit exemption for the following two years, meaning the eventual return to compliance required a full statutory audit of accounts that, in substance, contained almost no transactions — an audit bill running into thousands of euro for a company that had done, quite literally, nothing.

(These case studies are illustrative composites reflecting patterns we see regularly among Irish business owners, not individual clients.)

How to Close, Pause, or Keep a Company Compliant — Properly

Decide early whether you’re pausing (dormant) or ending (strike-off) — the obligations are different, and ‘I’ll figure it out later’ is how both get missed.

If dormant: hold a directors’ meeting to formally record the dormancy decision, and keep filing your annual return and nil CT1 every year without fail.

If ceasing trading permanently: cancel VAT, employer PAYE and any other Revenue registrations via TRCN1 or ROS, file final accounts and a final tax return, and settle any outstanding liabilities.

If closing the company entirely: use the voluntary strike-off process (Form H15) while the company is solvent and has no outstanding creditors — this is materially cheaper and faster than recovering from an involuntary strike-off later.

If you traded under a registered business name as a sole trader, notify the CRO of the closure within three months using Form RBN3.

Frequently Asked Questions

If my company isn’t trading, do I still need to file anything?

Yes. A dormant or non-trading company still must file its CRO annual return every year and submit a nil Corporation Tax return to Revenue. Only a company that has been properly struck off or dissolved has no further filing obligation.

Can I just let Revenue and the CRO strike the company off on their own?

You can, but it’s the most expensive way to close a business. Involuntary strike-off leaves accumulated penalties, a permanent public compliance record, and — if you need the company back — a restoration process that costs far more than a planned voluntary strike-off.

What happens to my personal liability if the company is struck off?

Limited liability protection ends on dissolution. If the business continues to operate in any form afterwards, it’s being carried on in a personal capacity, without the legal protection the company structure was providing.

I stopped trading as a sole trader — is there anything to file with the CRO?

Only if you registered a business name. In that case, you must notify the CRO of the closure within three months using Form RBN3. You’ll also need to notify Revenue and file a final Income Tax return.

Does cancelling my VAT registration clear penalties from before the cancellation?

No. Cancelling a registration stops future obligations; it doesn’t remove liability for returns or payments that were already due before the cessation date. Outstanding periods still need to be filed and settled.

Can a struck-off company be restored?

Usually yes. Administrative restoration is available within twelve months of strike-off provided all filings are brought up to date and penalties paid. After that window, restoration requires a High Court order, which involves legal costs and takes considerably longer.

What’s the cheapest way to avoid all of this?

Make the decision — dormant, wind down, or close — while the company is still in good standing, and act on it immediately rather than leaving it unresolved. Every one of the case studies above would have cost a fraction of the eventual bill if addressed in the first few months.

How Forti Helps

Whether a company is dormant, has stopped trading, or needs to be closed down properly, we handle the CRO filings and Revenue cancellations that keep the process clean — so it doesn’t turn into a strike-off, a forced audit, or a personal liability problem months down the line.

Talk to Forti Before You Walk AwayMonthly bookkeeping and management accounts from €195/month + VATIrish company formation, CRO fee included: €250Dormant company filings, VAT/PAYE deregistration and voluntary strike-off support available on request.

If you’re thinking about pausing, closing, or you’ve already stopped trading and aren’t sure what’s still outstanding, get in touch with the Forti team at forti.ie before the CRO or Revenue make the decision for you.


The Irish Amazon Seller’s Complete Tax & Accounting Guide 2026

The Amazon Opportunity — and Why Accounting Catches Sellers Out

Ireland has one of the fastest-growing cohorts of Amazon sellers in Western Europe. From cottage industry crafters selling handmade goods to entrepreneurs running six-figure private label operations from a home office in Leinster, the Amazon marketplace has opened up genuinely global distribution to Irish businesses of every size.

But there is a gap that catches almost every Amazon seller at some point: the gap between what Amazon pays you and what you actually owe Revenue. Amazon is extraordinarily good at getting your products in front of customers. It is not, however, your accountant, your tax adviser, or your compliance officer. The platform handles some VAT on your behalf in some markets — but the responsibility for your Irish income tax, your VAT registration obligations, your EU compliance, and your bookkeeping sits squarely with you.

The sellers who get into trouble are not usually the ones who are deliberately cutting corners. They are the ones who did not know what they did not know. This guide sets out to fix that.

€10,000
EU-wide distance selling threshold triggering OSS obligation
23%
Irish standard VAT rate on most goods
12.5%
Irish corporation tax rate on trading profits
DAC7
EU law — Amazon reports your sales data to Revenue quarterly

How Amazon Income Is Taxed in Ireland

Every euro of profit you make from selling on Amazon is taxable income in Ireland. The way that income is taxed depends on your business structure — whether you operate as a sole trader or through a limited company. Most new Amazon sellers start as sole traders and many stay that way; some reach a point where incorporation makes financial sense. We cover the comparison in Section 8.

Sole Traders — Self-Assessment and Form 11

If you sell on Amazon as a sole trader, your Amazon profits are added to any other income you have (employment, rental, investments) and taxed under the self-assessment system. You must:

  • Register for income tax with Revenue if your non-PAYE income exceeds €5,000 net or €30,000 gross in a tax year
  • File an annual Form 11 tax return by 31 October each year for the previous tax year (extended to mid-November if filing and paying via ROS)
  • Pay Preliminary Tax for the current year at the same time — typically 100% of your previous year’s liability, or 90% of your estimated current year liability
  • Pay Class S PRSI at 4.2% on your net trading profits (with a minimum contribution of €500/year)
  • Pay USC on all income above €13,000 per year — in bands of 0.5%, 2%, 3%, and 8%

Your Amazon profit is not your Amazon turnover. It is your sales revenue less all allowable business expenses. See Section 7 for a full list of what you can claim. This distinction matters enormously — many sole trader Amazon sellers overpay tax because they do not claim all the expenses they are entitled to.

THE PRELIMINARY TAX TRAP

A common shock for first-year Amazon sellers: when your business takes off and you file your first Form 11, you may owe both your first year’s tax balance and preliminary tax for the current year simultaneously. On profits of €50,000, that combined bill can easily reach €25,000–€30,000.
The fix is straightforward but requires planning: set aside approximately 30–35% of your net Amazon profits into a separate tax savings account every month. Do not wait for October to calculate what you owe.

Income Tax Rates (2026)

Income Level Rate Notes
First €42,000 (single person) 20% income tax Standard rate band — increases for married couples / civil partners
Above €42,000 40% income tax Higher rate on all income above threshold
USC Band 1: €0–€12,012 0.5% Universal Social Charge
USC Band 2: €12,013–€25,760 2%
USC Band 3: €25,761–€70,044 3%
USC Band 4: Above €70,044 8%
Class S PRSI (self-employed) 4.2% Minimum €500/year; rises to 4.35% from Oct 2026

A sole trader Amazon seller making €60,000 net profit in 2026 faces an effective total tax rate (income tax + USC + PRSI) of approximately 42–45% on the income above the standard rate band. This is a significant cost, and it is one of the primary reasons established Amazon sellers consider incorporating.

Limited Companies — Corporation Tax

A limited company pays corporation tax at 12.5% on Irish trading profits — substantially lower than the top personal income tax rate of 40%. However, corporation tax is only one layer: getting money from the company into your personal pocket involves salary (PAYE), dividends, or a combination, each with its own tax implications. We cover this in Section 8.

VAT Registration — Your Irish Obligations

VAT is one of the most frequently misunderstood obligations for Irish Amazon sellers — and one of the most expensive to get wrong. There are two distinct layers to think about: your Irish VAT obligations (whether you need to register here) and your EU VAT obligations (whether you need to register or use OSS in other member states). This section covers the Irish side. Section 4 covers the EU picture.

When Must an Irish Amazon Seller Register for VAT?

In Ireland, VAT registration is mandatory when your taxable turnover exceeds the relevant threshold:

Supply Type VAT Registration Threshold Notes
Goods €80,000 per year Most Amazon sellers selling physical products fall here
Services €40,000 per year Applies if your primary supply is a service rather than goods
Both goods and services Lower threshold applies If you supply both, use the goods threshold if goods dominate

Once registered, you must charge Irish VAT at the appropriate rate (23% standard rate for most goods), file VAT returns (typically bi-monthly), and pay VAT to Revenue on time. You can also reclaim input VAT on business purchases — including stock, packaging, software, and professional fees.

DO NOT WAIT UNTIL YOU HIT THE THRESHOLD

Many Amazon sellers only register for VAT when they realise they have already exceeded the threshold. At that point, they owe VAT on all sales from the date they should have registered — not the date they actually did. Revenue can also charge interest and penalties on the under-declared VAT.
If your Amazon business is growing quickly, get a VAT adviser involved early. Registering voluntarily before you hit the threshold is often the right move — particularly because VAT registration lets you reclaim input VAT on stock and business costs from day one.

What Irish VAT Rate Applies to My Products?

VAT Rate Applies To Examples
23% (Standard) Most physical goods Electronics, clothing, toys, tools, household goods
13.5% (Reduced) Certain goods and services Some building materials, hospitality-related goods
9% (Second reduced) Newspapers, certain sports facilities Limited application for most Amazon sellers
0% (Zero-rated) Children’s clothing/footwear, most food, books Exempt but still reportable on VAT return

Can I Reclaim VAT on My Amazon Costs?

Yes — once VAT registered, you can reclaim the VAT element of allowable business expenses, including:

  • Stock purchases from VAT-registered Irish or EU suppliers (who issue valid VAT invoices)
  • Packaging, labelling, and fulfilment materials purchased in Ireland
  • Software subscriptions that have an Irish VAT element
  • Professional fees (accountant, solicitor, consultant) from Irish VAT-registered providers
  • Import VAT paid on goods brought into Ireland from outside the EU (via C79 certificate)

Amazon’s fees themselves (referral fees, FBA fees) are generally subject to a reverse charge mechanism rather than direct VAT — your accountant will handle this correctly on your VAT return.

EU VAT, One Stop Shop (OSS), and Amazon FBA

If you sell on Amazon to customers across Europe — or if you use Amazon’s Fulfilment by Amazon (FBA) service with stock stored in EU warehouses — you have EU VAT obligations that go well beyond your Irish registration. This is the area where Irish Amazon sellers are most frequently non-compliant, and where the financial exposure can be largest.

The EU-Wide Distance Selling Threshold

Since July 2021, a single EU-wide threshold of €10,000 applies to cross-border B2C (business to consumer) sales. If your total cross-border B2C sales to EU customers across all countries combined exceed €10,000 in a calendar year, you are required to either:

  • Register for the One Stop Shop (OSS) in your home EU member state (Ireland) and file quarterly OSS returns accounting for VAT in each destination country, OR
  • Register for VAT individually in each EU country where you have customers

For most Irish Amazon sellers selling B2C across Europe, OSS is the correct and most efficient route — one return, filed in Ireland, covering all EU member states. However, OSS is not a complete solution for all Amazon sellers.

OSS Does NOT Cover Everything — FBA Changes the Picture

The One Stop Shop scheme only applies to cross-border B2C sales. It does not cover:

  • Sales from locally-stored stock — if Amazon holds your inventory in a German warehouse and you sell to a German customer, that is a domestic German sale, not a cross-border sale. It falls outside OSS and requires a German VAT registration.
  • Intra-community stock transfers — when Amazon moves your goods between fulfilment centres in different EU countries, those movements are treated as self-supplies and must be reported locally.
  • B2B (business to business) sales — OSS only applies to B2C transactions.

Import VAT — on goods imported from outside the EU, separate IOSS rules or local import VAT procedures apply.

PAN-EU FBA SELLERS – CRITICAL CHANGE FROM JANUARY 2026

If you use Amazon’s Pan-European FBA (Pan-EU FBA) programme, Amazon moves your stock between fulfilment centres in multiple EU countries to optimise delivery times. From 1 January 2026, Pan-EU FBA requires VAT registration in a minimum of five countries: Germany, France, Poland, Italy, and Spain.

Storing inventory in any EU country — even temporarily, even if Amazon moves it there without your direct instruction — creates a local VAT registration obligation in that country regardless of your sales volume. Many Irish FBA sellers are currently non-compliant with local VAT registrations in Germany, France, and Poland. Revenue authorities in those countries are now actively cross-referencing Amazon’s DAC7 data against their local VAT registration databases.

OSS Returns — Deadlines and Rates

If registered for OSS in Ireland, you file quarterly OSS returns through Revenue Online Service (ROS). Deadlines are:

Quarter Period Filing Deadline
Q1 January – March 30 April
Q2 April – June 31 July
Q3 July – September 31 October
Q4 October – December 31 January (following year)

Each OSS return must account for sales in each destination EU country at that country’s applicable VAT rate. VAT rates vary significantly across the EU — German standard VAT is 19%, French is 20%, Italian is 22%. Your accounting software or VAT service needs to apply the correct rate for each sale by destination country.

THE FIX

If you use FBA and sell across Europe, you almost certainly need specialist eCommerce VAT advice. The OSS + local registration combination that most Pan-EU FBA sellers require is not something a generalist accountant typically handles. Forti.ie specialises in exactly this — contact us for a VAT position review.

DAC7 — Why Revenue Already Knows What You’re Earning

Here is something every Irish Amazon seller needs to understand: Revenue does not rely solely on self-reported income to know what you earn on Amazon. Since January 2024, Amazon has been legally required to report your earnings directly to EU tax authorities under the DAC7 Directive — and it has been doing so on a quarterly basis.

What Is DAC7?

DAC7 (Council Directive 2021/514) is EU legislation that requires digital marketplace operators — including Amazon, Etsy, eBay, and Airbnb — to collect and verify information about their sellers and report that information to the relevant national tax authorities each year. In Ireland, Amazon reports to Revenue. Revenue then exchanges data with other EU member states.In Ireland, the reporting threshold that triggers DAC7 inclusion is €2,000 in total consideration or 30 or more transactions in a reporting period. The vast majority of active Amazon sellers will exceed both thresholds.

What Information Does Amazon Share with Revenue?

Amazon provides Revenue with the following seller information each reporting year:

  • Your full legal name and business name
  • Your address and Tax Identification Number (Irish PPS number or company tax number)
  • Your total gross sales revenue for the year, broken down by quarter
  • The number of transactions you completed
  • Any fees deducted by Amazon (referral fees, FBA fees, etc.)
  • Details of bank accounts to which Amazon pays you

WHAT THIS MEANS IF YOU HAVE NOT FILED

Revenue now has three years of DAC7 data on Irish Amazon sellers — covering 2023, 2024, and 2025 — all submitted by Amazon directly. In 2026, that represents sufficient historical data for Revenue to identify sellers who have not registered for income tax, not registered for VAT, or significantly under-declared their Amazon income./strong>

If your Amazon income has not been declared to Revenue, this is not a situation where you can hope it goes unnoticed. The data is already there. Acting now — via a voluntary qualifying disclosure — is significantly less costly than waiting for Revenue to make contact.

DAC7 and You — What To Do

If you are a compliant Irish Amazon seller with all income declared, VAT filed, and tax returns submitted accurately, DAC7 is not a problem. It is simply Revenue having visibility that matches what you have already told them.

If you are not yet compliant, or uncertain about your compliance position, the correct approach is:

1. Conduct a compliance review

Establish what income has been earned, what has been declared, and what the gap might be.

2. Quantify any underpayment

Work out the income tax, USC, PRSI, and VAT that may be outstanding.

3. Make a qualifying disclosure

Before Revenue contacts you, a voluntary qualifying disclosure significantly reduces penalties — from up to 100% of the underpayment down to 3–20%. The window is before Revenue initiates contact about a specific liability.

4. Get compliant going forward

Register for income tax and VAT as required, file returns, and maintain proper records.

Amazon Bookkeeping — Reconciling Your Payouts

Amazon’s payment system is notoriously complex from a bookkeeping perspective. The amount that lands in your bank account every two weeks is not your revenue — it is a net settlement figure after Amazon has deducted dozens of line items including referral fees, FBA fees, advertising charges, storage fees, returns, refunds, and adjustments. Treating your bank deposits as your income figure is one of the most common — and most expensive — accounting mistakes Irish Amazon sellers make.

Understanding Your Amazon Settlement

Each Amazon settlement report contains:

Item What It Represents Tax Treatment
Product sales Gross revenue from customer purchases Taxable income — record as turnover
Shipping credits Amounts customers paid for shipping Taxable income if you receive it
Referral fees Amazon’s commission (typically 8–15% of sale price) Allowable business expense
FBA fees Picking, packing, and shipping fees charged by Amazon Allowable business expense
FBA storage fees Monthly charges for warehouse space Allowable business expense
Advertising (PPC) Amazon Sponsored Products / Brands costs Allowable business expense
Returns and refunds Gross refunds to customers Reduces turnover; also releases some fees
Promotional rebates Discounts funded by Amazon Reduces gross revenue
Vine programme fees Costs for Amazon Vine review programme Allowable business expense
Loan repayments Amazon Lending repayments if applicable Principal is balance sheet; interest is P&L

Correct Bookkeeping Methodology

The correct approach for Amazon seller bookkeeping is:

  1. Record gross product sales as turnover — not the net settlement amount
  2. Record each category of Amazon fees as a separate expense line — this gives you visibility on your cost structure and ensures all deductible costs are captured
  3. Reconcile your settlement reports to your bank deposits every settlement period — any discrepancy needs to be investigated
  4. Track inventory purchases separately as stock (a balance sheet item, not immediately an expense — it becomes cost of goods sold when the items are sold)
  5. Record VAT separately from revenue, particularly if selling to OSS-liable countries at different rates
  6. Maintain records of returns and refunds by month to correctly adjust your VAT position

Software Recommendations for Amazon Sellers

Managing Amazon bookkeeping manually in a spreadsheet becomes impractical above modest volumes. The following platforms integrate with Amazon Seller Central and can import settlement data automatically:

  • A2X — specifically built for Amazon sellers; automatically categorises Amazon transactions and maps them to accounting software
  • Xero or QuickBooks — combined with A2X for automated settlement reconciliation; both support Irish VAT returns and OSS filing
  • Linnworks or Katana — for sellers with complex multi-channel inventory management needs

Whatever software you use, the key is ensuring your data is reconciled correctly before your accountant files your returns. Garbage in, garbage out — and in this case, garbage out means an incorrect tax return and the risk of Revenue scrutiny.

THE FIX

A dedicated eCommerce accountant who understands Amazon’s settlement structure will save you significantly more than their fee in correctly claimed expenses and correctly filed VAT returns. Forti.ie works with Amazon sellers across Ireland — contact us to discuss your bookkeeping setup.

Allowable Expenses for Amazon Sellers in Ireland

One of the most significant ways an Irish Amazon seller can legally reduce their tax bill is by correctly identifying and claiming all allowable business expenses. Your taxable profit is your revenue minus allowable expenses — every euro of genuinely incurred business expense that you fail to claim increases your tax bill unnecessarily.Revenue allows deductions for expenses that are wholly and exclusively incurred for the purpose of the trade. For Amazon sellers, the following categories typically qualify:

Cost of Goods Sold (COGS)

The single largest deductible expense for most Amazon sellers. This includes:

  • Purchase price of inventory sold during the year
  • Import duties, customs charges, and freight costs on stock purchases
  • Cost of product samples and testing
  • Quality inspection fees paid to third-party inspectors (e.g. in China)

Note: Inventory that has not yet been sold is a balance sheet asset (stock), not an immediate expense. Only the cost of goods actually sold in the tax year is deducted from that year’s profit.

Amazon Platform Fees

  • Referral fees (Amazon’s commission on each sale)
  • FBA fees (pick, pack, and ship per unit)
  • FBA storage fees (monthly and long-term storage)
  • Amazon Seller Central subscription (Individual or Professional plan fee)
  • Sponsored Products and Sponsored Brands advertising spend
  • Amazon Vine programme fees
  • Returns processing fees
  • Removal and disposal fees for stranded or unsellable inventory

Logistics and Fulfilment

  • Freight forwarder fees (sea or air freight from supplier to Amazon warehouse)
  • Courier and shipping costs (if using FBM — Fulfilment by Merchant)
  • Third-party logistics (3PL) costs if you use a prep centre in Ireland or the UK
  • Packaging, labels, poly bags, bubble wrap, cartons

Professional and Software Costs

  • Accountant and bookkeeper fees
  • VAT compliance and OSS filing services
  • Legal fees (contracts, IP protection, trademark registration)
  • Amazon seller tools (Helium 10, Jungle Scout, Keepa, SellerApp)
  • Accounting software (Xero, QuickBooks)
  • A2X or similar transaction management tools
  • Photography, graphic design, and brand asset creation

Other Allowable Expenses

  • Home office costs — a proportion of rent/mortgage interest, utilities, and broadband if you work from home (Revenue approved method)
  • Business banking fees and payment processing charges
  • Relevant training courses, books, and subscriptions
  • Travel expenses for supplier visits or trade shows (wholly business-related)
  • Capital allowances on equipment (computer, camera, office furniture) at 12.5% per year over 8 years

EXPENSES THAT ARE NOT ALLOWABLE

The following are commonly claimed incorrectly and disallowed by Revenue: personal clothing (unless a uniform or specialist protective clothing), meals and entertainment without a clear business purpose, personal phone costs not exclusively for business, and capital items expensed as revenue (they must be capitalised and claimed via capital allowances).

Sole Trader vs Limited Company for Irish Amazon Sellers

The question of whether to operate as a sole trader or through a limited company is one of the most important financial decisions an Irish Amazon seller can make. The right answer depends on your profit level, your personal financial situation, and your plans for the business. There is no universal correct answer — but there are clear indicators.

SOLE TRADER — DRAWBACKS

  • ✗ All profits taxed at personal rates (up to 40% + USC + PRSI)
  • ✗ Combined effective tax rate can exceed 50% on higher earnings
  • ✗ Personal liability for all business debts
  • ✗ Less scope for tax planning and retained earnings
  • ✗ May look less credible to some suppliers

LIMITED COMPANY — ADVANTAGES

  • ✓ 12.5% corporation tax on trading profits
  • ✓ Profits retained in company taxed at 12.5% vs 40%+ personally
  • ✓ Limited liability protection
  • ✓ More tax planning options (salary + dividends)
  • ✓ Can own IP, assets, invest surplus profits tax-efficiently

When Does Incorporation Make Sense for an Amazon Seller?

As a general rule of thumb, incorporation typically makes financial sense when your Amazon net profit exceeds €40,000–€50,000 per year and you do not need to extract all of that profit personally to live on. If you can leave retained profits in the company (investing in stock, growth, or other purposes), the tax saving from paying 12.5% corporation tax instead of 40%+ personal income tax is substantial.An Amazon seller making €80,000 net profit as a sole trader might face a combined income tax / USC / PRSI bill of around €34,000–€38,000. The same profit in a limited company paying corporation tax at 12.5% results in a company tax bill of €10,000 — leaving €70,000 in the company. The director then draws a tax-efficient salary (typically set to maximise PRSI credits without hitting the 40% band) and takes the remainder as dividends when and if needed.

INCORPORATION IS NOT ALWAYS THE RIGHT MOVE

A limited company comes with additional compliance costs: annual CRO filing, directors’ returns, corporation tax returns (Form CT1), potential audit requirements at higher turnover, and payroll to run if you pay yourself a salary. The accounting fees are higher. For a seller making €30,000 net profit who needs all of that to live on, the tax savings from incorporation may not outweigh the compliance costs.

Take professional advice before incorporating. Forti.ie will model the tax position for you across both structures so you can make an informed decision based on your specific numbers.

Case Studies

The following case studies are based on real client situations handled by the Forti.ie team. Names, identifying details, and specific figures have been changed or anonymised. They are illustrative of the types of challenges Irish Amazon sellers face and how specialist accounting support resolves them.

1. The Handmade Goods Seller Who Did Not Know About VAT

Background:

A sole trader in the west of Ireland had been selling handmade homeware products on Amazon.co.uk and Amazon.de for three years, building turnover to approximately €95,000 per year. She operated from home and managed everything herself, including her own bookkeeping on a spreadsheet.

The Problem:

When she came to Forti.ie, she had never registered for VAT in Ireland and had not filed a self-assessment tax return for any of the three years she had been trading. She was aware she should probably be doing something but had not known what. Her combined unpaid Irish income tax, VAT, and PRSI across three years was estimated at approximately €48,000 before interest and penalties. She had also not registered for VAT in Germany despite having significant sales to German customers — a separate exposure.

What We Did:

We conducted a full compliance review, reconstructed her accounts for all three years from Amazon settlement reports and bank records, and quantified the exact liability. We then prepared and filed an unprompted qualifying disclosure with Revenue for the Irish liabilities. Simultaneously, we engaged a German VAT agent to address the German registration and file back-returns with the German tax authority under their voluntary disclosure equivalent.

The Outcome:

The qualifying disclosure resulted in penalties being capped at 3% of the Irish liability rather than the potential 100%. The total amount paid, including all tax, PRSI, VAT, interest, and penalties, was approximately €54,000 — substantially less than the unmanaged exposure would have been. She was then set up with a proper accounting and VAT compliance system going forward, including quarterly OSS filings through Revenue.

2. The FBA Seller Unaware of Pan-EU Stock Obligations

Background:

A private label seller in Dublin had been using Amazon Pan-European FBA for two years, selling into markets across Germany, France, Spain, Poland, and Italy. He was VAT-registered in Ireland and filed regular Irish VAT returns. He believed he was compliant because he had ‘sorted VAT’. His turnover had grown to approximately €320,000 across EU markets.

The Problem:

A review of his account revealed he had VAT registration obligations in Germany, France, Poland, Spain, and Italy due to Amazon storing his inventory in fulfilment centres in all five countries. He had no local VAT registrations in any of those countries. His Irish VAT return was also incorrectly treating EU sales as if OSS applied to all of them — but OSS cannot cover domestic sales from locally-stored stock. Additionally, DAC7 data submitted by Amazon to German tax authorities had flagged his inventory presence and triggered a registration demand letter from the German Finanzamt.

What We Did:

Forti.ie coordinated VAT registrations in all five required countries through specialist local agents in each jurisdiction. Back-filings were completed in Germany, France, and Poland under their respective voluntary disclosure frameworks where available. His OSS filings were reconstructed to correctly exclude domestic sales from local stock. His Irish VAT returns were also corrected to remove the incorrectly claimed input VAT on German import VAT (which should have been reclaimed locally in Germany).

The Outcome:

The total cost of remediation — registrations, back-filings, penalties, and professional fees across all jurisdictions — was approximately €28,000. Had he waited for Revenue authorities in each country to complete their investigations, the exposure would have been significantly higher. His business is now fully compliant across all five EU markets with automated VAT filing managed by Forti.ie on an ongoing basis.

3. The Successful Seller Who Incorporated at Exactly the Right Time

Background:

A sole trader in Cork had been selling sports nutrition products on Amazon for four years, growing from a side income to a primary income of approximately €110,000 net profit per year. He was registered for income tax and VAT, filed his Form 11 on time each year, and had a reasonable grasp of his obligations. His problem was a growing tax bill: as a sole trader on €110,000 net profit, he was paying approximately €48,000 in combined income tax, USC, and PRSI — leaving him €62,000 to live on.

The Problem:

He approached Forti.ie asking whether incorporation would save him money, and if so, when and how to do it. He had heard from other sellers that a limited company would reduce his tax bill but was unclear on the specifics and worried about compliance complexity.

What We Did:

We modelled his tax position across four scenarios: remaining as a sole trader; incorporating immediately; incorporating and paying himself a salary only; incorporating and taking salary plus dividends. The analysis showed that by incorporating and drawing a salary of €42,000 (using the full standard rate band) plus dividends of €25,000 at a point that suited his personal cash needs, his overall tax position could be improved materially. The remaining profits, retained in the company and reinvested in stock, were taxed at 12.5% rather than at personal rates. We managed the incorporation, registered the company with the CRO and Revenue, transferred trading to the new entity, set up payroll, and established the correct dividend policy.

The Outcome:

In the first full year of trading through the limited company, his combined personal and company tax bill reduced from approximately €48,000 to approximately €27,000 — a saving of €21,000, against annual accounting fees of €3,800. The retained profits in the company are now being used to fund new product launches. He has since expanded to three additional product lines and is on track for €200,000 turnover this year.

Frequently Asked Questions

The following questions are among the most common we receive from Irish Amazon sellers. They cover the practical day-to-day compliance questions that arise when running an Amazon business in Ireland in 2026.

Do I need to register for VAT to sell on Amazon in Ireland?

Not immediately — but you may need to sooner than you think. If your Amazon turnover from goods exceeds €80,000 in a 12-month period, VAT registration in Ireland is mandatory. However, even below this threshold, you may need to register for EU OSS if your cross-border EU sales exceed €10,000. And if you use Amazon FBA with stock stored in other EU countries, you may need local VAT registrations in those countries regardless of your sales volume. Review your position early — do not wait until you breach a threshold.

Does Amazon collect and pay VAT on my behalf?

It depends on the marketplace and transaction type. Amazon operates as a deemed supplier for certain sales — particularly sales by non-EU sellers to EU customers. For Irish-registered Amazon sellers selling on Amazon.co.uk or EU marketplaces, Amazon may collect and remit VAT in certain circumstances (e.g. UK sales under the UK marketplace facilitator rules). However, for your Irish VAT obligations and your OSS obligations on cross-border EU sales, you remain responsible. Amazon’s VAT Calculation Service can assist with setting correct VAT rates, but it does not file your returns or manage your registrations. Do not assume Amazon has handled your VAT compliance.

I sell on Amazon as a hobby — do I still owe tax?

If you are making a profit — even occasionally — Revenue takes the view that this is a taxable trade, not a hobby. The distinction between hobby and trade in Irish tax law is not based on how casually you approach the business; it is based on whether you are engaging in a systematic and sustained effort to make a profit. Most Amazon sellers, even those who started as hobbyists, meet this test. If your non-PAYE income (including Amazon income) exceeds €5,000 net or €30,000 gross in a tax year, you must register for self-assessment and file a Form 11.

What is DAC7 and does it affect me?

DAC7 is EU legislation that requires digital marketplace operators (including Amazon) to report seller earnings and transaction details to EU tax authorities annually. In Ireland, Amazon reports directly to Revenue. The threshold that triggers inclusion in DAC7 reporting is €2,000 in total income or 30 or more transactions in a reporting period. The vast majority of active Amazon sellers exceed this. Since January 2024, Amazon has submitted annual DAC7 reports to Revenue. Revenue now has several years of data on Irish Amazon sellers’ earnings — making undisclosed Amazon income significantly easier to identify.

What is the One Stop Shop (OSS) and do I need to use it?

The One Stop Shop (OSS) is an EU VAT simplification scheme that allows you to file a single quarterly VAT return in Ireland covering B2C sales to customers in all 27 EU member states, rather than registering for VAT in each country individually. You need to use OSS (or register locally in each country) once your total cross-border EU B2C sales exceed €10,000 per year. OSS does not cover sales of goods stored in other EU countries — those require local VAT registrations regardless of the OSS threshold.

Should I use Amazon FBA or FBM from a tax perspective?

From a pure Irish tax perspective, both FBA and FBM create the same Irish income tax obligations. The difference arises with EU VAT: FBA significantly increases your EU VAT complexity because Amazon may store your goods in multiple EU countries, creating local VAT registration obligations in each of those countries. FBM (Fulfilment by Merchant), where you ship directly from Ireland, typically only creates OSS obligations for cross-border B2C sales above €10,000. Many sellers choose FBA for its operational and sales rank benefits, but they should do so with full awareness of the VAT compliance requirements — and budget for the cost of managing multiple EU VAT registrations.

How far back can Revenue go if I have not declared my Amazon income?

Revenue can generally go back 4 years for innocent errors in self-assessment. Where deliberate non-compliance, fraud, or neglect is involved, there is no fixed time limit. Given that DAC7 reporting started for the 2023 tax year (submitted by Amazon in January 2024), Revenue now has at minimum the 2023 and 2024 tax years as a starting point. The appropriate response if you have undisclosed Amazon income is to take professional advice and make an unprompted qualifying disclosure to Revenue before Revenue contacts you. This significantly reduces the applicable penalties.

What expenses can I claim against my Amazon income?

You can claim any expense that is wholly and exclusively incurred for the purpose of your Amazon trade. This includes cost of goods sold (inventory), Amazon fees (referral, FBA, advertising, storage), freight and logistics costs, packaging, accounting and VAT compliance fees, Amazon seller tools and software, a portion of home office costs, capital allowances on business equipment, and professional development costs. You cannot claim personal expenses, the personal portion of dual-purpose costs, or capital items that should be depreciated via capital allowances.

When should I consider incorporating my Amazon business as a limited company?

The general trigger point for considering incorporation is when your Amazon net profit exceeds €40,000–€50,000 per year and you do not need to extract all of that profit personally for living expenses. The tax saving from paying 12.5% corporation tax on retained profits versus 40%+ personal income tax on those same profits can be substantial. However, incorporation also brings additional compliance costs (payroll, CT1 returns, CRO filings, higher accounting fees) that need to be weighed against the tax savings. Take professional advice before making this decision — the right answer depends on your specific financial situation.

What records do I need to keep as an Irish Amazon seller?

You are required to maintain records for a minimum of 6 years from the end of the relevant tax year. Records should include: Amazon settlement reports for all periods, purchase invoices for all stock and business expenses, records of inventory (opening stock, purchases, closing stock), bank statements, VAT records (sales, purchases, OSS returns), and correspondence with Revenue. Amazon settlement reports can be downloaded from Seller Central — we recommend downloading and archiving these monthly, as historical data may not be available indefinitely.